








How does a failed BTC treasury company complete the delisting process?
 Core Viewpoint

 This company sold its last BTC, demonstrating the most complete "exit sample."
Author: Azuma, Odaily Planet Daily
From Strategy to Bitmine, over the past two years, we have witnessed the rise of numerous cryptocurrency treasury companies (DAT) ------ some have accumulated massive amounts of BTC through continuous financing, while others have made heavy bets on altcoins like ETH, and some previously inconspicuous listed companies have transformed into agents for crypto assets in the public stock market through this model.
This model was once quite effective; as long as a company's stock could obtain a premium above its net asset value, it could continue to finance, continue to buy coins, and further increase market attention… But have you ever thought, what if one day this game can no longer be played, how should a cryptocurrency treasury company exit?
Today, we are witnessing the answer to this question with the UK-listed company Satsuma ------ sell BTC, close the business, return the majority of capital to shareholders, and then voluntarily exit the stock trading market.
With the planned delisting date of September 14 officially approaching, Satsuma is about to become the first case in the past two years of the treasury craze to actively complete the "liquidate BTC → return capital → ultimately delist" process ------ although there have been similar cases before, Profusa managed to maintain its listing status under delisting pressure, while DigiAsia chose to delist due to mergers and restructuring, which is different from Satsuma's situation.
How did Satsuma get to this point?
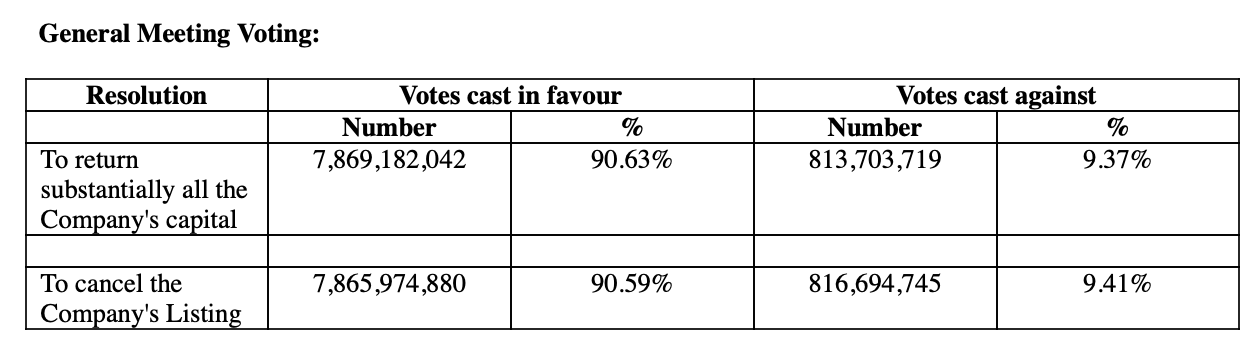
On July 20, 2026, Satsuma held a shareholder meeting to vote on two special resolutions: one was to return the majority of the company's capital to shareholders; the other was to cancel the company's listing qualification on the FCA Official List.
The results were not surprising, the first resolution received 90.63% approval, and the second received 90.59% approval. After the shareholder vote passed, the board immediately began preparing to close the company's trading activities and started selling the remaining 669 BTC holdings.
This was not a sudden decision. In fact, Satsuma's BTC treasury strategy had long been in trouble. Since shifting to the treasury route, Satsuma had accumulated 1199 BTC, but the average cost of acquisition exceeded $113,000. As BTC prices fell, the value of the BTC assets on the company's books rapidly shrank, and the valuations given by the capital markets also declined.
In December 2025, Satsuma once sold 579 BTC in one go, accounting for about half of its holdings at the time, fetching about £40 million (approximately $93,057 at the current exchange rate), but the purpose of this transaction was not to actively reduce BTC exposure, but to address liquidity pressure ------ the company needed to repay a convertible bond of about £78 million that was due that month. However, the subsequent situation did not improve; BTC prices continued to decline, and Satsuma's cash flow pressure grew increasingly severe.
At this point, the reverse drawbacks of the BTC treasury model had begun to fully expose themselves in Satsuma ------ when the company needed to rely on selling BTC to repay debts, the original cycle of "financing → buying coins → refinancing" became very difficult to continue.
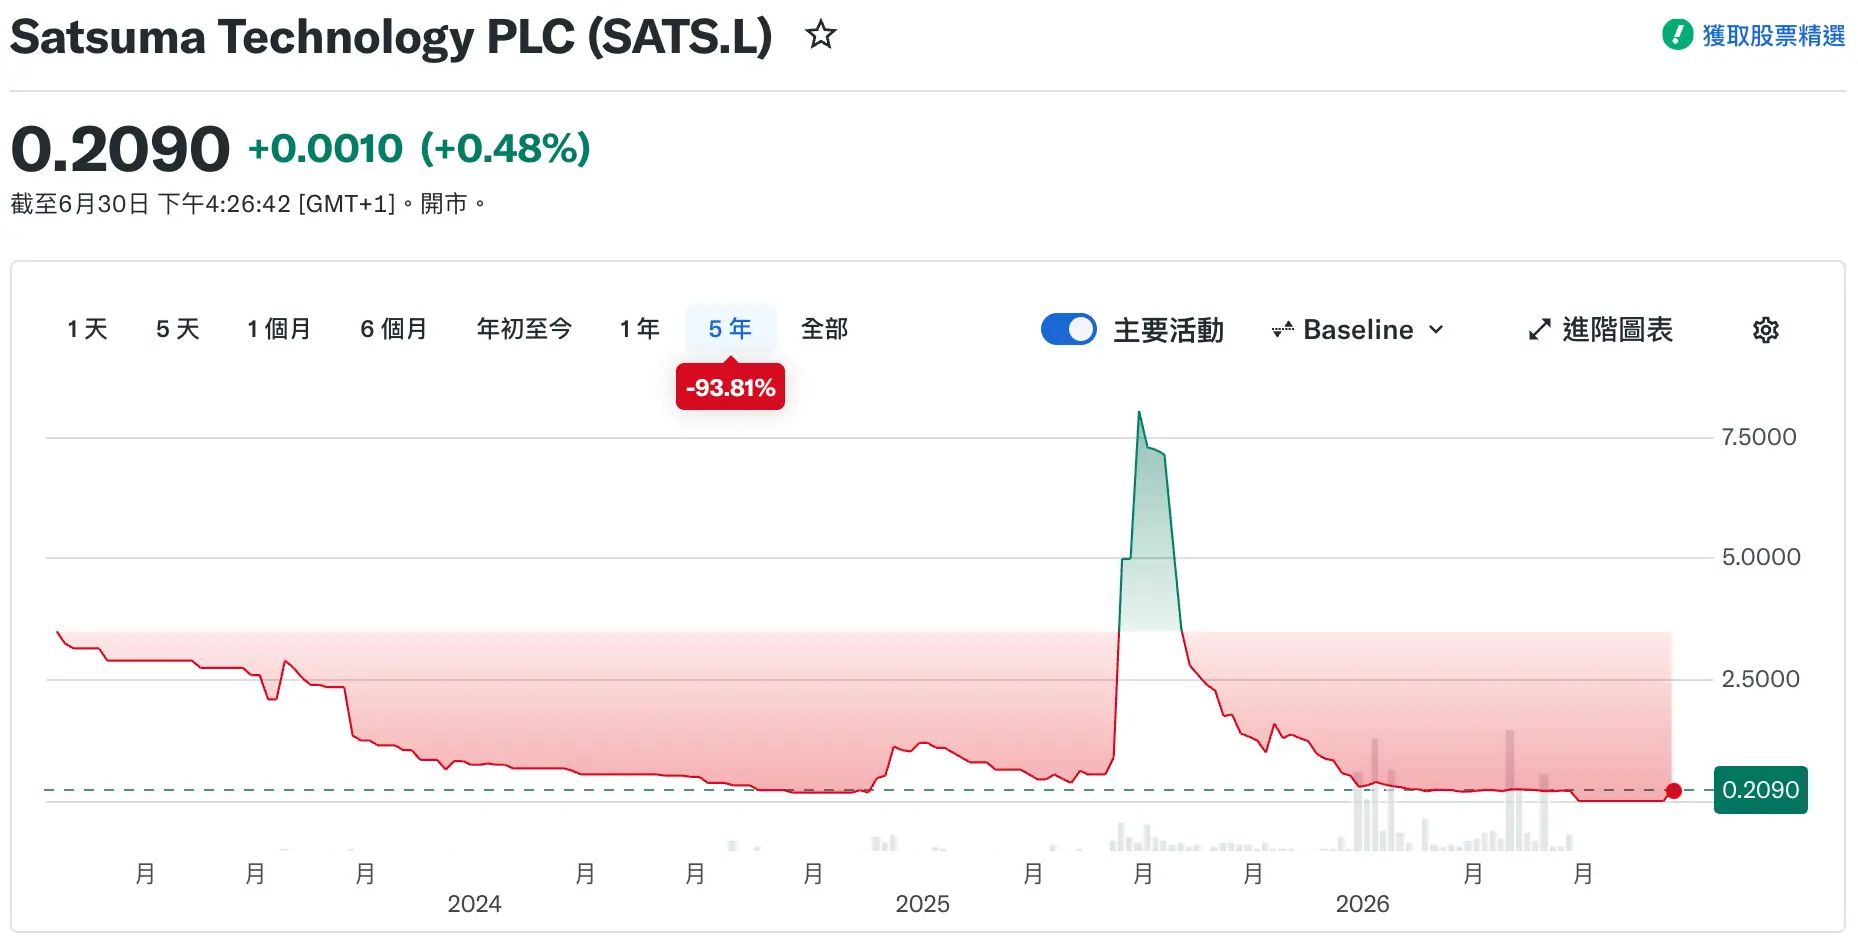
The performance on the stock price side was even more exaggerated. Based on the peak in June 2025, by the time of the delisting vote in July this year, Satsuma's stock price had cumulatively dropped by about 99%, and its market value even once fell below the value of the BTC it held.
In other words, the market was no longer willing to pay a premium for this BTC treasury company, and thus, the significance of maintaining this listed entity itself began to be questioned. In April 2026, one of Satsuma's largest institutional shareholders, Pantera Capital, publicly urged the company to abandon the treasury model, sell the remaining BTC, and return cash to shareholders. Subsequently, shareholders holding more than 20% of the company's shares jointly requested a shareholder meeting, ultimately pushing forward the capital return and delisting proposal.
In the end, over 90% of shareholders chose to support the capital return and delisting, and Satsuma thus officially ended its story as a BTC treasury company.
What steps must a DAT take to voluntarily delist?
The remaining question is how to execute the delisting, and Satsuma has provided a complete demonstration for the market.
The first step is for the shareholder meeting to pass a special resolution. A company cannot simply decide to close the listed entity based on the board's decision. Satsuma first needed to let shareholders vote on whether to agree to return capital and cancel the listing qualification.
The second step is to determine the final shareholders entitled to receive capital return and the number of shares. Satsuma chose to return capital through "B Shares," and after the registration period ended, it was ultimately confirmed that there were 11,235,874,700 shares. This is important because how much each share can receive back mainly depends on two variables ------ how much asset the company ultimately has left, and how many shares participate in the distribution.
The third step is to sell BTC, close the business, and clean up the balance sheet, which is also the most critical step in the DAT exit process, meaning it will transform from a listed company holding BTC into a liquidation entity waiting for the distribution of remaining cash. From July 24 to July 31, Satsuma sold all of its remaining 669 BTC, totaling about £31.91 million (approximately $64,226 at the current exchange rate).
The fourth step is for the court to confirm the capital return plan, which is also a relatively special part of the UK company law process. On September 8, the High Court of England approved Satsuma's cancellation of 11,235,874,700 "B Shares" and returned about £30.72 million to shareholders, thus the return amount for each "B Share" was determined to be £0.002734.
The fifth and final step is to delist and complete asset distribution to shareholders. According to the timetable previously announced by Satsuma, the company will complete the delisting on September 14, and eligible shareholders are expected to receive their "refund" on September 28. Only at this point can a BTC treasury company be considered to have truly completed its exit.
Another challenge for treasury companies
Satsuma's story cannot simply be understood as a failed example of the cryptocurrency treasury model. After all, leading companies like Strategy and Bitmine are still continuously expanding their asset scale, but for smaller DATs with limited financing capabilities, when BTC falls, stock prices drop below net assets, and even financing becomes difficult, "continuing to hoard coins" is no longer the only answer.
In a sense, how to buy BTC is only the first half of the treasury company's journey; how to exit is the second half it must face. Satsuma's process from shareholder voting to liquidating BTC, returning capital, court approval, and final delisting also provides a fairly complete "exit manual" for future entrants.
As more and more companies enter the DAT track, the market may also need to start paying attention to another indicator: a treasury company must not only have the ability to buy BTC but also the ability to safely return assets to shareholders when the rules of the game change.
 Risk warning
Popular articles





