








I went to Almaty, and I re-evaluated Kazakhstan's payment system
 Core Viewpoint

 When Payment is sufficiently Digital, how can we truly achieve Interoperable?
Author: Xu Chen Steven, Payment 201
Last week, I was on a business trip in Almaty.
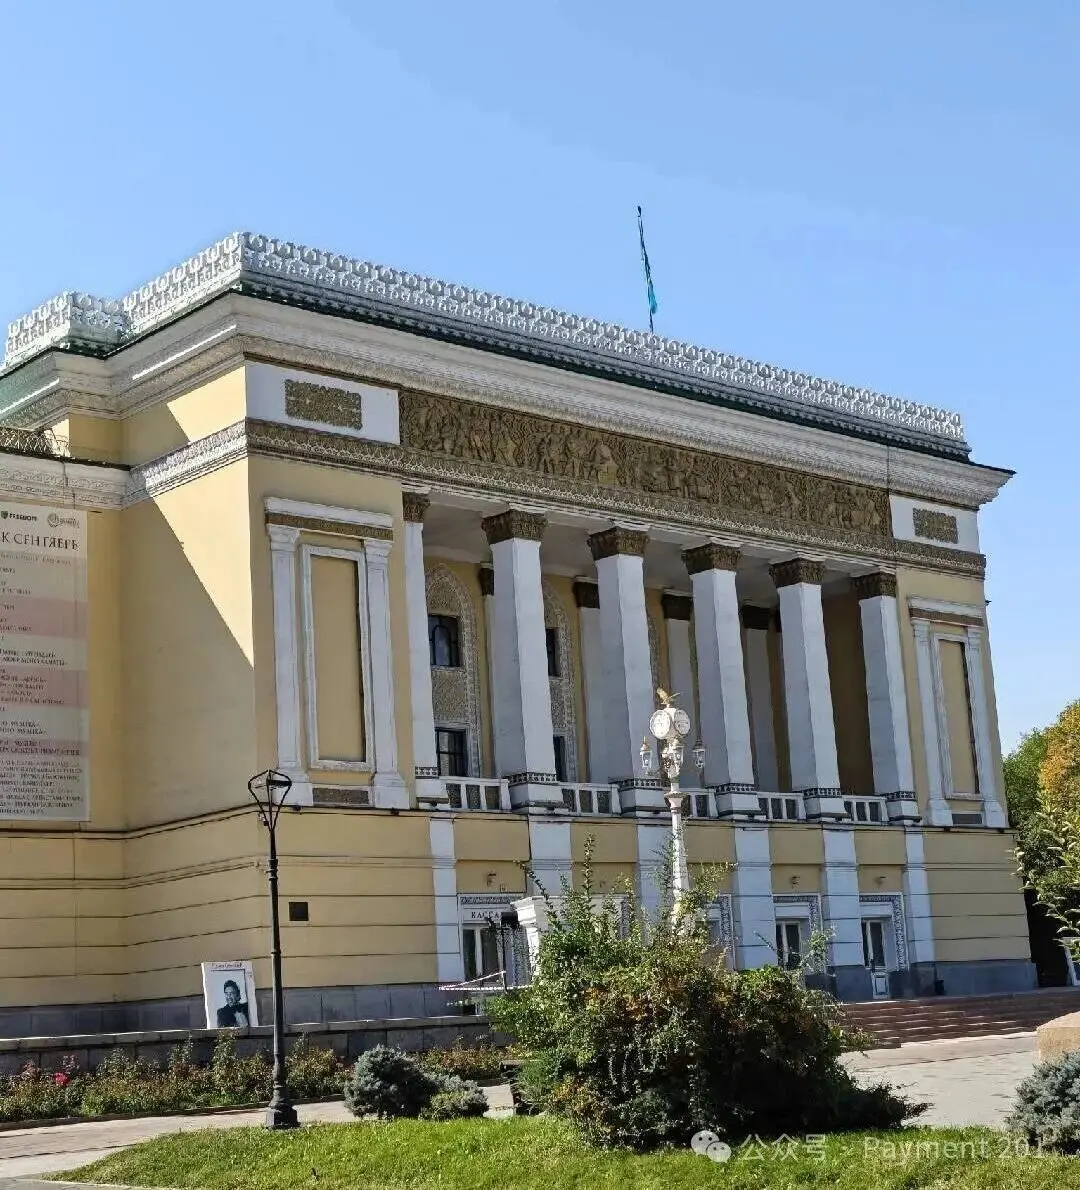
This was also my first time in Kazakhstan. Before going, I imagined it might resemble cities like Phnom Penh or some in Vietnam. However, upon arrival, I found Almaty to be quite clean, with streets, buildings, and even the overall feel of the city having a hint of Southeast European flavor.
Yet, there is often a sense of dust in the air.
The roads are wide, with new buildings, roads, and various infrastructures under construction everywhere, but when actually walking on the streets, it feels like there aren't many people.
After all, this is a country with a land area close to 2.7 million square kilometers and a population of only over 20 million.
The land is too vast, and the population is too small.
As of August this year, Kazakhstan's population is approximately 20.6 million.
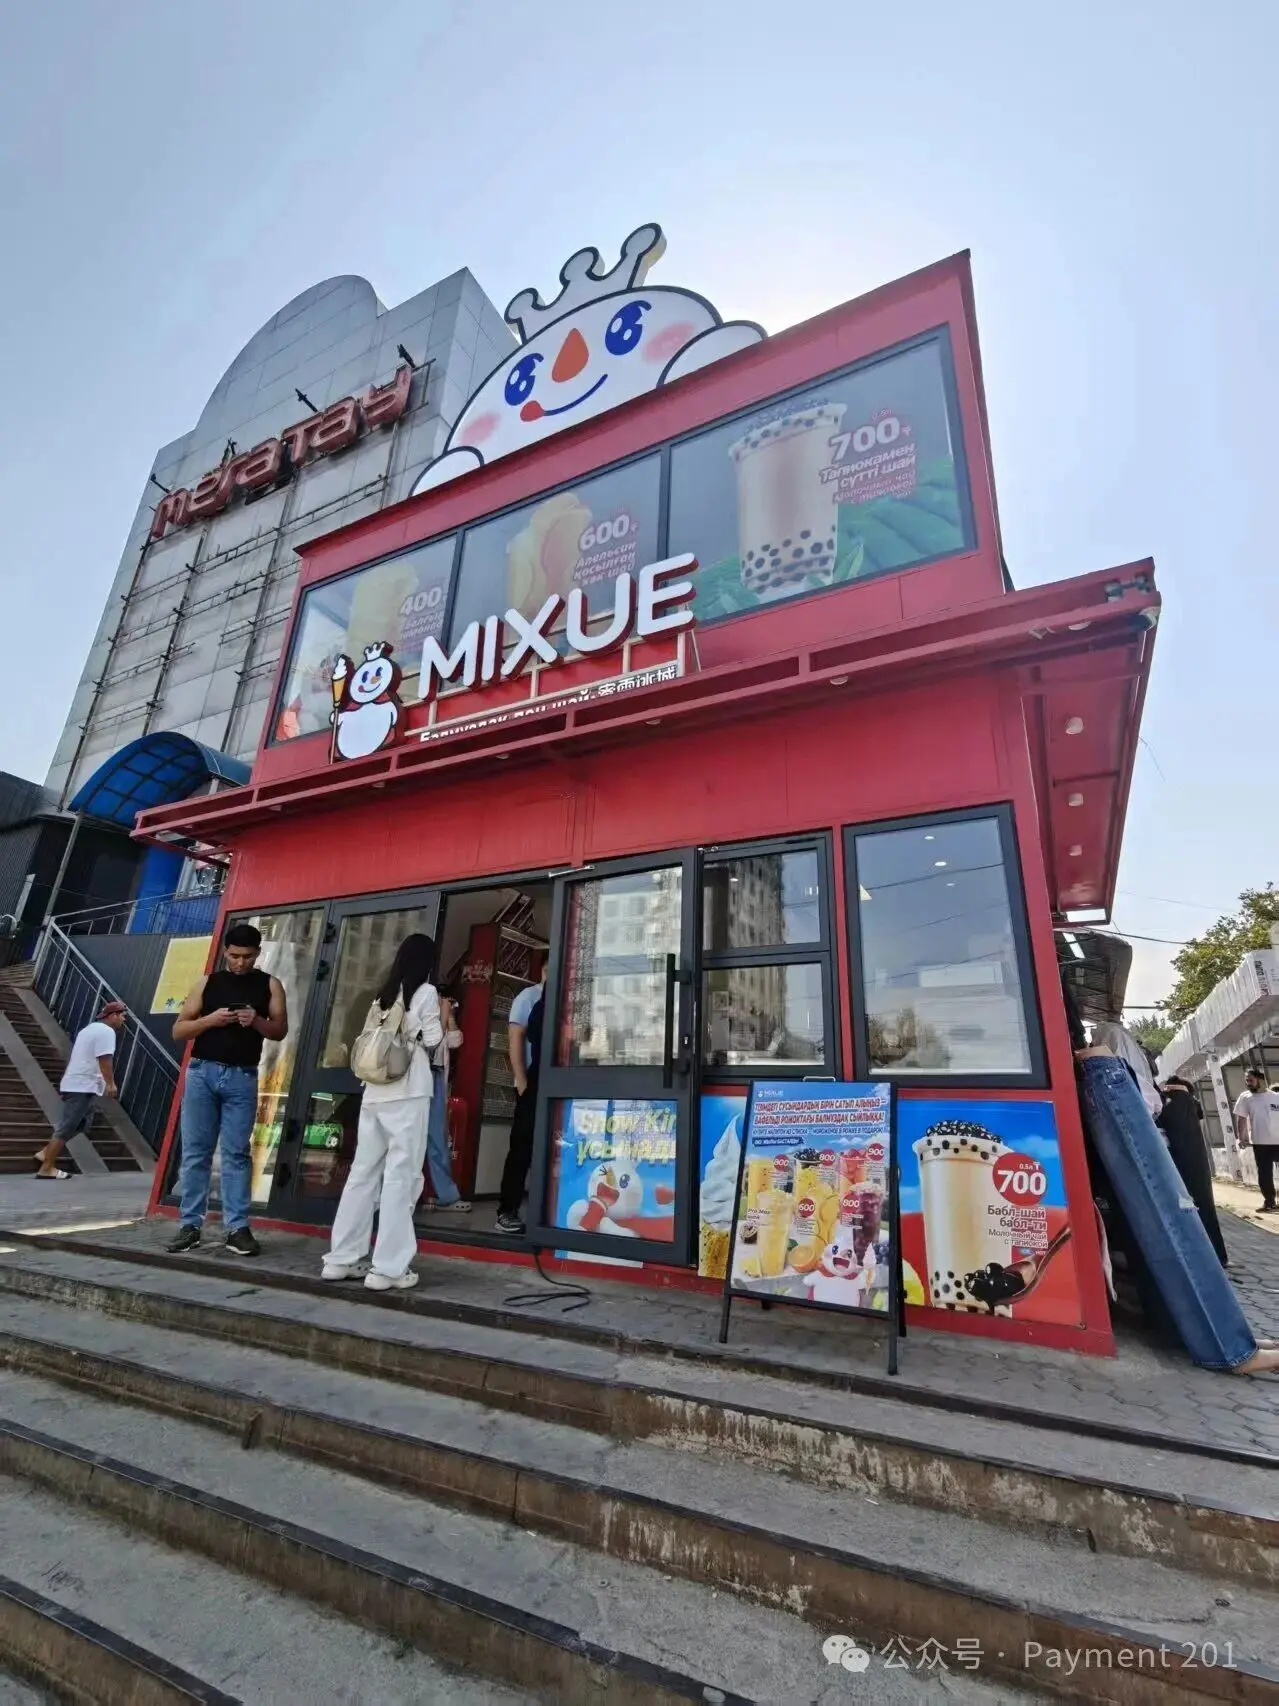
Another very intuitive feeling is that there are more Chinese elements than I originally imagined. Of course, there might be a bit of survivor bias. Starting from the airport in Urumqi, to landing in Almaty, and then to the meeting the next day, I encountered quite a few Chinese people along the way. Some are involved in infrastructure, some in minerals, energy, and resource trade, and others in cross-border logistics and business.
The flow of goods, funds, and personnel between China and Central Asia is actually much deeper than many domestic payment practitioners imagine.
1. From Freedom Bank to Central Asia FinTech Summit
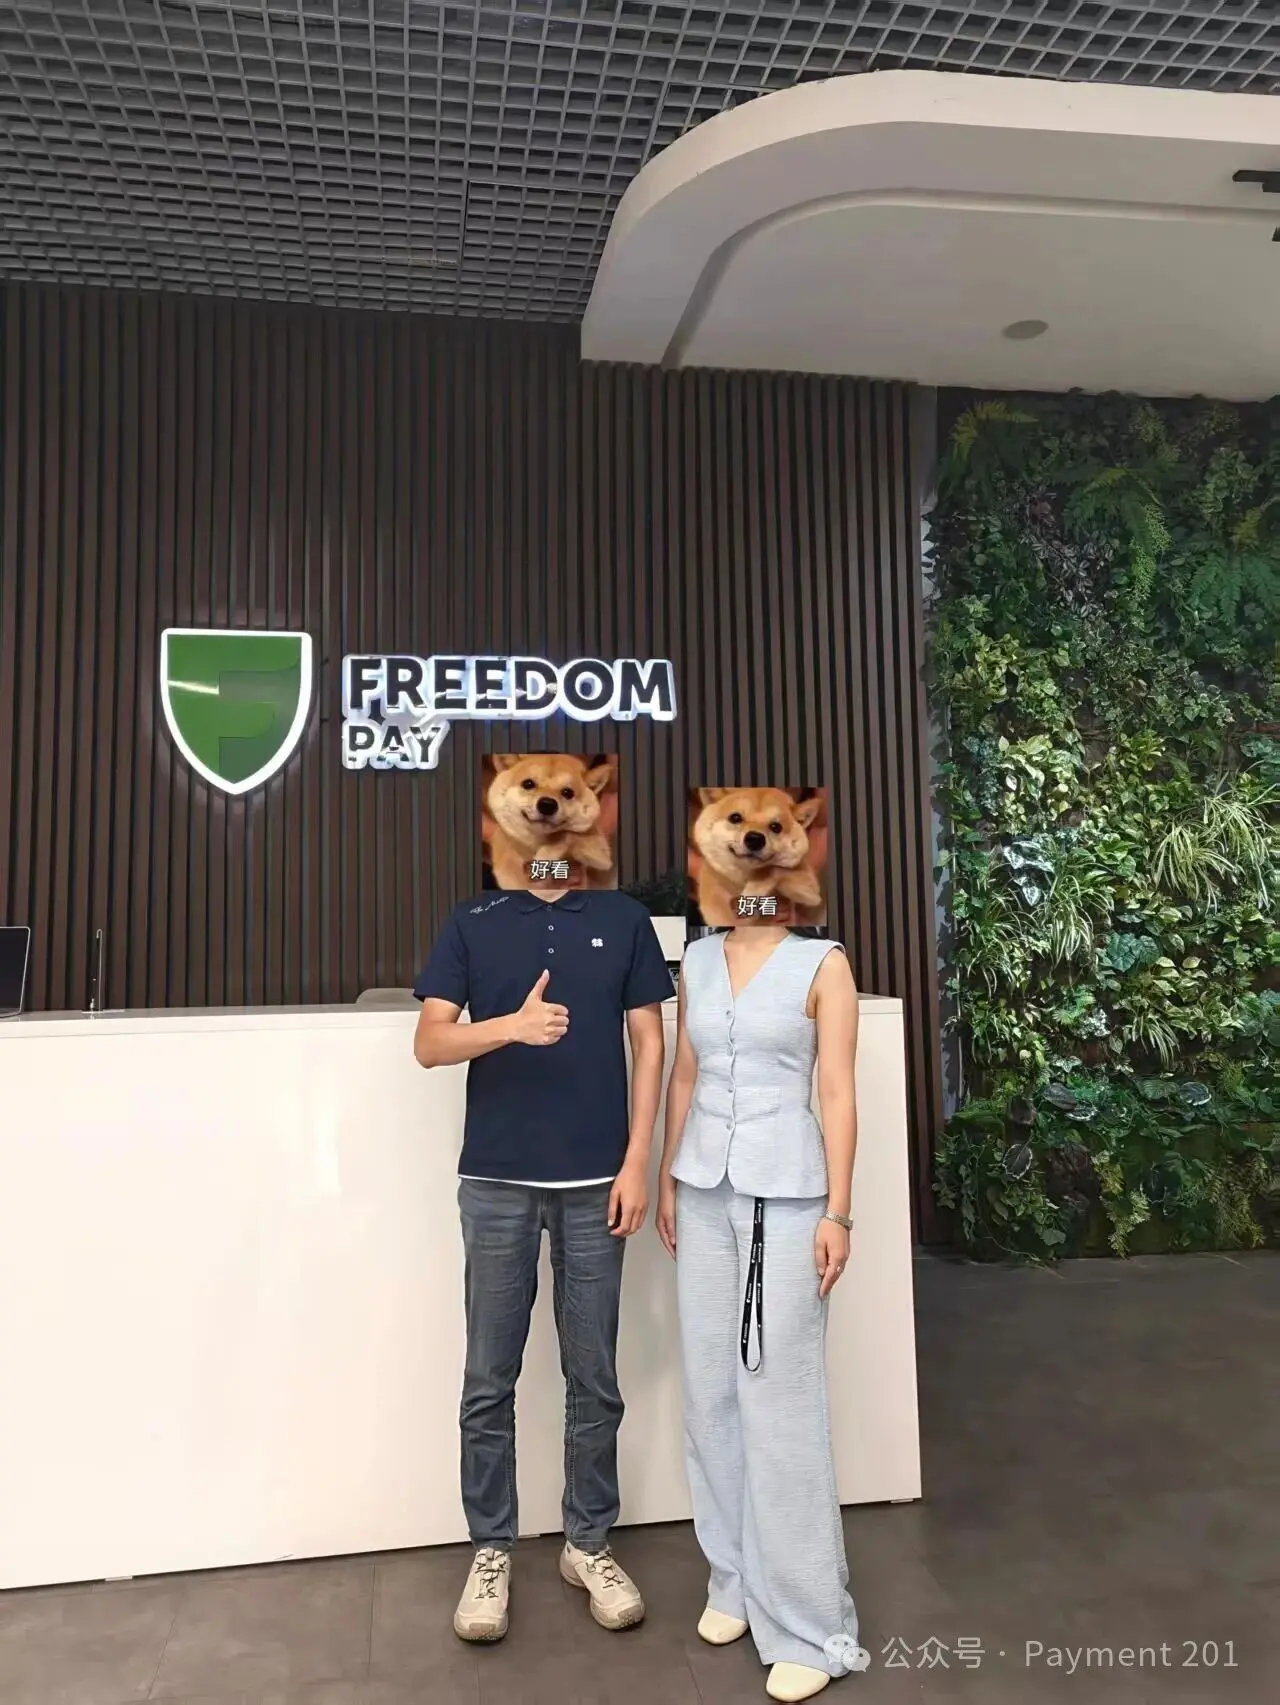
Early the next morning, I went to Freedom Bank.
The office has a very typical internet banking style, reminiscent of WeBank. The Freedom Pay team works in Kaisar Plaza, and since the big boss likes Harry Potter, the office is decorated according to Harry Potter themes.
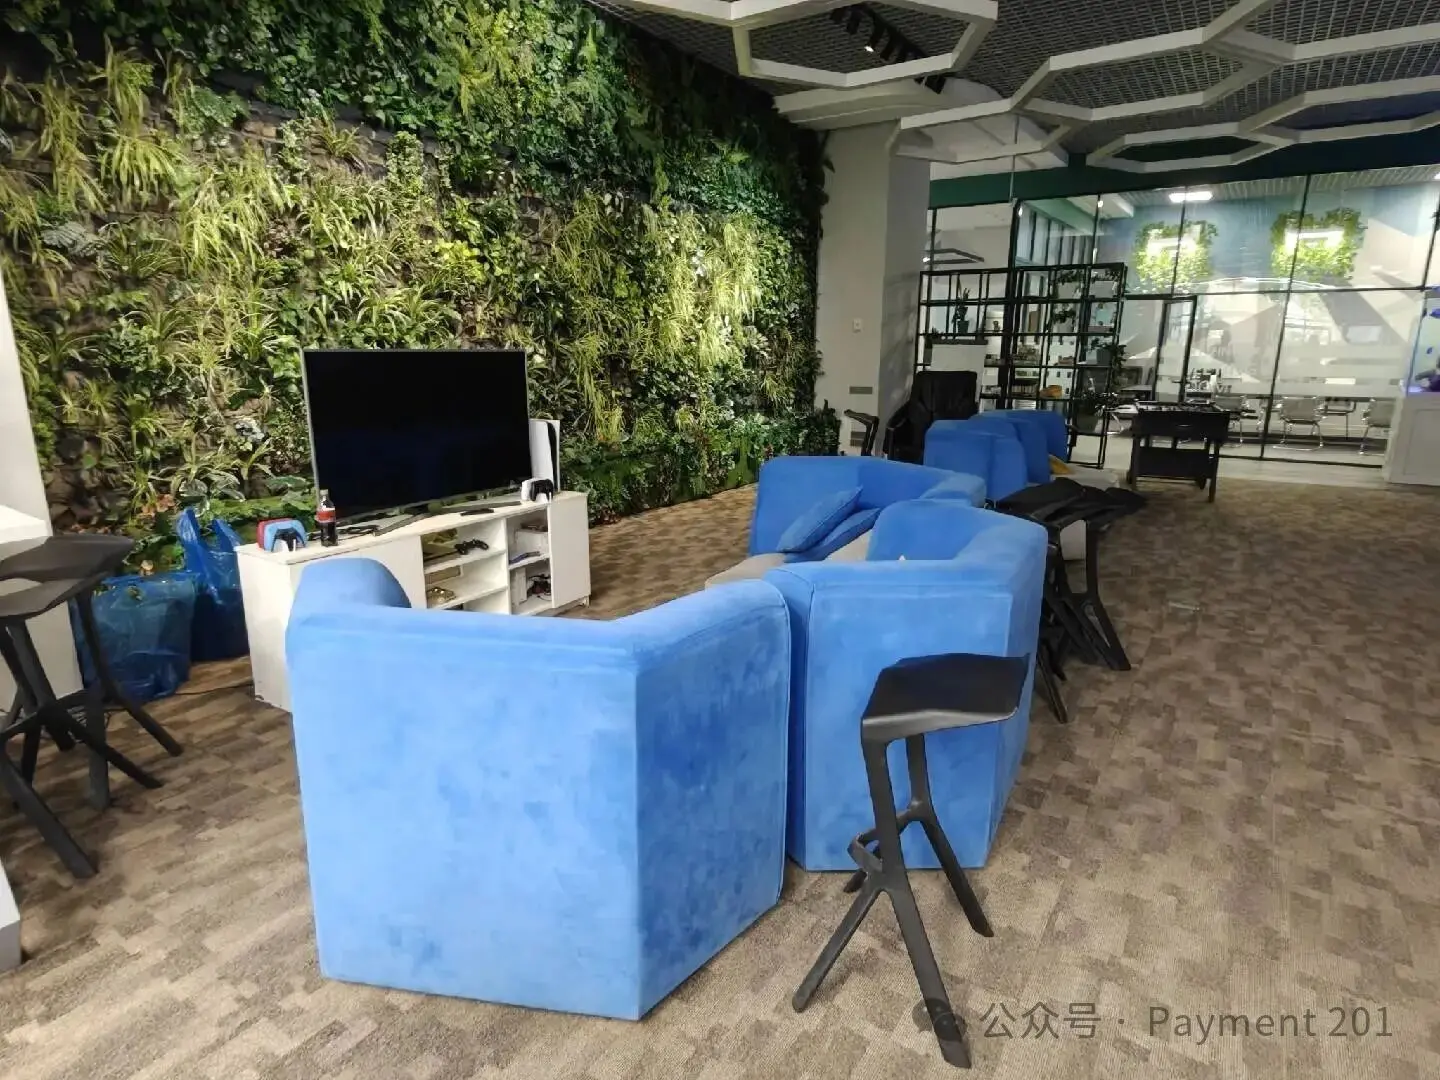
Everyone quickly caught up on previous business collaborations, discussed recent industry changes, and the potential future directions for banking and payments in Kazakhstan.
One more intuitive feeling from this visit to Freedom is that local banks no longer view mobile apps as merely "electronic banking channels," which were just for checking balances, transferring money, and paying credit cards. Instead, they are competing for the real Consumer Front-end.
Kaspi is the most successful player in this model, but Freedom, along with other local banks, is also moving towards Banking + Payments + Lifestyle/Commerce. In other words, local banks are competing for more than just deposits, loans, and cards.
What everyone is competing for is: who can dominate the app that users open every day. This detail is actually very important, which I will elaborate on later.
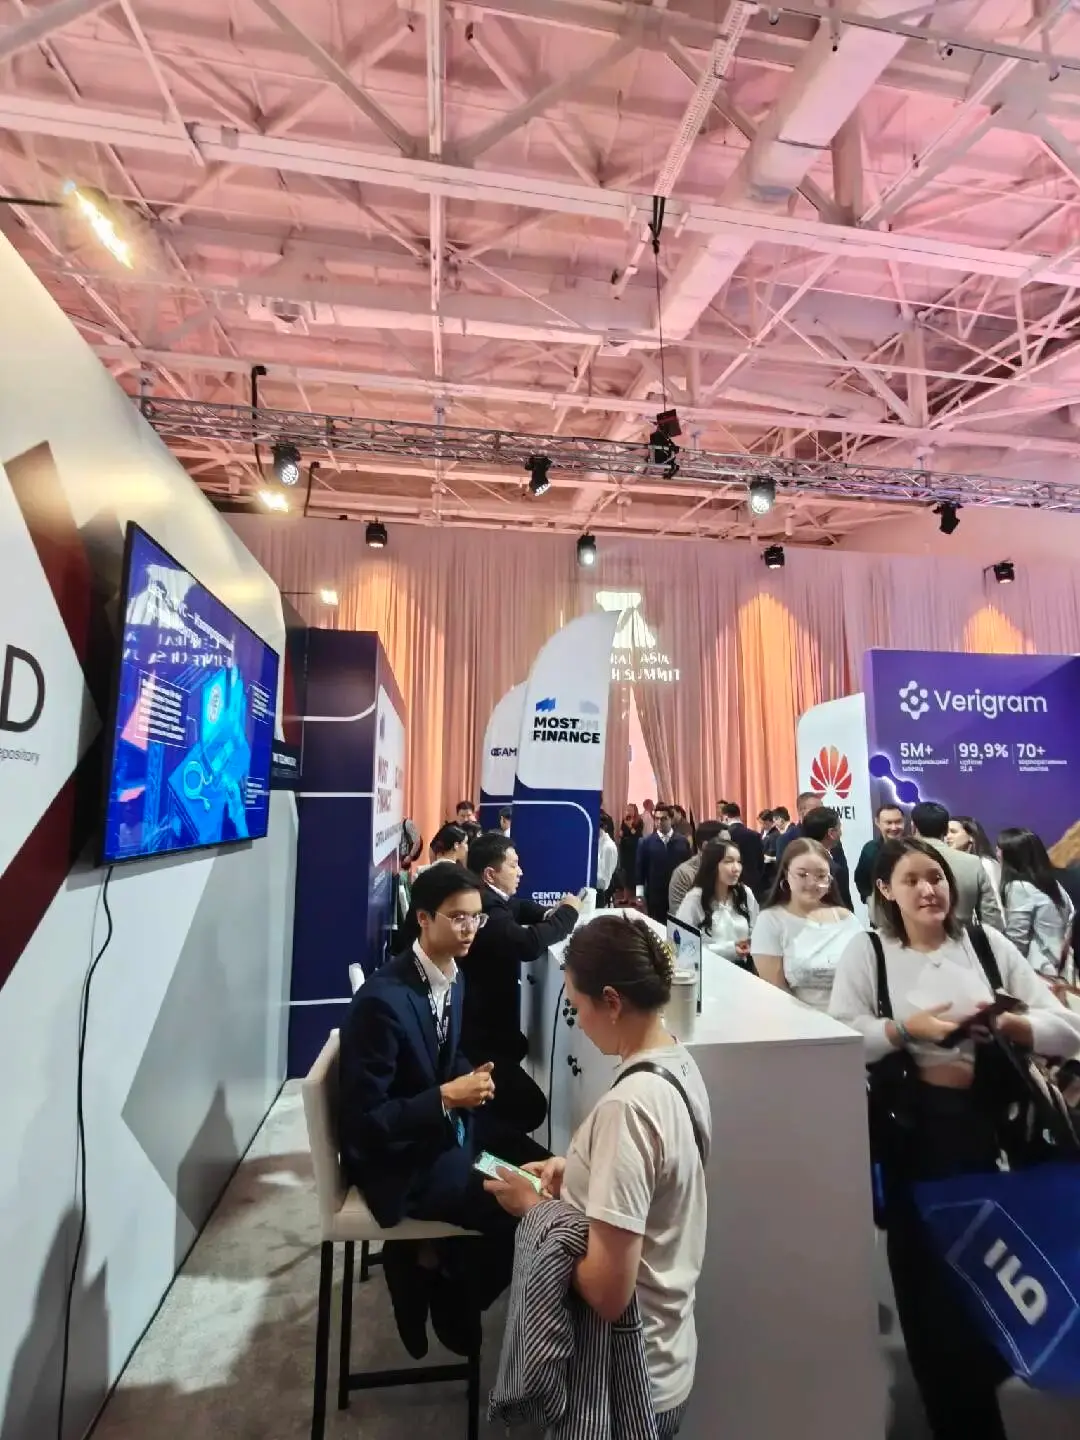
At noon, I quickly visited the Central Asia FinTech Summit. The venue was somewhat like an art gallery, with not many booths, mainly consisting of local exchanges, payment companies, and financial institutions. Visa had a fairly large booth, but when I passed by, it seemed there wasn't much business happening, with a few people sitting there playing games.
I casually chatted with a few institutions at the venue, exchanged some business cards, and indeed had some unexpected gains. I also ran into friends from UnionPay International and discussed card issuance and remittance services.
The payment industry can be quite interesting at times. Issues that take ten emails to clarify online can often be understood in about ten minutes of face-to-face conversation, and then the rest can be followed up later.
At noon, I had a meal with friends nearby and began to speculate on what could be done in the payment industry in the coming years.
### 2. The evening discussions were already about "2026 topics"
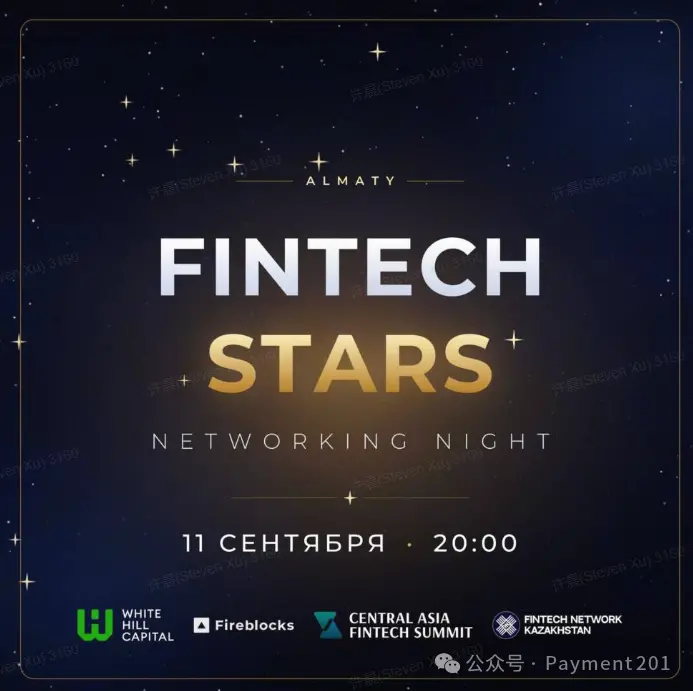
In the evening, I attended the only Fintech Network event in Almaty that day.
Fireblocks was one of the hosts, and I was introduced to Pave Bank, Tether, and several local PSPs and FinTechs from Central Asia.
The topics discussed were very much "2026." Various specific businesses and collaborations revolved around: Stablecoin, Cross-border Settlement, Banking Infrastructure, On/Off-ramp, and what will emerge in the Central Asian market next.
After chatting, I looked at the time and realized it was already ten o'clock at night. When I opened Telegram, I found that many friends from Central Asia communities I had contacted before were arranging to meet offline. It was indeed overwhelming.
Although the event was called the Central Asia FinTech Summit, there were actually not just the Central Asian C5 countries present. I also met friends from the Caucasus, such as Georgia. From the perspective of the payment and financial industry, Central Asia and the Caucasus are often viewed as part of a larger region.
Over the past few days, I also took the opportunity to try the local cuisine. Horse meat, homemade bread, draft beer, and Georgian grill.
Almaty really has a strong aftertaste.
After a few days, I didn't use cash even once.
Speaking of payments.
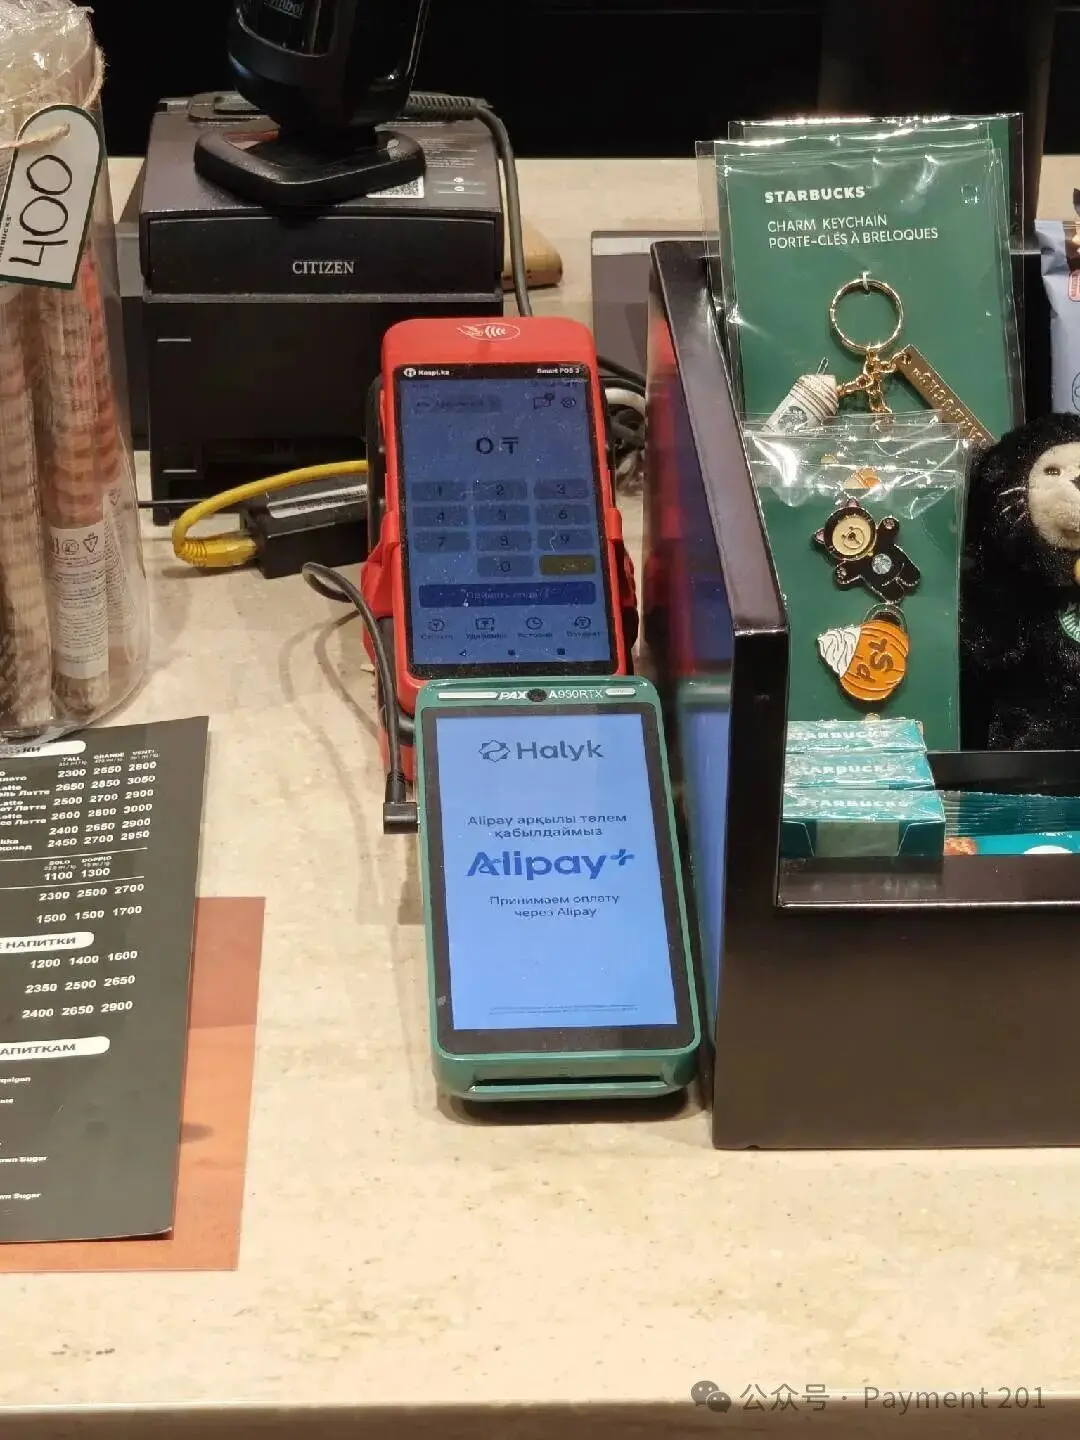
During this trip to Almaty, I had a very intuitive experience:
I did not use cash at all.
For meals, coffee, shopping malls, and various daily expenses, whenever I could use a card, I directly used my Visa Card, and in some scenarios, I also used Alipay+. The entire payment experience was much smoother than I had imagined before setting out.
Before coming, I still had some stereotypes: Would the cash ratio in Almaty be relatively high? Would card acceptance be insufficient? Would there be many local wallets that are fragmented?
Upon arrival, at least in a core city like Almaty, these concerns basically did not materialize. A foreign tourist can live a cashless life relying solely on Visa + Alipay+.
In the first half of 2026, residents of Kazakhstan completed approximately 7.1 billion transactions worth 92.1 trillion tenge in non-cash transactions, averaging over 39 million transactions daily.
However, the payment world I, as a tourist, observed is not the same as the payment world local people use daily.
Tourists see: Visa / Mastercard / International Wallet.
Local consumers are more familiar with: Kaspi / Bank App / QR / P2P.
Going a layer deeper, we start to see:
Interbank Instant Payment + Unified QR.
It is from here that Kazakhstan's payment landscape becomes very interesting.
This is not a typical Wallet-led Market
Everyone is familiar with the development path of mobile payments in China over the past decade. Third-party wallets like Alipay and WeChat Pay have gradually positioned themselves between consumers and bank accounts.
BankAccount
↓
Wallet
↓
Consumer / Merchant
The bank account remains below, but the consumer front-end has been taken over by the wallet.
Kazakhstan, however, has not fully developed along this path.
A significant part of the force driving payment digitalization here comes from banks and bank-related platforms.
Banking apps are no longer just account management tools. They have directly transformed into: super apps. So if I had to label Kazakhstan's payment landscape, I would prefer to call it:
Bank-led Super App Market.
Kaspi is the most typical example here.
What Kaspi has truly changed is not just the payment method.
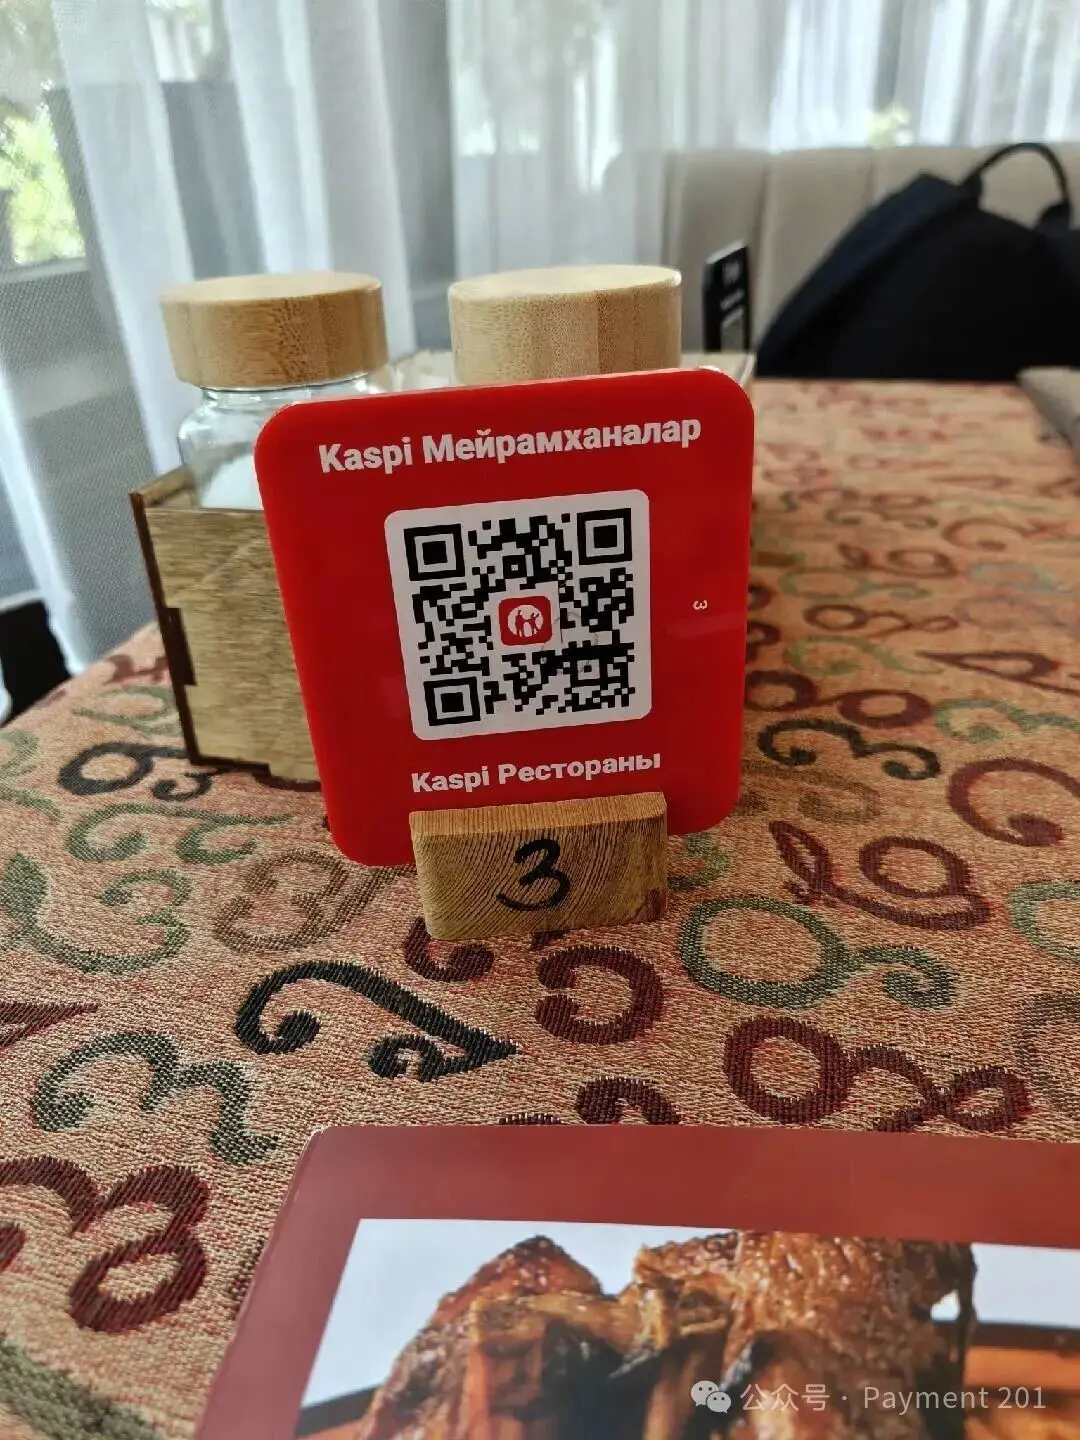
Many people who first learn about Kaspi will directly understand it as:
"Kazakhstan's Alipay."
This is convenient for understanding, but it somewhat underestimates Kaspi.
Kaspi is not simply a wallet.
On the consumer side, it offers Payment, P2P, QR, Bill Payment, Marketplace, Travel, Installment;
On the merchant side, it provides Kaspi Pay, Acquiring, QR, B2B Payment, Merchant Services.
Payment, Banking, Commerce, and Credit are all integrated into one ecosystem.
But if we only list these products, it still doesn't explain why Kaspi is strong.
What really matters is the Flywheel behind it:
Consumer
↓
Payment
↓
Merchant
↓
Marketplace
↓
Credit / Installment
↓
More GMV
↓
Payment
Consumers come in because of the convenience of payment. Merchants also need to come in because consumers are all here. The more merchants there are, the stronger the Acceptance Network becomes. The marketplace brings more transactions to merchants. Installment and Consumer Finance further drive consumption.
In the end, these transactions flow back into Payment.
So Kaspi's true moat has never been QR.
Rather, it is the Network Effect formed by: Consumer + Merchant + Payment + Commerce + Credit.
By 2025, Kaspi Payments Active Consumers will reach 14.6 million, with annual Payments TPV reaching 44.2 trillion tenge, and Payment Transactions approximately 6.72 billion; QR and Card Payment together account for 69% of Payments TPV.
In a country with only 20.6 million people, this density is quite remarkable.
But I think the truly significant meaning of Kaspi is not even these numbers.
- The relationship between traditional banks and users might be: salary comes in, save money, take loans, occasionally open the app.
- Kaspi transforms this relationship into: shopping, dining, transferring money, paying bills, installments, shopping…
Happening every day.
Payment becomes the most important high-frequency entry point in this relationship.
So in a sense, Kaspi is no longer just a Payment App.
It is very close to a:
Private Payment Infrastructure.
An interesting Card Market: Visa, Mastercard, MIR are all present
Another interesting point is that Kazakhstan is not simply a Visa / Mastercard Market.
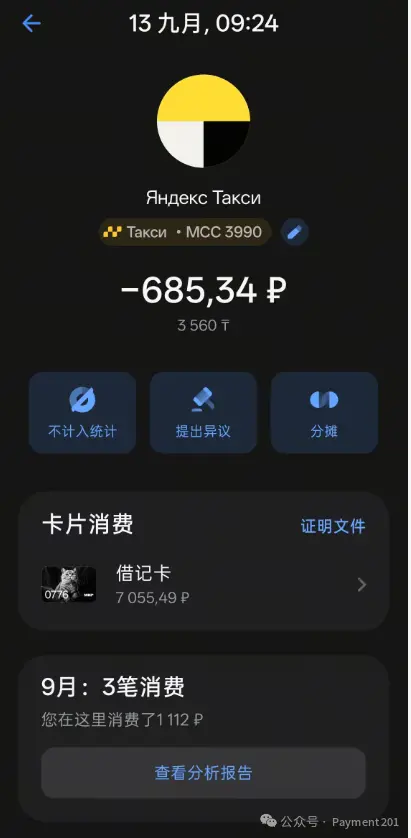
In some scenarios, MIR Card can also be accepted.
Of course, this does not mean that MIR has fully covered Kazakhstan; MIR Acceptance clearly still depends on specific Acquirers and POS Networks. Some banks and terminal networks still support MIR, while others have suspended it.
But it is precisely this detail that makes Kazakhstan Payment more interesting.
In the same market, you might simultaneously see: Visa, Mastercard, UnionPay, MIR. On top of that: Kaspi QR / Bank QR / Unified QR.
From the perspective of Payment Rail, Kazakhstan actually resembles a crossroads of payment networks.
To the west, there is the Global Card Network of Visa / Mastercard.
To the north, it retains some connection with the Russian and CIS Payment Ecosystem.
To the east, Chinese tourists and merchants can see payment methods like UnionPay, Alipay+.
And the strongest local Consumer Payment Interface is Kaspi and various Bank Apps.
So Kazakhstan Payment is hard to simply categorize as: "Card Market" or: "QR Market." It is more like a: Multi-rail Payment Market.
Payment Rails from different countries, different eras, and different technological paths coexist here.
QR is strong, but it does not mean "QR has eliminated bank cards"
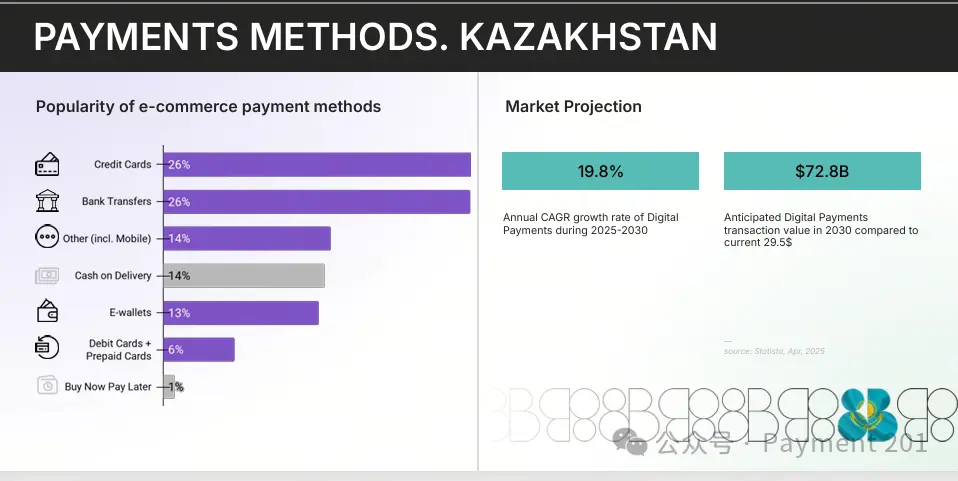
Because of this, I believe we cannot describe Kazakhstan with the phrase: "QR replaces Card."
During my time there, I mostly used Visa, while local consumers extensively used QR, and users from Russia might still use MIR in certain Acceptance Networks.
These things can completely coexist.
Because when it comes to Payment, we need to distinguish between two things: Payment Interface and Payment Rail.
When consumers open a Bank App to scan a QR code, that is one Interface. When I tap my Visa Card, that is also an Interface.
MIR Card completes a transaction at the POS that supports it, which is backed by another set of Scheme and Processing.
So what is really happening is not: one Rail completely eliminates another Rail.
Rather, the front-end Payment Experience is becoming increasingly Mobile-first, while the underlying Payment Rail is becoming more layered.
Visa / Mastercard will continue to exist in the long term for Cross-border, Tourist Payment, E-commerce, and International Merchant Acceptance.
MIR reflects the existing connection between Kazakhstan and the Russian payment ecosystem. Kaspi and Local QR address local high-frequency Consumer Payment. Unified QR continues to move towards Interoperability.
Different Rails solve different problems.
The more successful Kaspi becomes, the more apparent the next problem becomes
From the Consumer perspective, Kaspi's Closed Loop has almost no issues. Open the app, scan, pay, done.
The problem arises in the overall Market Structure.
Kaspi has its own Consumers, its own Merchants, its own QR, its own Accounts, and its own Acquiring Network.
Other banks are also developing their own Apps, their own QR, and their own Merchant Networks. This is reasonable for any bank.
Because:
Closed Loop = Moat.
An institution can control UX, Risk, Pricing, Merchant Experience, and continuously enhance its Network Density through Cashback, Credit, Installment, and Commerce.
However, once several sufficiently large Closed Loops exist simultaneously, from the perspective of the entire payment market, it turns into another term:
Fragmentation.
Why should consumers care which bank the merchant belongs to? Why should merchants use different QRs for consumers from different banks? Why does each bank need to repeatedly build its own Acceptance Network?
Therefore, I believe that Kazakhstan's previous stage addressed: How to go Cashless? Now it is starting to answer the next question: How to become Interoperable?
Kaspi addresses Adoption, Unified QR begins to address Market Structure
So the most noteworthy change in Kazakhstan Payment by 2026 is not actually Kaspi.
But rather:
Unified QR.
In July 2026, Kazakhstan will officially launch the Interbank Mobile Payment System nationwide. The core consists of two things: Interbank Transfer by Phone Number and: Interbank QR Payment.
At launch, all banks providing Retail Banking Services to individual customers through Mobile Apps will be connected.
Consumers can transfer money in real-time from their bank's app to users of another bank; they can also scan the merchant's unified QR to complete cross-bank payments, no longer requiring the buyer and seller to be at the same bank.
The system supports:
24/7 Real-time.
Previously, it might have been:
Bank A Consumer
↓
Bank A App
↓
Bank A QR
↓
Bank A Merchant
Now it is gradually becoming:
Bank A Consumer
↓
Bank A Mobile App
↓
Interbank Payment Rail
↓
Bank B Merchant
For ordinary consumers, on the surface, only one thing has happened:
QR codes are interoperable.
But what those in Payment see is not just QR.
The real change is: Addressing, Routing, Clearing, Acceptance. Starting from Private Network to Interoperable Rail.
The system is operated by the National Payment Corporation under the Central Bank of Kazakhstan. One month after its launch, this Interbank Mobile Payment System has processed over 8 million transactions worth 210 billion tenge.
So I think it can be summarized in one sentence:
Kaspi addresses Adoption, Unified QR starts to address Market Structure.
Kaspi proves how quickly a Closed Loop can pull Consumers and Merchants into Mobile Payment.
Unified QR is solving another problem:
The market cannot always be divided by individual Private Networks.
Why is Kaspi already so strong, yet the country still wants to implement Unified QR?
This question is actually the main point I want to convey throughout the article. From a UX perspective, Kaspi is already very user-friendly. Consumers do not complain daily, "I need a national unified QR code." Merchants also have mature Acceptance.
So why continue to build the Interbank Rail?
Because Payment Infrastructure never only solves UX.
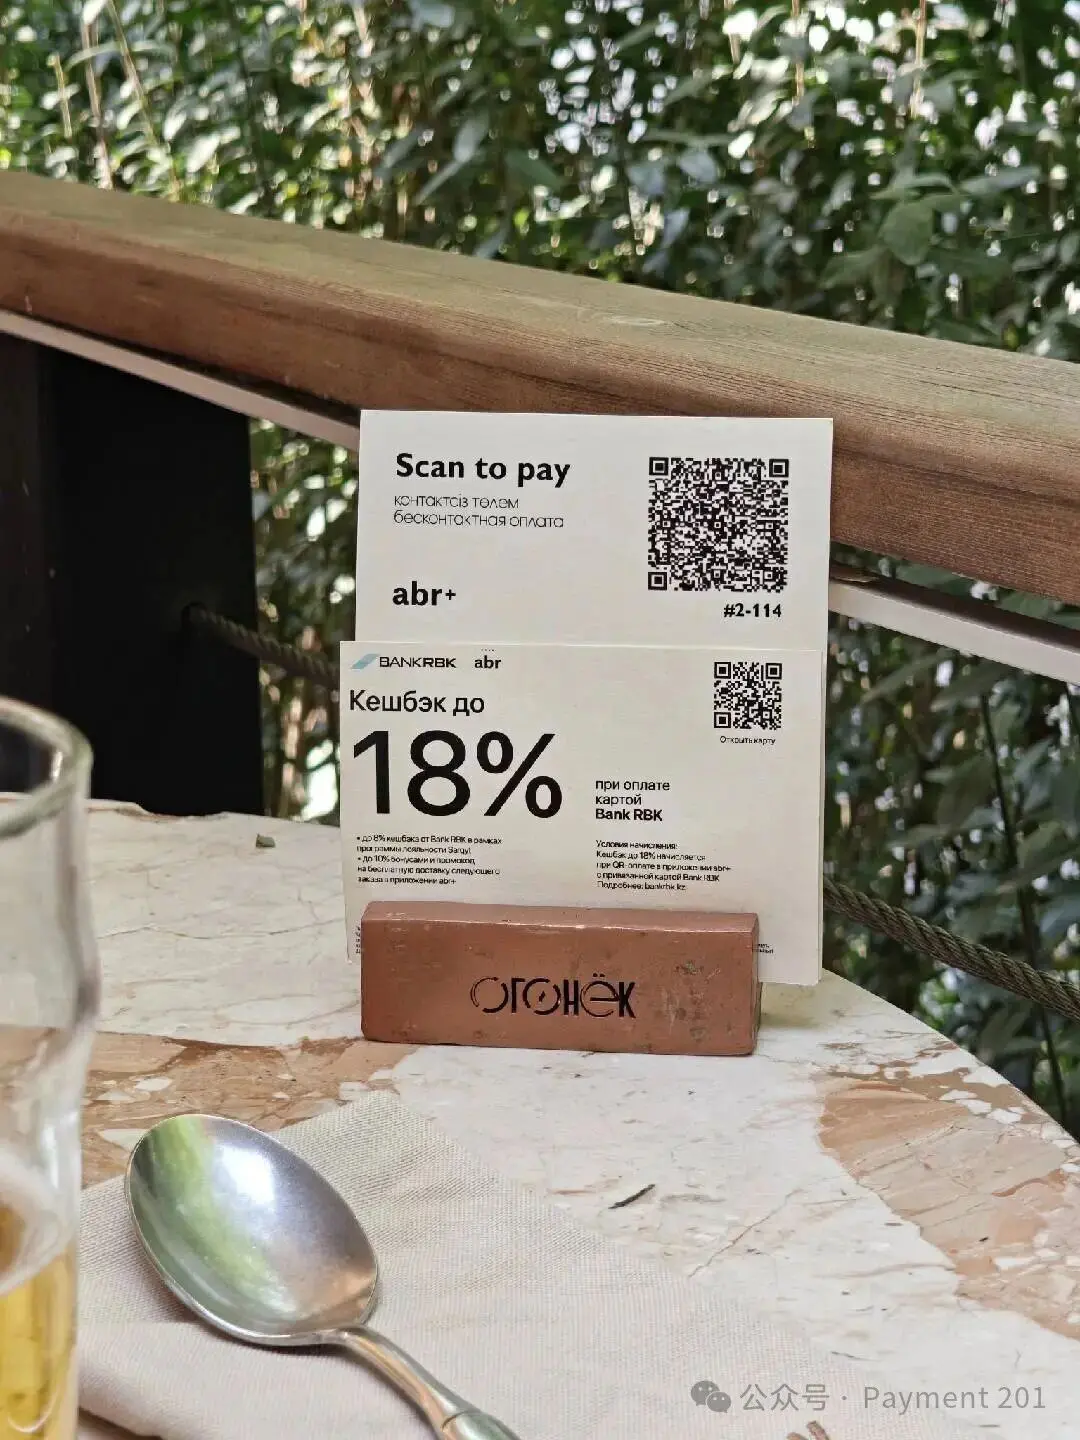
The first issue is: Competition.
When a platform simultaneously has Consumers, Merchants, Payment, Commerce, and Credit, a new entrant is not just facing a payment product.
But an entire Network. Creating a better QR code is meaningless. Because people are not with you. Merchants are not with you either.
In the payment industry, this is often the case: Technology is easy to replicate, Distribution is hard to replicate. Unified QR effectively decouples the Acceptance Network from a specific Bank's Consumer Base. Banks can compete less on "who has more QR Merchants" and compete more on: Product, UX, Pricing, Credit, Risk, Data, Service.
The second issue is:
Acceptance Density.
A truly mature Payment Network ultimately hopes to achieve:
Consumer Bank ≠ Merchant Bank, and it does not affect payment.
Visa, Mastercard, and UnionPay have essentially been solving this type of problem for decades.
Today, more and more countries are implementing Instant Payment + QR, just redoing it in the A2A world.
This is also the process of moving from: Private Network to: Public Rail.
Further down, there is a complete national-level Financial Stack
Unified QR is not an isolated project.
The Central Bank of Kazakhstan is currently advancing Interbank Mobile Payment, Unified QR, Open Banking, Digital Tenge, etc., within a larger National Digital Financial Infrastructure framework.
If we break these down: QR, Instant Payment, Open Banking, Digital Identity, Anti-Fraud, CBDC, each is a hot topic in the FinTech circle in recent years.
But what is truly interesting is that they may eventually be pieced together into the same Stack:
Identity
↓
Bank Account
↓
Open API
↓
Payment Rail
↓
Clearing / Settlement
↓
Digital Money
↓
Risk Infrastructure
So looking at Kazakhstan Payment today, if we only study: Why is Kaspi successful?
It is actually a bit insufficient; Kaspi is a very important answer from the previous stage, but this market has already begun to pose the next question.
I use Visa myself, but it is far from simple for a PSP to enter the local market.
This time in Almaty, my Payment Experience as a tourist was very simple. Visa, Alipay+, basically sufficed.
However: the ability for tourists to pay and for a Merchant / PSP to truly enter this market are completely different matters.
This time I also encountered many Chinese people locally. Infrastructure, minerals, energy, resource trade, logistics, cross-border business.
These Business Flows will inevitably be followed by increasingly complex Money Flows: Collection, FX, Settlement, Cross-border Payout. And what everyone is currently very concerned about: Stablecoin On/Off-ramp.
If a Global PSP enters Kazakhstan, the first reaction is often:
"Local Visa / Mastercard is very popular; isn't it enough to just connect Card Acceptance?"
But once you enter the Local Payment Stack, what needs to be handled is:
Local Entity
↓
Local Acquiring
↓
Kaspi / Local QR
↓
Unified QR
↓
KZT Collection
↓
Settlement
↓
FX
↓
Reconciliation
↓
Cross-border Payout
And many of your merchants do not have a local entity issue.
Thus, it often happens that the more mature the Local Payment Stack, the more Global PSPs need to understand Local. Global Acceptance has never equated to just completing Visa / Mastercard connections. What is called Global is essentially still pieced together from one Local Rail after another.
The opportunity for Stablecoin is not for locals to use USDT to buy coffee.
During networking in the evening, everyone talked a lot about Stablecoin.
But if placed within the entire Stack of Kazakhstan Payment, my understanding is actually quite simple: the first application of stablecoins is definitely not retail. Local Consumers can complete the purchase of a cup of coffee by simply opening Kaspi or a Bank App and scanning. Why must they first use USDT to pay? The front-end Consumer Payment is already good enough. Stablecoin does not need to solve a problem that has already been solved.
Its real value may lie in the backend: Cross-border B2B, Treasury, USD Liquidity, On/Off-ramp, Merchant Settlement. And in some corridors where traditional Correspondent Banking has poor coverage efficiency.
In other words:
Stablecoin here acts more like a Liquidity Layer and Settlement Layer, rather than a substitute for Local Consumer Payment.
The front-end Collection can continue to be: Kaspi / Bank QR / Card / KZT. What Merchants see can still be Fiat Settlement.
But in the subsequent Treasury, cross-border fund transfers, and Payout, it is entirely possible that a Fiat + Stablecoin Hybrid Settlement gradually emerges.
These two things do not conflict at all. I even think this is where the real value of Stablecoin Infrastructure will be seen in the coming years. It is not about what consumers use to pay today.
But rather: how the money flows after the Payment is completed.
The first half of Kaspi, the second half of Payment Rail
If we simplify the Evolution of Kazakhstan Payment over the past decade, I think it can be roughly divided into three stages:
Cashless
↓
Mobile-first
↓
Interoperable
Kaspi has had a significant impact on the first two stages.
It has brought together Consumers, Merchants, Payment, Commerce, and Credit through a Bank-led Super App. By relying on Closed Loop, it has maximized UX and Network Density.
But once a market is highly digitized, the next question will inevitably arise:
How do different Banks, different QR codes, and different Merchant Networks truly interconnect?
So I believe the most important variable for Kazakhstan Payment in 2026 is not the emergence of another Wallet or another PSP.
But rather:
Closed Loop → Interoperability.
The first half is the story of the Super App.
The second half begins to transform into the story of the Payment Rail.
Finally
Returning to this time in Almaty.
After a few days, I haven't used any cash at all. For a tourist, the payment experience has become very simple.
But what's really interesting is that what tourists see is just the top layer of the entire Payment Stack.
Going down one layer, we have: Kaspi / Bank App / QR / P2P.
Looking at the Card Rail, we see: Visa / Mastercard / UnionPay / some MIR Acceptance.
Going down another layer, we find: Interbank Instant Payment / Unified QR.
Looking at cross-border capital flows, we start to see: Stablecoin Liquidity / Settlement.
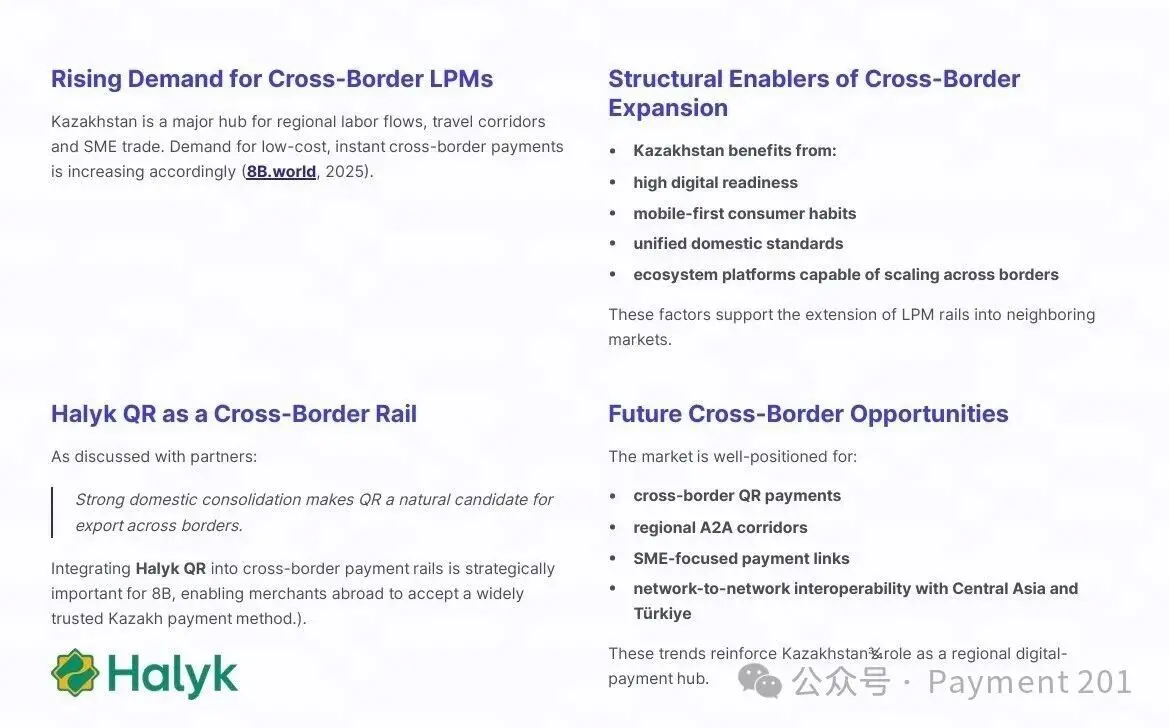
Image from 8b.world
Card, Super App, A2A, National Rail, Stablecoin. Several sets of Payment Infrastructure from completely different regions and stages are stacking together in a market with only over 20 million people.
So after returning this time, my biggest change in understanding about Kazakhstan is not:
"The payment here is more developed than I imagined."
But rather:
It has already started to change the topic.
The past question was:
How to move a market from Cash to Digital?
Today's question is increasingly becoming:
Once Payment is sufficiently Digital, how to truly achieve Interoperability?
Kaspi has solved a large part of the previous question.
And Kazakhstan in 2026 has already begun to answer the next question.
 Risk warning
Popular articles





