








What does being removed by MSCI mean for Strategy?
 Core Viewpoint

 A one-time sell-off may have limited impact as Strategy suggests, but for a company increasingly reliant on capital market infusions, the cost of losing a portion of passive buying may only become apparent during the next round of financing.
Author: Zhou, ChainCatcher
After the close of U.S. stocks on October 15, Eastern Time, the index provider MSCI announced the formal adoption of the non-operating company exclusion rule, which will take effect after the close on November 30.
According to the potential impact list released by MSCI along with the announcement, the world's largest publicly traded Bitcoin holding company, Strategy, is listed as a candidate for exclusion, and the Japanese Bitcoin treasury company, Metaplanet, is also included. The final list will be announced on November 11.
On that day, Strategy's stock price closed at $151.29, up 5.62%. After the announcement, the stock price fell 1.60% in after-hours trading to $148.87, and by the early morning of October 16, Eastern Time, the decline had expanded to 2.54%.
Compared to a year ago, this reaction seems calm. In November 2025, based solely on a report from JPMorgan regarding exclusion risks, Strategy's stock price fell for several weeks. Now that the rule is officially implemented, why is there no panic in the market, and what does being excluded by MSCI actually mean?
MSCI's New Rule Takes Effect, Strategy Faces Challenges
This is the second time MSCI has taken action against such companies. On October 10, 2025, MSCI initiated a consultation proposing to exclude companies with more than 50% of their total assets in digital assets from the global investable market index and to implement temporary measures on companies in the list, freezing share counts and delaying new inclusions.
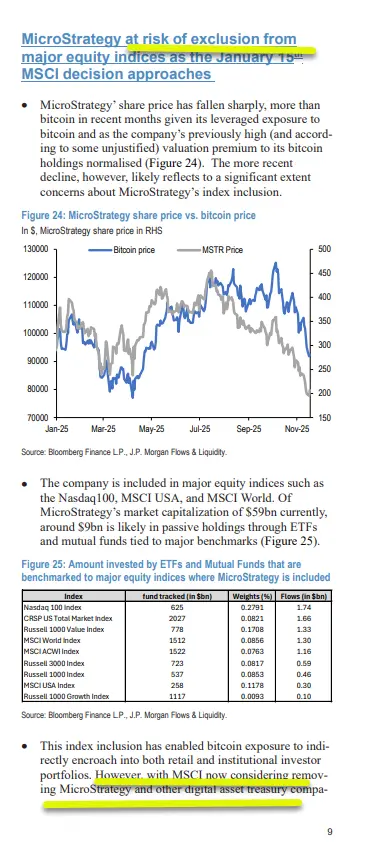
JPMorgan subsequently estimated that if Strategy were excluded, passive funds tracking the MSCI index could see outflows of $2.8 billion. Strategy's stock price continued to be under pressure, and by the end of 2025, it had fallen about 71% from its peak in November 2024.
On January 6, 2026, MSCI announced that it would not implement the proposal in the February index review, and Strategy's stock price rose about 6% in after-hours trading. However, the temporary measures were still retained, and MSCI stated that it would conduct a broader review of non-operating companies.
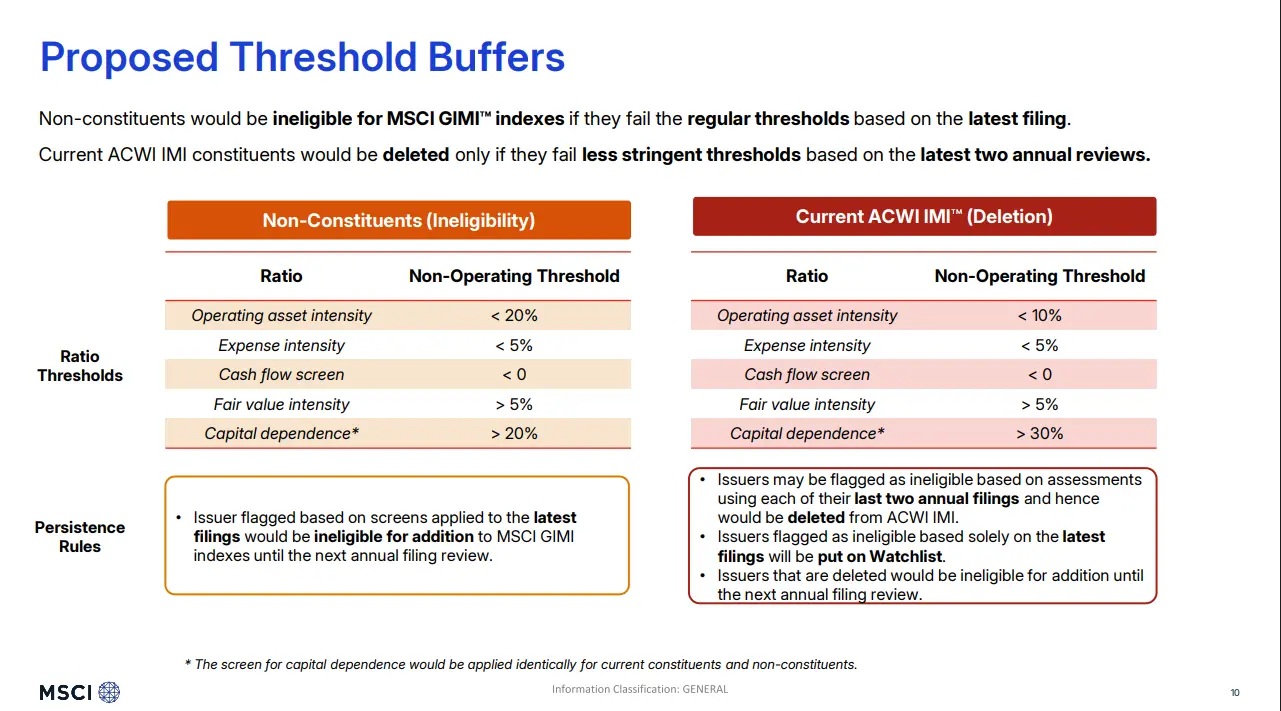
On August 3, a new round of consultation was launched. The new plan no longer mentioned digital assets throughout and changed to a two-step screening process. The first step checks whether operating assets exceed 50% of total assets; those that pass are retained directly. Those that do not pass enter the second step, where they are evaluated based on five financial ratios: operating asset intensity, expense intensity, operating cash flow, fair value intensity, and capital dependence. If four or more thresholds are met, they lose their qualification for inclusion.
To reduce index turnover, MSCI set a buffer for existing constituent stocks. According to the August consultation document, the thresholds applicable to constituent stocks are more lenient, with the standard for operating asset intensity relaxed from below 20% to below 10%, and capital dependence from above 20% to above 30%. Constituent stocks must not pass the screening in both of the last two annual financial reporting periods to be excluded; only those that fail the latest period are placed on the watch list.
MSCI explained in the consultation document that only sustained changes in business structure should trigger reclassification, and a one-time failure to meet standards would not. This announcement stated that the final plan made minor adjustments based on the August proposal, with specific thresholds included in its methodology appendix. Companies that are excluded will be removed from the entire MSCI global investable market index system and cannot be re-included before the next annual review.
With the new rules taking effect, the temporary measures for digital asset treasury companies will also end during the November index review, and such companies will be uniformly assessed according to the new method.
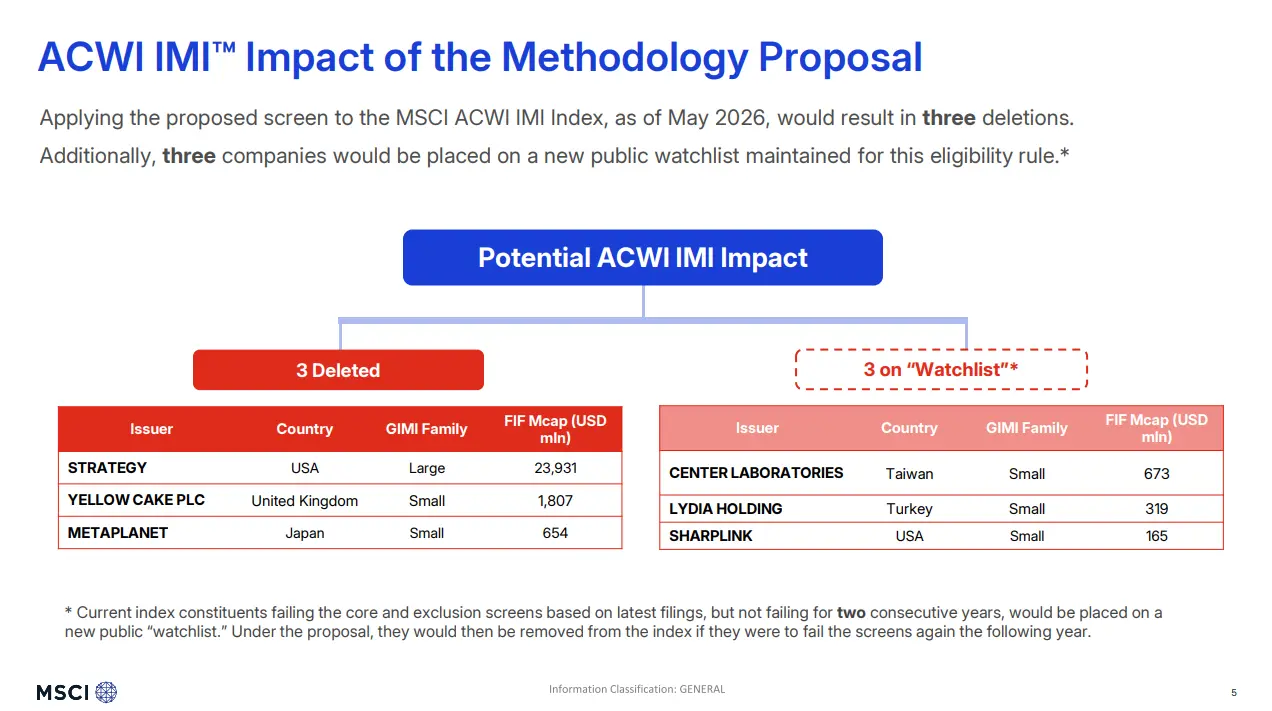
The August consultation document simulated based on May data, resulting in three companies being excluded and three entering the watch list. The list released with the announcement is based on financial data from September 30 and market capitalization from October 9, expanding to five candidates for exclusion and 17 entering the watch list. In addition to Strategy and Metaplanet, the candidates for exclusion include the UK uranium holder Yellow Cake, the Icelandic investment company Skel fjárfestingafélag, and the Solana treasury company Upexi.
The wording of the new rules maintains neutrality regarding asset types, but Strategy finds it difficult to pass, primarily due to two of the tests.
According to MSCI's definition, capital dependence is equal to cash flow from financing activities divided by total assets, and the company must have engaged in financing activities to accumulate assets in the past 12 months. According to Strategy's annual report, its cash flow from financing activities for the fiscal years 2024 and 2025 is approximately $22.13 billion and $24.84 billion, corresponding to year-end total assets of approximately $25.84 billion and $61.64 billion, with ratios of about 86% and 40%, both far exceeding the 30% threshold for constituent stocks.
The cash flow test standard is that operating cash flow is negative. Strategy's operating cash flow for the fiscal years 2024 and 2025 is approximately -$53 million and -$67.2 million, also touching the threshold in both years. According to this calculation, the two-year buffer is unlikely to provide protection for Strategy, which also explains why it directly entered the exclusion list in the May simulation rather than the watch list.
The pace of financing has not slowed this year. According to an 8-K document disclosed by Strategy in September, the company has raised approximately $20.9 billion this year through the issuance of common and preferred stock, ranking fourth in the scale of stock issuance in the U.S., behind only SpaceX, Alphabet, and Intel.
Whether the other three items can meet the threshold depends on whether Bitcoin counts as operating assets, which is the core of the dispute between the two parties. MSCI described the common characteristics of non-operating companies in the consultation document, stating that they create value by accumulating and holding non-operating assets, with their own business generating almost no cash, performance driven by market fluctuations, and relying on external capital rather than their own operations for growth.
Strategy emphasized in an open letter to MSCI in September that the company employs approximately 1,500 people globally and, after communicating with SEC staff, its Bitcoin business is disclosed as an operating segment under U.S. GAAP, with related gains and losses included in operating expenses. Strategy believes that there is no definition of operating versus non-operating in U.S. GAAP, IFRS, or any recognized legal framework, and the new proposal is merely a rebranding of the proposal withdrawn in 2025, leading to the same outcome.
A few days ago, Saylor stated that MSCI's position so far has been disappointing, imposing a biased value judgment on digital assets, and urged MSCI to reconsider. He also announced that the bear market in the crypto market over the past year has ended, and Bitcoin will return above $100,000.
The Bitcoin Policy Institute (BPI) also released a report questioning MSCI's decision-making process. The report pointed out that the metadata shows that the presentation on which MSCI's consultation was based is stored in an internal folder specifically for digital asset treasury companies.
Among the 17 companies on the latest watch list, most are digital asset treasury companies, including the Ethereum treasury company SharpLink, as well as Ton Strategy, Solana Company, DeFi Development, Sui Group, and others. However, the exclusion and watch lists also include uranium holders, Icelandic investment companies, and several investment holding companies from Canada, Sweden, and Israel.
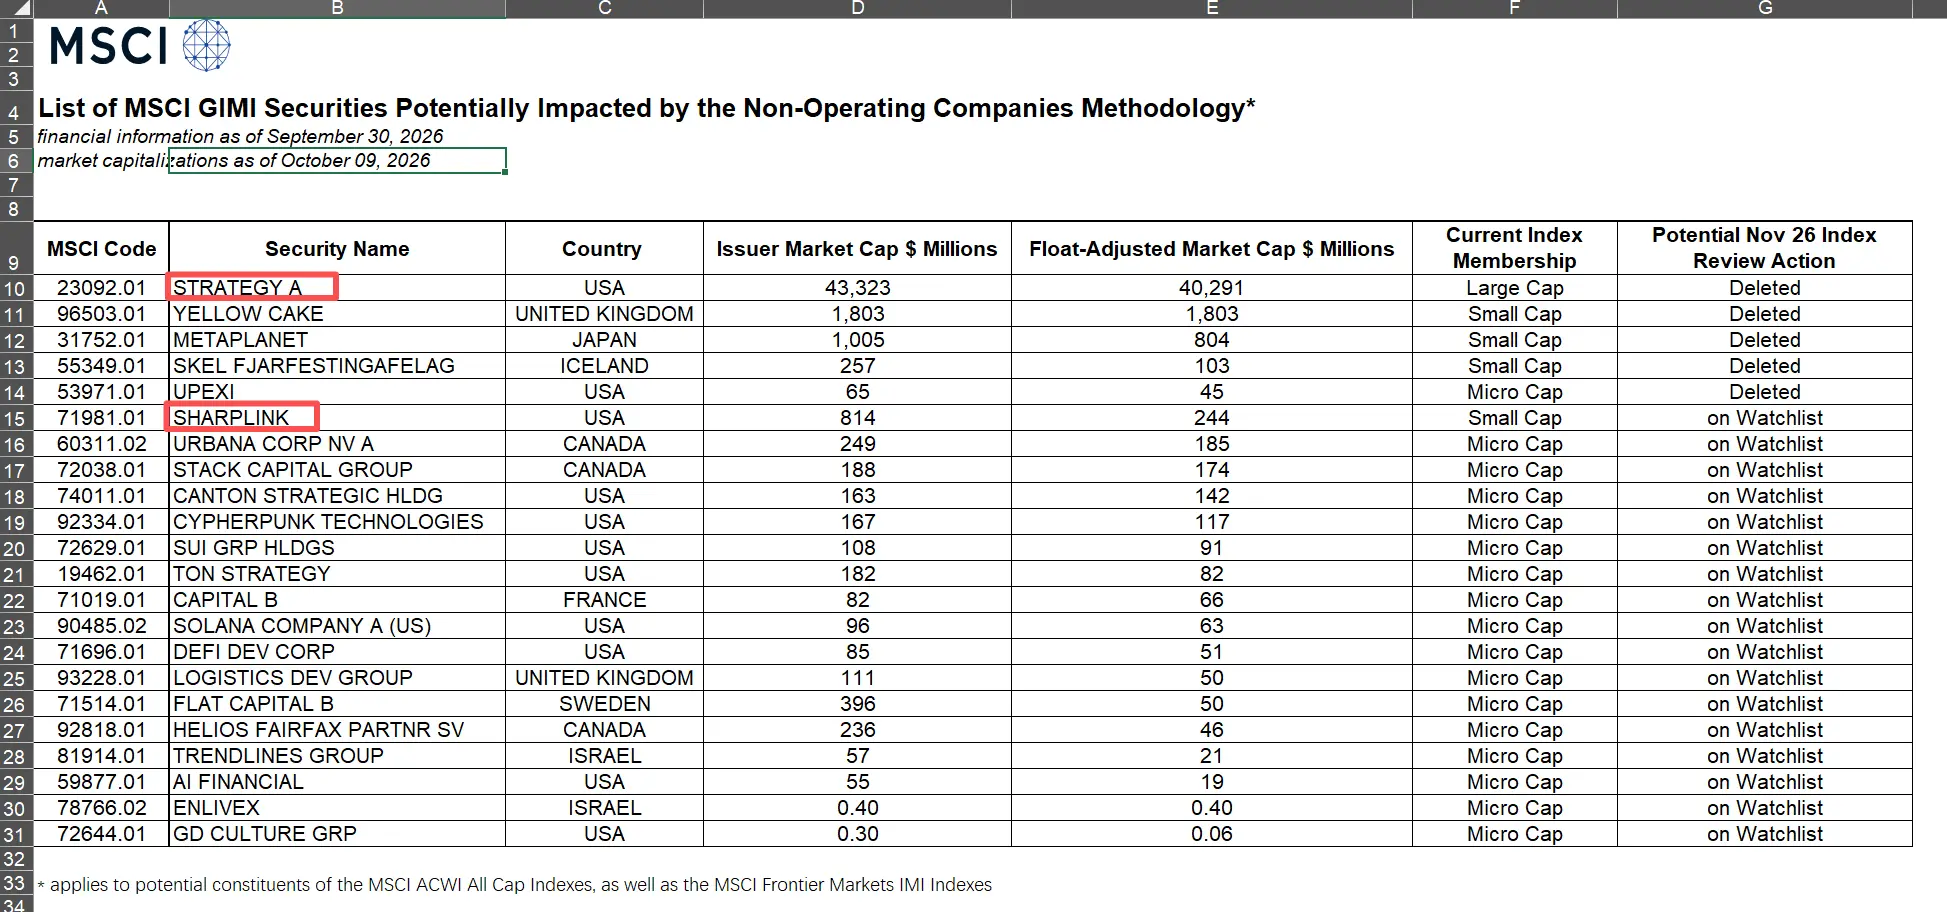
The real disparity lies in the scale. According to the list data, the total adjusted market capitalization of the 22 companies is approximately $44.4 billion, with Strategy accounting for about $40.3 billion, or about 91%. The rules treat all companies equally, but the impact falls primarily on Strategy alone.
Limited Passive Selling Pressure? The Real Pressure is on the Financing Flywheel
The most direct consequence of exclusion is passive fund selling. Last November, JPMorgan estimated that if excluded by MSCI, Strategy could face $2.8 billion in fund outflows; if other index providers follow suit, total outflows could reach $8.8 billion.
Of this, $2.8 billion comes from funds tracking the MSCI World, MSCI ACWI, and MSCI USA indices, approximately $1.3 billion, $1.16 billion, and $300 million, respectively. The $8.8 billion includes totals from the Nasdaq 100, CRSP U.S. Total Market Index, and Russell series, with the Nasdaq 100 alone accounting for about $1.74 billion, provided that multiple index providers take action simultaneously.
However, JPMorgan's estimate was based on MSCI's proposal from last year, relying on the market capitalization and index weights at that time.
Strategy's own figures are much smaller. The company stated on its official MSCI webpage that the proposal would not have a material impact on Strategy, as funds tracking the MSCI global investable market index only hold 3.1% of its basic float shares, about 13 million shares, which is less than one trading day's volume.
According to Bitcoin analyst Adrian Morris, the average daily trading volume of MSTR this year is approximately $2.91 billion, and the $2.8 billion sell-off is roughly equivalent to 0.96 trading days' volume, accounting for only 18.3% of last week's trading volume.
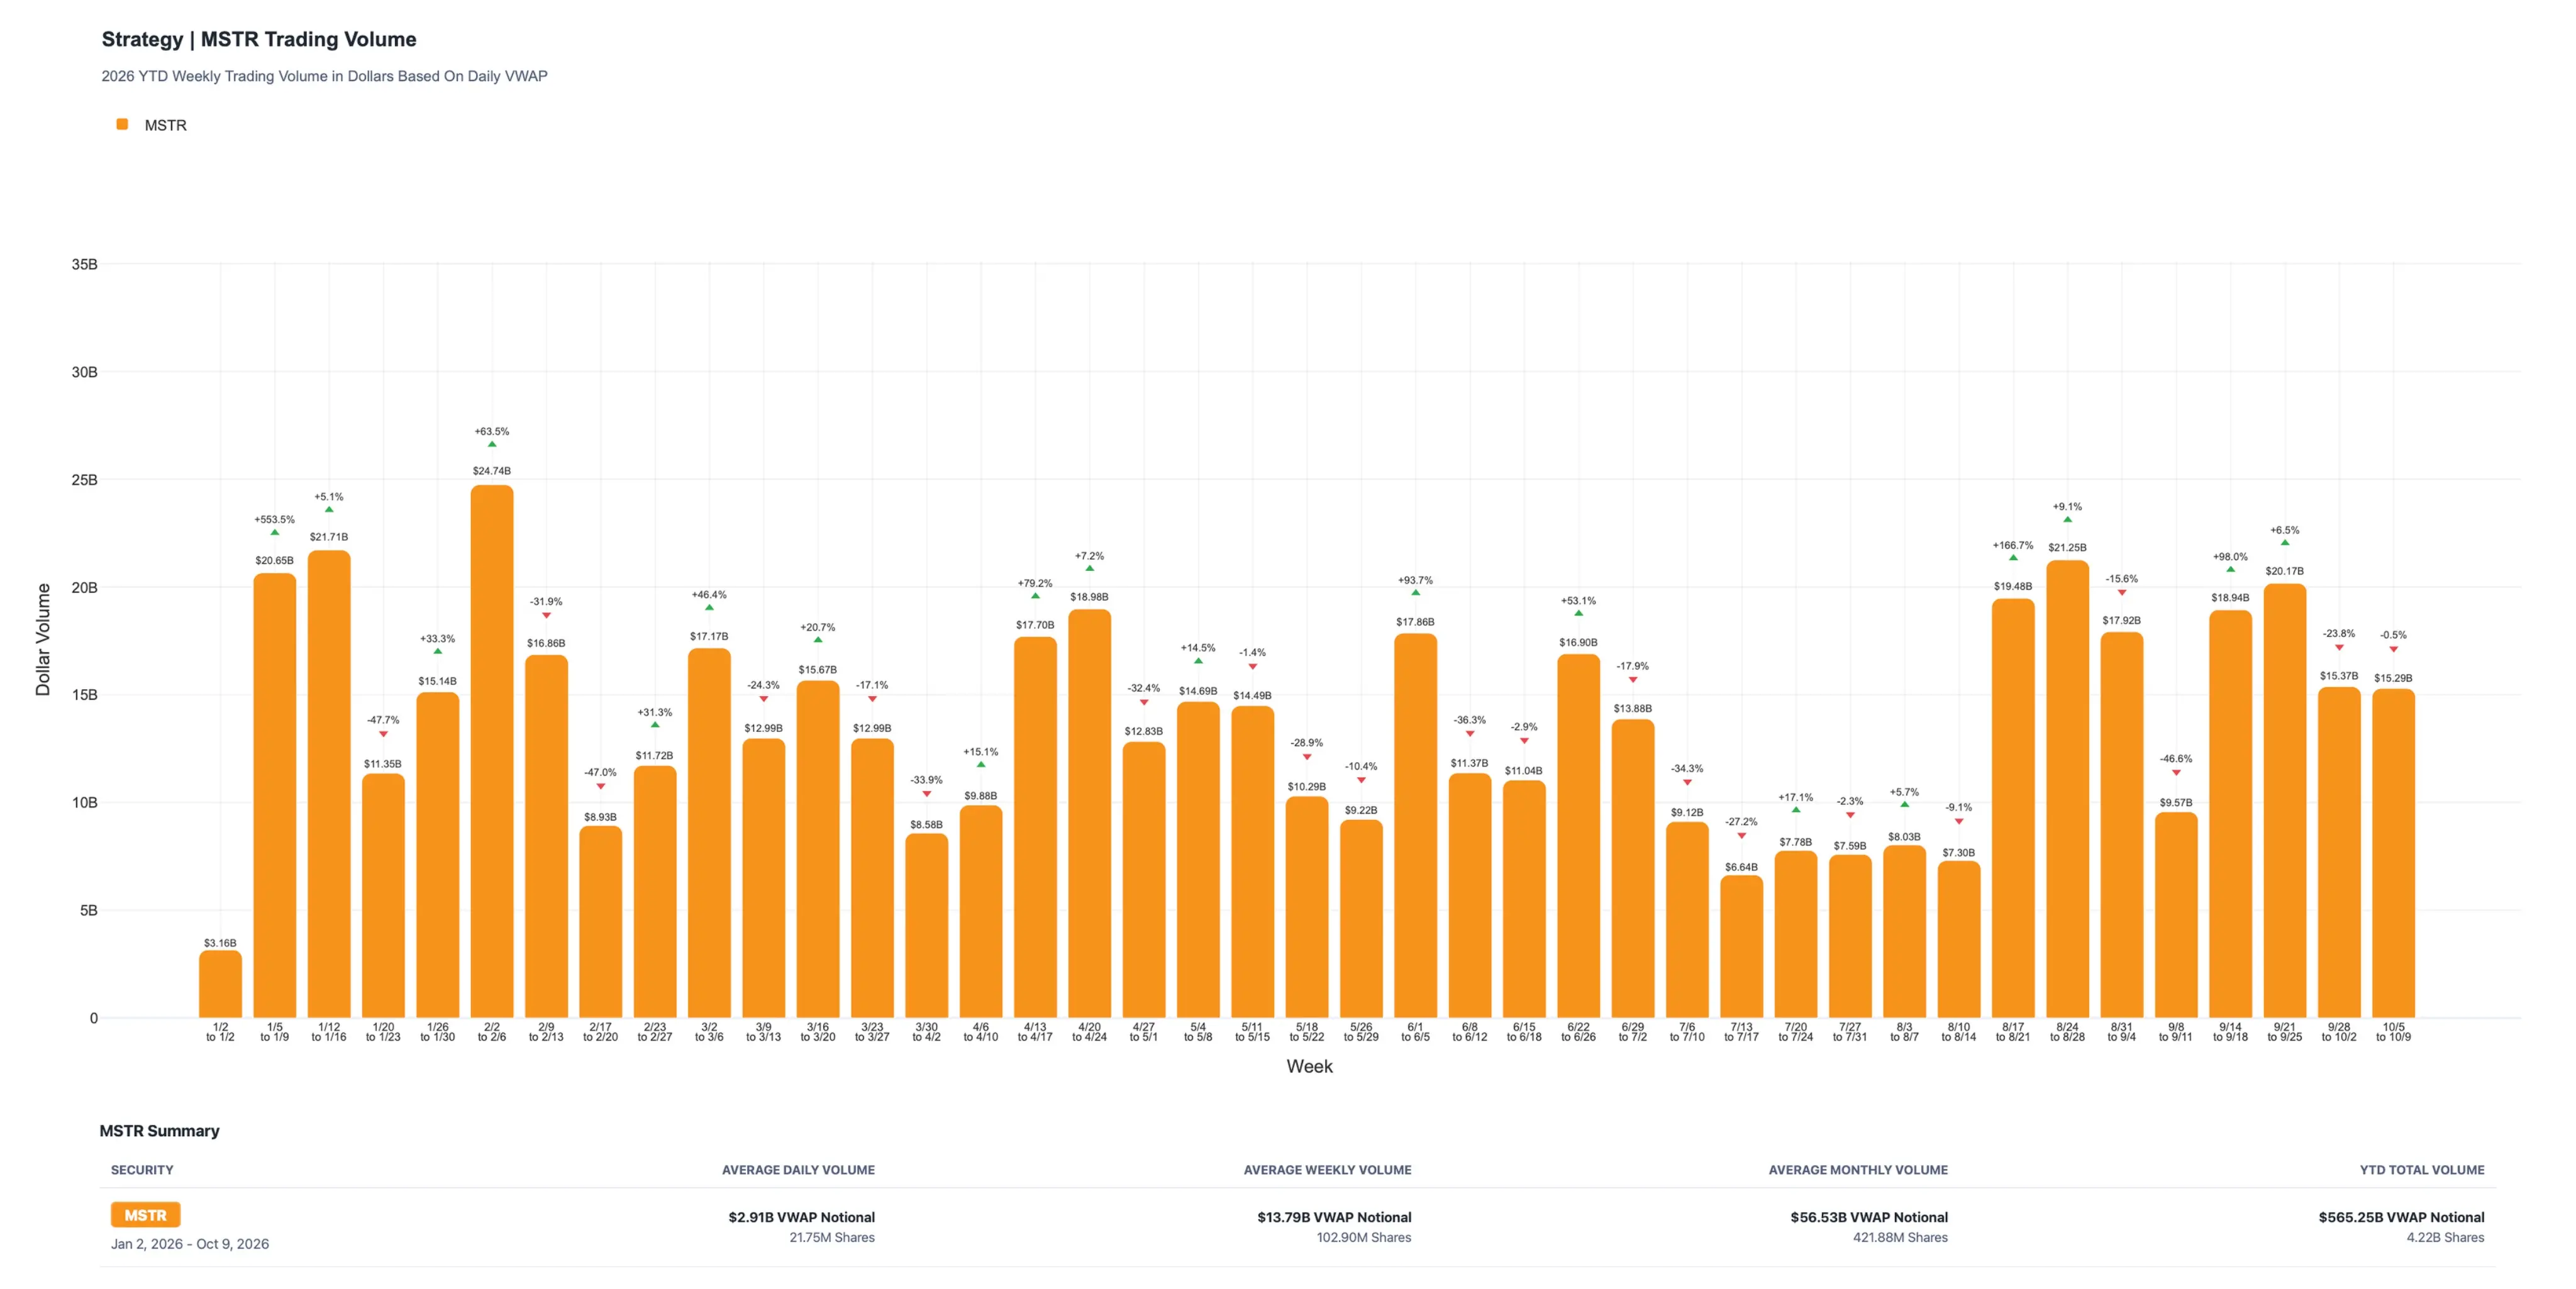
However, index adjustment sell-offs typically concentrate around the close on the effective date, and the impact will be more concentrated than if spread out over average daily trading volume. Strategy's scale has also changed significantly; according to the MSCI list, its adjusted market capitalization has risen from about $23.9 billion during the May simulation to about $40.3 billion.
Looking solely at the scale of the sell-off, Strategy's assertion that the new rules will not have a material impact seems plausible.
The issue lies in the boundaries of the business. Strategy's business, in addition to holding Bitcoin, also includes continuous financing to buy coins.
In documents submitted to the SEC, Strategy stated that in both the first and second quarters of this year, its 10-Q filings listed index exclusion as a risk factor, stating that if MSCI or other major index publishers were to exclude it or take measures such as delaying inclusion or restricting index-related adjustments, funds tracking the index might be forced to sell or buy less of its Class A common stock, thereby causing significant adverse effects on the price and liquidity of its Class A common stock and other listed securities.
JPMorgan pointed out last year that while active managers are not obligated to follow index adjustments, being removed from major indices will definitely be viewed negatively by the market and raise concerns about Strategy's future equity and debt financing costs and capabilities. Bloomberg believes that the new regulations have added new pressure to the financing model behind Saylor's massive Bitcoin holdings.
This financing model has already been transforming. Bloomberg stated that as the premium of common stock relative to Bitcoin holdings disappears, Strategy has shifted to issuing perpetual preferred shares that do not dilute common stock equity, with a current circulation size exceeding $14 billion. However, its floating-rate preferred shares STRC have not been newly issued since May, and the company has instead repurchased over $1 billion.
According to research firm K33, STRC increases Strategy's annual dividend obligations by approximately $725 million, equivalent to about 8740 Bitcoins at a price of $83,000 per Bitcoin. K33 believes that the preferred stock financing model is a mistake and prefers that Strategy raise funds through common stock ATM and other methods.
This year, Strategy was also forced to sell Bitcoin and announced plans to potentially sell Bitcoin to raise up to $1.25 billion for dollar reserves, preferred stock dividends, interest expenses, or buybacks. Saylor is seeking to change the preferred stock dividend payment from bi-monthly or quarterly to daily, with the relevant shareholder vote ending on October 28.
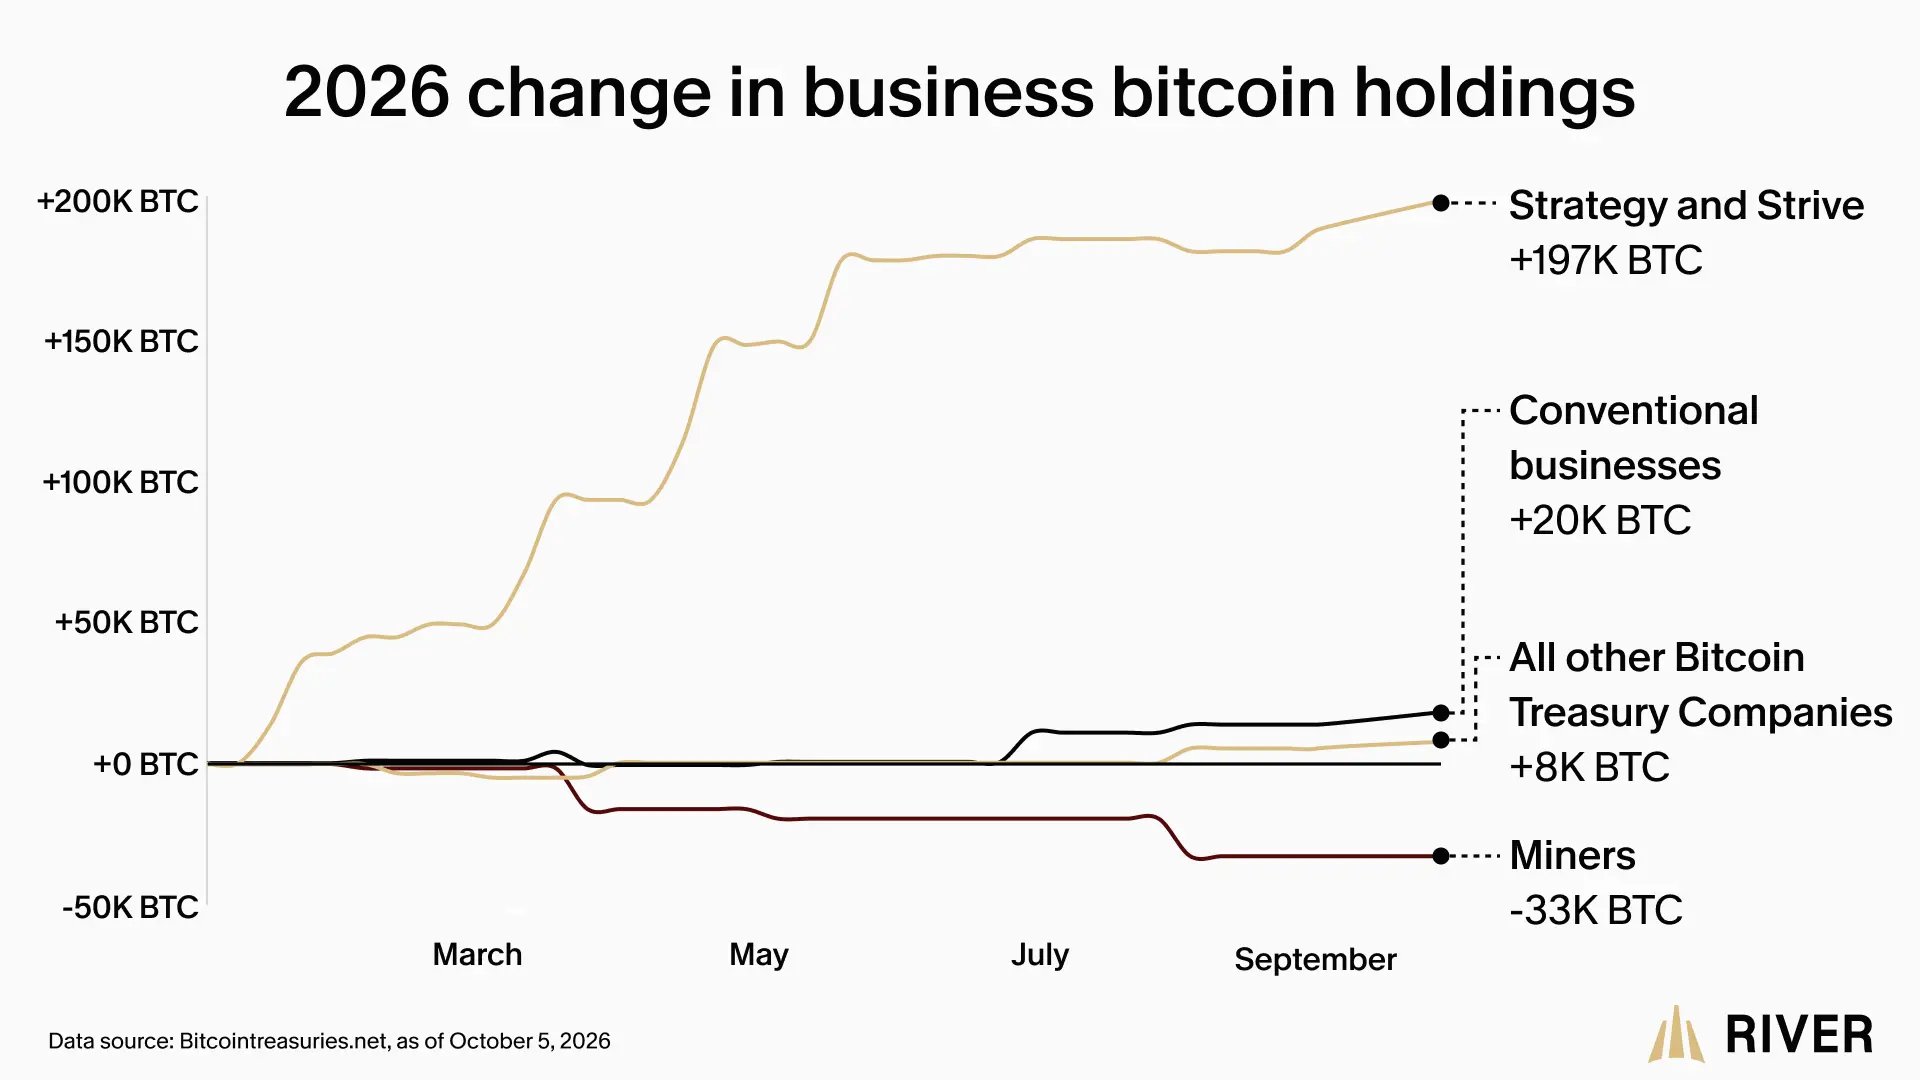
Meanwhile, buying pressure at the industry level is also shrinking. A report from Bitcoin financial services platform River shows that companies have net increased their holdings by 193,000 Bitcoins this year, with Strategy and Strive collectively increasing their holdings by 197,000, exceeding the total net purchases by companies, while other Bitcoin treasury companies have only bought a total of 8,000 Bitcoins.
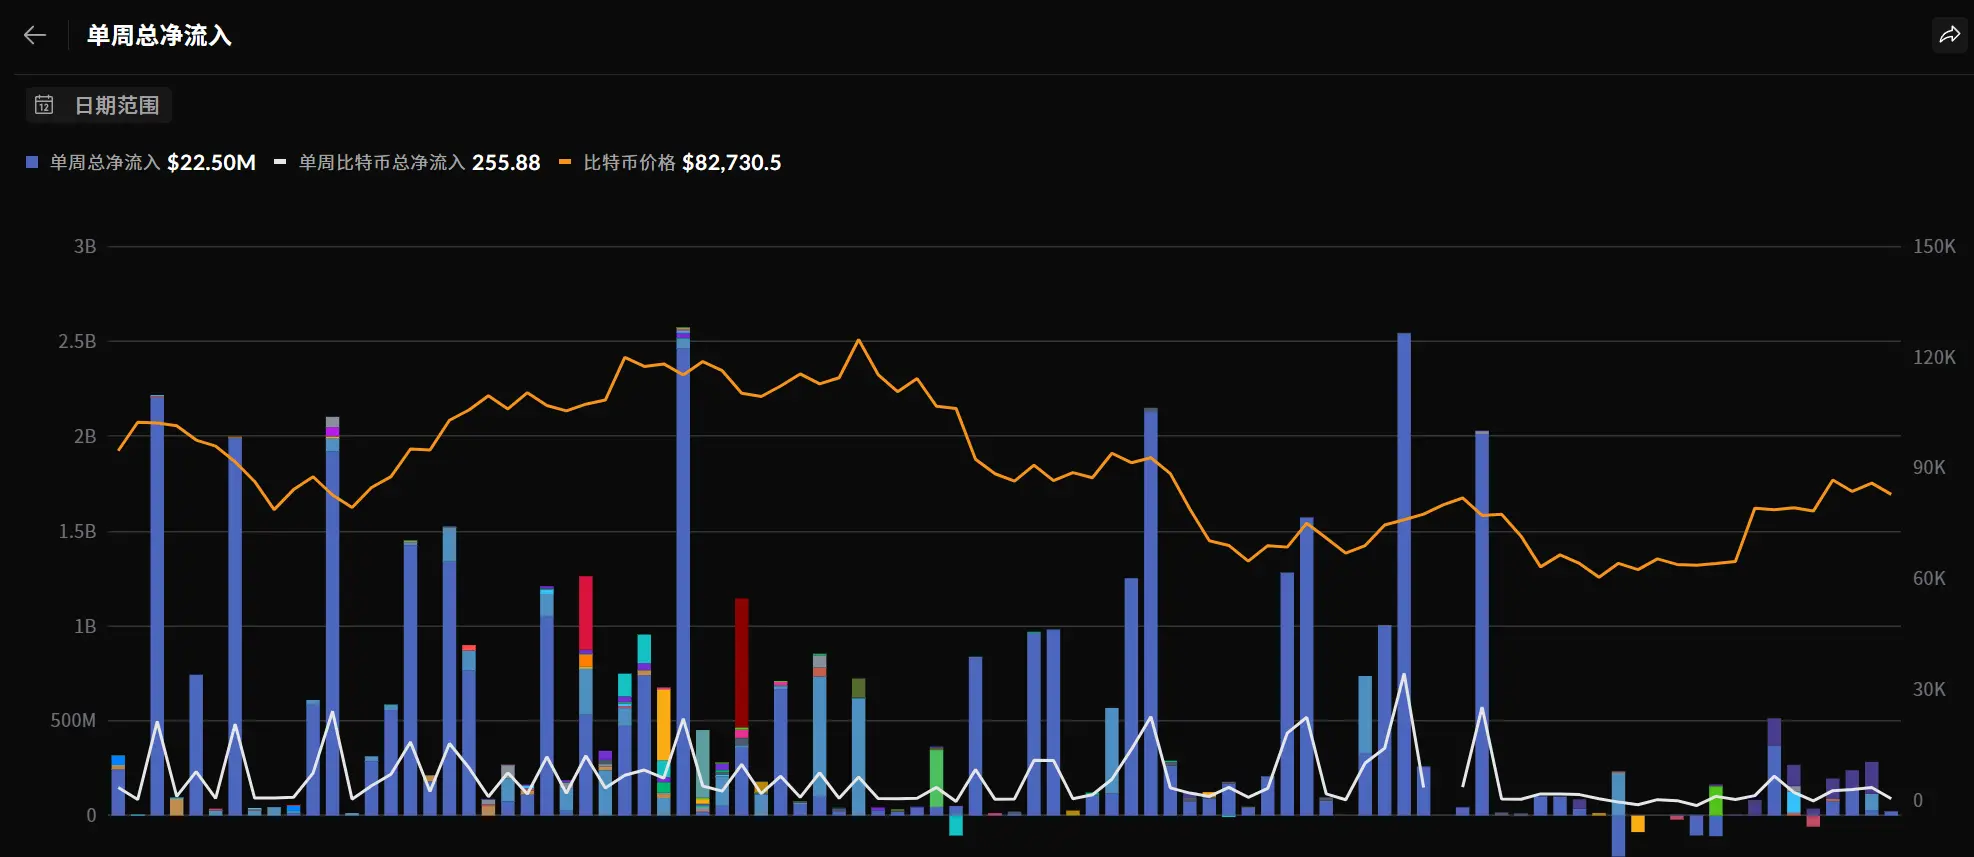
SoSoValue data shows that as of the week of October 12, global listed companies, excluding mining companies, had a net Bitcoin purchase of only $22.5 million, a decrease of 90.6% compared to two weeks ago.
The same logic applies to Metaplanet, where CEO Simon Gerovich disclosed that the company has just announced the issuance of zero-coupon convertible bonds worth 52 billion yen, maturing in 2031, while simultaneously advancing share buybacks, also relying on external financing for expansion.
The difference is that Metaplanet belongs to the MSCI small-cap stocks, with a free float-adjusted market value of about $800 million, and the scale of passive funds involved in its removal is much smaller than that of Strategy.
Returning to the initial question. A one-time sell-off may have limited impact as Strategy claims, but for a company increasingly reliant on capital market blood transfusions, the cost of losing a portion of passive buying may only become apparent during the next financing round.
 Risk warning
 Risk warning

Popular articles





