








The U.S. Treasury Department's investigation has not released signals for reducing bond issuance, U.S. Treasury yields have risen, and the 10-year yield has climbed back to 5.12%
 Core Viewpoint


 In a survey consulting primary dealers, the Ministry of Finance asked about the repurchase plan for long-term government bonds, how to improve repurchase efficiency, the timing of short-term bond issuance, and the economic and financing outlook, but did not directly address the issue of reducing the supply of long-term bonds. Some investors originally expected that the Ministry of Finance would use this questionnaire to more clearly hint at considering a reduction in the scale of long-term bond auctions, or even stopping the issuance of 20-year government bonds. The refinancing announcement released by the Ministry of Finance on November 4 became the next point of observation. Citigroup expects that at that time, the auction scale for 20-year and 30-year U.S. Treasury bonds will each be reduced by $3 billion, believing that this survey indicates the Ministry of Finance is considering reducing the issuance of long-term bonds.
Author: Wall Street Journal
The latest primary dealer survey from the U.S. Treasury did not release a clear signal regarding an imminent reduction in the scale of long-term Treasury bond auctions, disappointing investors betting on government action to lower long-term interest rates. As a result, U.S. Treasury prices fell, and yields rose overall.
This survey is part of the Treasury's preparation for the quarterly refinancing plan to be announced on November 4. The market originally hoped to find clues in the questionnaire about whether Treasury Secretary Janet Yellen might adjust the issuance scale of long-term Treasury bonds, especially the recent discussions about the possibility of reducing or even halting the issuance of 20-year Treasury bonds. However, the Treasury only broadly inquired about what auction scale adjustments should be considered in the future, without explicitly suggesting that a reduction in long-term bond supply is imminent.
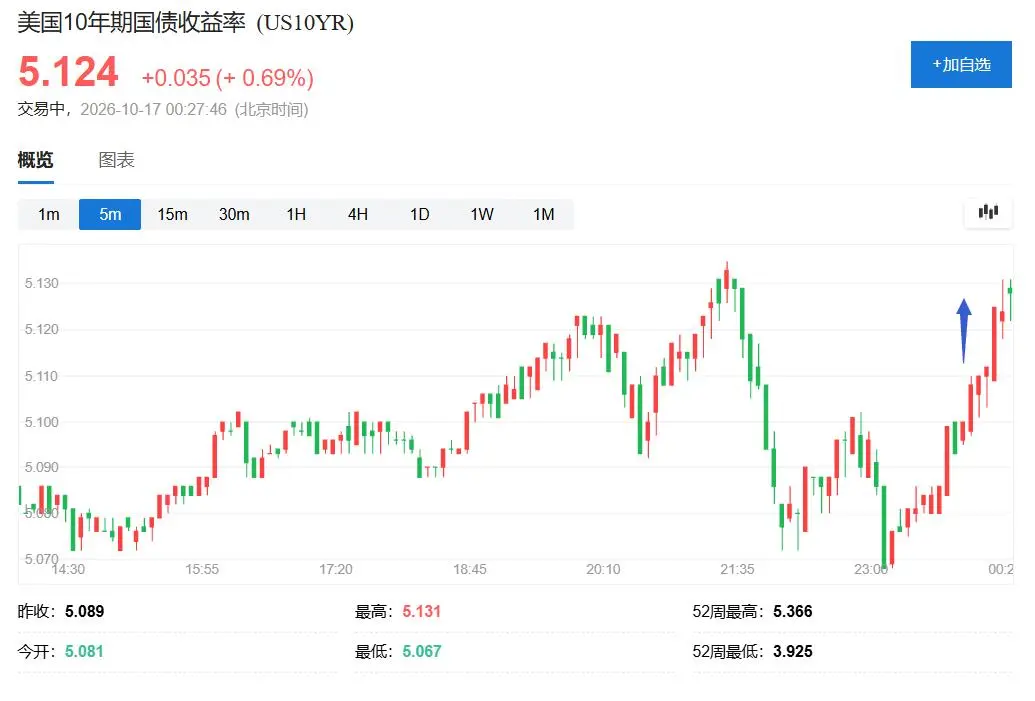
On Friday, the 16th, during the midday trading session of U.S. stocks, after the details of the Treasury's survey were released, U.S. Treasury yields rose across the board. The yield on the benchmark 10-year Treasury bond rose back above 5.12%, approaching the intraday high of 5.1315% set before the stock market opened, with the intraday increase expanding to 6.5 basis points; the yield on the 20-year Treasury bond rose by 5.4 basis points during the day, and the yield on the 30-year Treasury bond's intraday increase expanded to about 5 basis points, while the yield on the 2-year Treasury bond erased its intraday decline and turned positive.
At the same time, oil prices had already accelerated before the survey was released, adding upward pressure on Treasury yields. Therefore, the rise in yields on Friday reflected both the market's disappointment at the Treasury not releasing a signal for supply reduction and the influence of changes in energy prices.
What Did the Treasury Ask, and What Is the Market Waiting For
In this survey, the Treasury consulted primary dealers, focusing on what adjustments should be considered for Treasury bond auction sizes in the context of structural changes in investor demand and the potential evolution of medium-term demand expectations in the future.
Such surveys are routine preparatory work for the Treasury's quarterly refinancing decisions, aimed at understanding the judgments of major dealers regarding government financing needs, investor demand, and market operating conditions, providing references for determining the scale and structure of Treasury bond issuance. The survey itself is not a bond issuance plan and does not imply that the Treasury has decided to adjust the issuance scale for any maturity.
According to reports, this questionnaire also involved several debt management issues:
Long-term Treasury bond repurchase plan: The Treasury asked whether expanding the scale of long-term Treasury bond repurchases improved market liquidity and trading operations; how larger repurchases affect dealers' ability to handle customer buy and sell orders, and the willingness of customers to participate in repurchases directly or indirectly.
How to further improve repurchase efficiency: The Treasury sought dealers' opinions on what adjustments could be made to the repurchase plan.
Timing of Treasury bill and floating-rate bond issuance: The Treasury inquired whether the current practice of avoiding issuing Treasury bills and floating-rate bonds on Federal Open Market Committee (FOMC) meeting days should be adjusted.
Economic and financing outlook: Dealers were also required to provide forecasts on the economy, fiscal policy, monetary policy, and the Treasury's financing needs for the next few fiscal years.
What truly disappointed the market was that the Treasury did not directly address the issue of reducing long-term Treasury bond supply. Some investors had originally hoped that the Treasury would use this questionnaire to more clearly indicate that it was considering reducing the auction size of long-term bonds or even halting the issuance of 20-year Treasury bonds in response to the Trump administration's efforts to lower financing costs.
Blake Gwinn, head of U.S. interest rate strategy at RBC Capital Markets, stated that if the Treasury wanted to signal or influence yields through the questionnaire, it could have posed more direct questions. He believes that this survey did not convey substantive signals; considering that some investors expected significant adjustments, such as halting the issuance of 20-year Treasury bonds, this outcome may disappoint the market.
20-Year Treasury Bonds Become the Focus, Wall Street Bets on Treasury Adjusting Bond Issuance Structure
The market is particularly sensitive to the survey, related to the recent high levels of long-term U.S. Treasury yields. As the U.S. fiscal deficit continues and interest payments on existing debt increase, the government's financing needs are rising, making the pressure of long-term Treasury bond supply one of the core issues of concern for investors.
Bloomberg reported that some Wall Street institutions had previously bet that the Treasury might alleviate the pressure of long-term bond supply by adjusting the bond issuance structure. Market discussions are particularly focused on the 20-year Treasury bond: whether the Treasury will reduce its issuance scale or even completely cancel the issuance of this maturity.
From a financing mechanism perspective, the Treasury needs to meet the overall borrowing needs of the government, but this does not mean it must issue bonds of each maturity in fixed proportions. If the demand for short-term financing instruments and the market's capacity to absorb them allow, the Treasury can theoretically increase short-term debt issuance to reduce the supply pressure on the long-term bond market. However, adjusting the maturity structure will also change the government's future refinancing arrangements and cannot simply be understood as reducing total borrowing needs.
Molly Brooks, U.S. interest rate strategist at TD Securities, stated that the Treasury's question setting remains too broad and does not explicitly inquire about reducing long-term bond supply, leading to market disappointment. She expects that the scale of long-term Treasury bond auctions may not be adjusted until at least February 2027.
This judgment implies that the optimistic scenario some investors had previously bet on—namely, that the Treasury would announce a reduction in long-term issuance scale in the November quarterly refinancing plan, or even cancel the 20-year Treasury bond—may not materialize quickly. The questionnaire did not provide a clear signal for supply reduction, nor does it mean that relevant adjustments have been ruled out.
However, Citigroup strategists maintain their forecast, believing that the U.S. Treasury will reduce the issuance volume of long-term bonds in the November quarterly refinancing announcement, expecting the auction sizes of 20-year and 30-year U.S. Treasury bonds to each be reduced by $3 billion. They pointed out that the relevant questions in the survey indicate that Treasury officials are considering taking this action.
Citigroup's report stated that since the last refinancing announcement, there has been a significant sell-off in long-term U.S. Treasury bonds, and in several long-term bond repurchase operations following the Treasury's announcement to raise the repurchase limit, the market has performed relatively weakly. These factors will prompt the Treasury to shift long-term bond issuance towards short-term bonds.
Failed Bond Issuance Signals Combined with Rising Oil Prices Put Pressure on Long-Term Yields
In addition to the Treasury survey, rising oil prices have also increased upward pressure on U.S. Treasury yields. Higher energy prices may reignite market concerns about inflation and affect investors' judgments about the future interest rate path of the Federal Reserve. For long-term Treasury bonds, inflation expectations, future short-term rates, and the term premium demanded by investors will all influence yield pricing.
This also explains why the market's reaction this time is focused on long-term U.S. Treasury bonds. Long-term Treasury bond prices are particularly sensitive to changes in supply expectations: if the market originally expected the Treasury to reduce long-term bond issuance, once relevant signals are absent, investors may reassess the supply of long-term bonds they need to hold and the returns required to bear interest rate risk.
However, the rise in yields on Friday cannot be entirely attributed to the Treasury survey. Changes in oil prices are also mentioned as driving factors, and the survey results merely disappointed the market's previous expectations for policy adjustments without directly proving that the future issuance scale of long-term Treasury bonds will remain unchanged.
The November 4 Refinancing Announcement Becomes the Next Observation Point
The Treasury will announce the next quarterly refinancing plan on November 4, at which point the market can further assess the government's specific considerations regarding borrowing needs, the issuance scale of different maturities of bonds, and repurchase arrangements.
The U.S. government faces a persistent fiscal deficit, and interest payments on existing debt are also increasing, which forces the Treasury to weigh financing costs, market demand, and the maturity structure of debt. Reducing the supply of long-term bonds to lower long-term yields is one potential path of interest to the market, but it is not without constraints.
Before the formal announcement is made, the dealer survey provides a market opinion inquiry rather than a policy commitment. The decline in long-term U.S. Treasury bonds and the rise in yields on Friday reflect that the market originally expected the Treasury to release a more proactive signal for supply reduction, but did not receive sufficiently clear evidence from this questionnaire. Moving forward, investors will continue to pay attention to whether the Treasury will adjust the issuance arrangements for long-term Treasury bonds in the November refinancing plan and whether related measures can truly alleviate the supply pressure on long-term U.S. Treasury bonds.
 Risk warning
 Risk warning
Popular articles





