








The Federal Reserve is expected to remain steady, and Waller may signal a hawkish stance
 Core Viewpoint


 The market generally expects the Federal Reserve to keep interest rates unchanged this week, but Waller's statement on future rate hikes is the key.
Source: Jinshi Data
As Federal Reserve officials hold a monetary policy meeting this week, they are facing a critical debate: what actions can and should the central bank take in the face of inflation pressures that show no clear signs of abating in the short term, and how will they choose to proceed.
The Federal Open Market Committee (FOMC) will announce its decision at 2 AM Beijing time on Thursday. The market widely expects the Federal Reserve to keep the benchmark interest rate unchanged, having raised it by 25 basis points in September. However, the real focus for investors is how policymakers will signal future actions, especially what signals Federal Reserve Chairman Kevin Warsh will send.
Brett Ryan, a senior U.S. economist at Deutsche Bank, stated that he will pay close attention to how Warsh describes the future path of monetary policy. Warsh has been reluctant to reveal policy direction in advance, hoping the Federal Reserve will reduce its reliance on "forward guidance" and no longer frequently signal policy direction to the market as it has since the 21st century.
In a report to clients, Ryan wrote that Warsh might imply that recent inflation data further confirms the judgment made at the September meeting: over time, the Federal Reserve may still need to tighten policy further. However, skipping the rate hike in October could give officials more time to assess changes in data.
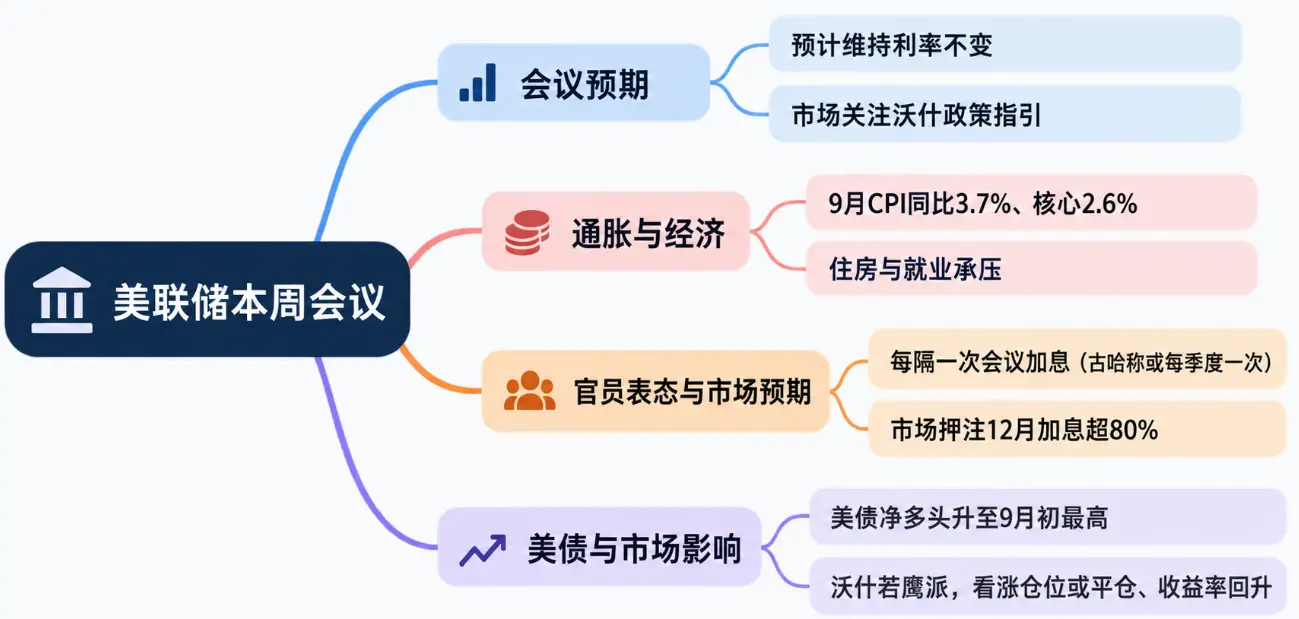
Inflation Heats Up Again, Housing and Job Markets Under Pressure
Recent inflation data has not alleviated the price pressures that have intensified earlier this year.
The Consumer Price Index (CPI) shows that the overall inflation rate in the U.S. rose to 3.7% year-on-year in September, primarily driven by soaring energy prices. Excluding the volatile food and energy prices, the core CPI rose by 2.6% year-on-year, still above the Federal Reserve's 2% inflation target, and up 0.3 percentage points from August, indicating that price pressures have not fully eased.
Meanwhile, mortgage rates are above 7%, further putting pressure on the U.S. housing market. The job market is showing a "low layoffs, low hiring" situation: the number of layoffs is close to the lowest level since the late 1960s, but unemployed individuals still face difficulties in finding new jobs.
Against this backdrop, adjustments to monetary policy become particularly complex. Pausing rate hikes helps the Federal Reserve assess how much impact previous tightening measures have had on the economy and financial environment; however, if inflation does not decrease, the Federal Reserve may have to raise rates further. At that time, the housing market, consumer loans, and other interest-sensitive economic sectors may face greater pressure.
Warsh aims to create a more flexible policy stance for the Federal Reserve, unwilling to commit prematurely to future interest rate paths, but instead prefers to let the market judge policy direction based on subsequent data releases. The challenge is that the Federal Reserve must demonstrate its determination to control inflation while not locking in the magnitude and pace of future rate hikes too early.
Economists Warn: Rising Risks in Policy Execution
Krishna Guha, chief economist and head of central bank strategy at Evercore ISI, believes there is a considerable risk of missteps in the current policy environment.
In a report on Monday, Guha stated that Warsh remains alert to market risks and should theoretically be able to demonstrate a calm and steady leadership style, but the Federal Reserve's policy execution faces significant challenges.
He pointed out that the Federal Reserve has not adequately explained how it measures the risks associated with its dual mandate—maintaining low inflation and achieving full employment—nor has it clearly articulated how the central bank assesses the degree of tightening in current monetary policy. These information gaps make it more difficult for the market to judge how the Federal Reserve will act next.
Despite persistently high inflation, the U.S. unemployment rate remains generally stable. Meanwhile, the financial environment is also changing. The Chicago Fed Financial Conditions Index shows that since the rate hike in September, financial conditions have tightened slightly, with increased stock market volatility being one contributing factor.
Recently, statements from key officials such as Federal Reserve Vice Chair Jefferson and New York Fed President Williams point to a possibility: if inflation pressures persist, the Federal Reserve may adopt a pace of raising rates every other meeting. However, there is still no clear answer on how many times rates need to be raised.
Guha believes that Warsh's recent remarks at the World Bank and International Monetary Fund events in Bangkok align closely with the mainstream views within the FOMC. This suggests that the Federal Reserve may adopt a cautious and orderly tightening pace, potentially raising rates once per quarter as a baseline path, adjusting judgments based on data rather than preemptively ruling out any interest rate levels.
He added that if inflation data continues to disappoint or if economic growth momentum fails to weaken, the Federal Reserve may further raise rates.
Market Bets on December Rate Hike, Economists Divided
According to the CME's FedWatch tool, federal funds rate futures indicate that the market assigns about a 10% probability to a rate hike by the Federal Reserve this week, while the probability of a rate hike in December has exceeded 80%. The market also sees a certain possibility of another rate hike in March 2027; by the end of 2027, the probability of another rate hike by the Federal Reserve is about 50%.
However, economists have significant disagreements on whether the Federal Reserve should continue tightening policy.
Economists at Citigroup believe that inflation data may ease in the coming months, providing a reason for the Federal Reserve to remain on hold, and could even create conditions for rate cuts starting next year. However, Citigroup currently still predicts that the Federal Reserve will raise rates in December.
Mohamed El-Erian, chief economic advisor at Allianz, expects that the Federal Reserve will ultimately raise rates, but he believes this is a mistake, as higher borrowing costs could harm vulnerable areas like the housing market and exacerbate economic inequality.
El-Erian stated on CNBC on Monday that the market's belief that the Federal Reserve will not act this time is correct, but Warsh must use relatively hawkish language to explain the decision, as inflation data is generally above expectations.
He believes that addressing inflation concerns and the rising U.S. Treasury yields should rely on "fiscal restraint rather than monetary tightening." If the Federal Reserve ultimately chooses to further tighten policy, the impact may not be limited to the technology sector. El-Erian pointed out that the technology sector may be relatively less affected, while the housing market, auto loans, and personal consumer loans may face greater pressure.
For the Federal Reserve, the difficulty of this meeting lies not only in deciding whether to raise rates but also in how to explain the reasons for pausing action while retaining necessary policy space. If Warsh sends stronger inflation signals, market expectations for a December rate hike may be further strengthened; if he emphasizes patience in observing data, it may ease recent tightening bets. Regardless, the trend of inflation will still determine the policy path.
Treasury Bulls Bet Intensifies, If Warsh Sends Hawkish Signals, Yield Down Trading Faces Reversal
If the Federal Reserve takes a tougher stance at this week's monetary policy meeting, the bullish bets that have accumulated in the U.S. Treasury market may face a sharp reversal.
If Warsh sends hawkish signals on key issues like inflation, the market may reassess what level the Federal Reserve will ultimately raise rates to, potentially triggering a painful wave of liquidations. Previously, some traders bet on safe-haven funds continuing to flow into U.S. Treasuries, establishing bullish positions with falling yields and rising bond prices.
David Bieber, a strategist at Citigroup, stated that the most noticeable change in the market before the FOMC meeting is that investors have shifted to tactical bullish positions in both the U.S. Treasury and European bond markets. He noted that traders are chasing the bond rally by establishing bullish positions, although the overall market remains in a net short position.
CME's open interest data shows that over the past week, traders have been reducing their short positions in U.S. Treasuries while betting that the previous rebound can continue. This rally is supported by factors including market concerns about the sustainability of AI trading and pressures in the French bond market.
Last Friday, the U.S. Treasury futures market saw large-scale liquidations, particularly concentrated in contracts related to 10-year Treasuries. The day before, the Treasury market had just recorded its best trading day in over two years, while contracts related to 10-year Treasuries saw a significant increase in risk exposure, consistent with short covering.
JPMorgan's weekly survey also showed that the market's net long positions have risen to the highest level since early September.
Ed Al-Hussainy, a portfolio manager at Columbia Threadneedle, stated that the key factor determining whether the market can maintain current pricing is the Federal Reserve's policy guidance.
This means that even if this meeting ultimately does not result in a rate hike, Warsh's statements on subsequent policy could still change market trading logic. If the Federal Reserve clearly signals that it is still prepared to further tighten policy, traders may need to reassess their bullish positions in bonds, and the recently established bullish trades could face the risk of being forced to liquidate.
Meanwhile, traders in the options market are actively hedging risks for their portfolios in anticipation of further declines in yields and continued increases in bond prices. This demand has pushed up the costs of related hedging options, with costs rising to the highest level since March last week.
Many traders are protecting themselves by buying different structures of call options, with some strategies betting that the yield on 10-year Treasuries will further decline to around 4.6% in the coming weeks.
The skew between call and put options in the options market has also changed significantly, with market pricing shifting heavily toward call options. In other words, compared to hedging against the risk of rising yields, traders are now willing to pay a higher premium to guard against further declines in yields.
This position change reflects the market's continued expectation for a rebound in U.S. Treasuries, but it also means that trading is more susceptible to policy signal shocks. If Warsh emphasizes that inflation pressures persist and the Federal Reserve still needs to raise rates, investors may quickly withdraw their bullish positions, putting pressure on bond prices and causing yields to rise; conversely, if he does not further strengthen tightening expectations, recent bullish trades may continue to receive support.
Thus, this week's Federal Reserve meeting is not only about whether to adjust short-term rates but may also become a key juncture for repricing positions in the Treasury market. The real risk is that current bullish bets have clearly increased, and once policy guidance deviates from market expectations, the trading forces that originally drove bond prices up may also turn into pressure for accelerated liquidations.
 Risk warning Risk warning

Popular articles





