Grayscale: Reassessing the Combined Value of Bitcoin and Crypto Assets
 Core Viewpoint


 Grayscale pointed out that Bitcoin's realized volatility has dropped to around 40%, falling within the range of some large-cap U.S. stocks. Returns exhibit fat tail and momentum characteristics, with a few trading days dominating long-term returns; after adjusting for volatility, the drawdown is not more extreme than that of stocks and bonds. Traditional factors have low explanatory power, and a small allocation historically improved portfolio efficiency. Sector correlation has decreased, and leadership rotation indicates that crypto is no longer a single Bitcoin beta.
Author: Zach Pandl, Charlie Perkins, Zach Pandl is the Head of Research at Grayscale, and Charlie Perkins is a Research Associate at Grayscale (CFA)
Compiled by: Gu Yu, ChainCatcher
Bitcoin is no longer the asset it was 15 years ago or even 10 years ago. The investment risks associated with Bitcoin and the broader category of crypto assets should be viewed from a completely new perspective.
Over the past decade, Bitcoin's actual volatility has significantly decreased and is now within the range of volatility seen in large-cap U.S. stocks.
Bitcoin's returns can experience extreme fluctuations in both directions, and strong momentum leads to returns that tend to cluster, with reversals often being very rapid. A very small number of trading days have played a decisive role in Bitcoin's compound returns.
In percentage terms, Bitcoin's drawdowns remain severe, but when adjusted for its higher underlying volatility, its drawdowns appear less extreme compared to stocks and bonds.
Traditional market factors explain Bitcoin's returns far less effectively than they do for stocks, bonds, or private equity, supporting its potential role as a portfolio diversification tool.
Historical backtesting indicates that a moderate allocation to Bitcoin can enhance portfolio efficiency without proportionately increasing volatility or maximum drawdown.
Investment opportunities are not limited to Bitcoin: Bitcoin can only explain about half of the return differences in the crypto industry, correlations have fallen from early highs, and leading performances among assets are showing a rotational state.
Crypto assets are often evaluated under outdated risk perspectives. Many asset allocators still view Bitcoin as an asset with uniquely extreme volatility, believing its performance resembles that of high-leverage risk assets, and consider the broader crypto space as a single, undifferentiated risk exposure. Each assumption is worth re-examining. Over time, Bitcoin's market structure, investor base, and role within the broader asset class have undergone substantial changes.
For allocators, the core distinction lies in the difference between single volatility and portfolio risk. Volatility measures the magnitude of an asset's own fluctuations; portfolio risk, on the other hand, depends on why it fluctuates, when it fluctuates, and whether these fluctuations overlap with existing exposures. From a portfolio perspective, Bitcoin's volatility is not just a risk to be minimized; it may also represent a differentiated source of returns.
This report examines crypto asset risk from four dimensions:
Bitcoin's 18-Year Journey to Maturity: How Bitcoin's Volatility Has Evolved
Beyond Surface Volatility: What Momentum and Tail Behavior Reveal About Its Return Distribution
Bitcoin for Portfolio Diversification: How Bitcoin Interacts with Diversified Portfolios
Diversification Allocations Beyond Bitcoin: How Differentiated the Broader Crypto Space Has Become
Evidence suggests that the maturity of this asset class has outpaced many analytical frameworks used to assess it. We believe it deserves a risk framework tailored to the current state of asset classes today, rather than one based on conditions from a decade ago.
Bitcoin's 18-Year Journey to Maturity
Bitcoin has long been known for its volatility. In its early development stages, facing a market size of only single digits (in the billion-dollar range), its volatility often exceeded 100%, sometimes even approaching 200%. [1] As its market capitalization and liquidity have grown over its 18-year journey, increased institutional participation, the emergence of safer investment tools like Bitcoin exchange-traded products (ETPs), and improved regulatory clarity have collectively created a more mature trading environment (Chart 1). Currently, its actual volatility is in the mid-40% range, far below the triple-digit highs of the early cycle. The risk characteristics of Bitcoin available to investors today are completely different from those of a decade ago.
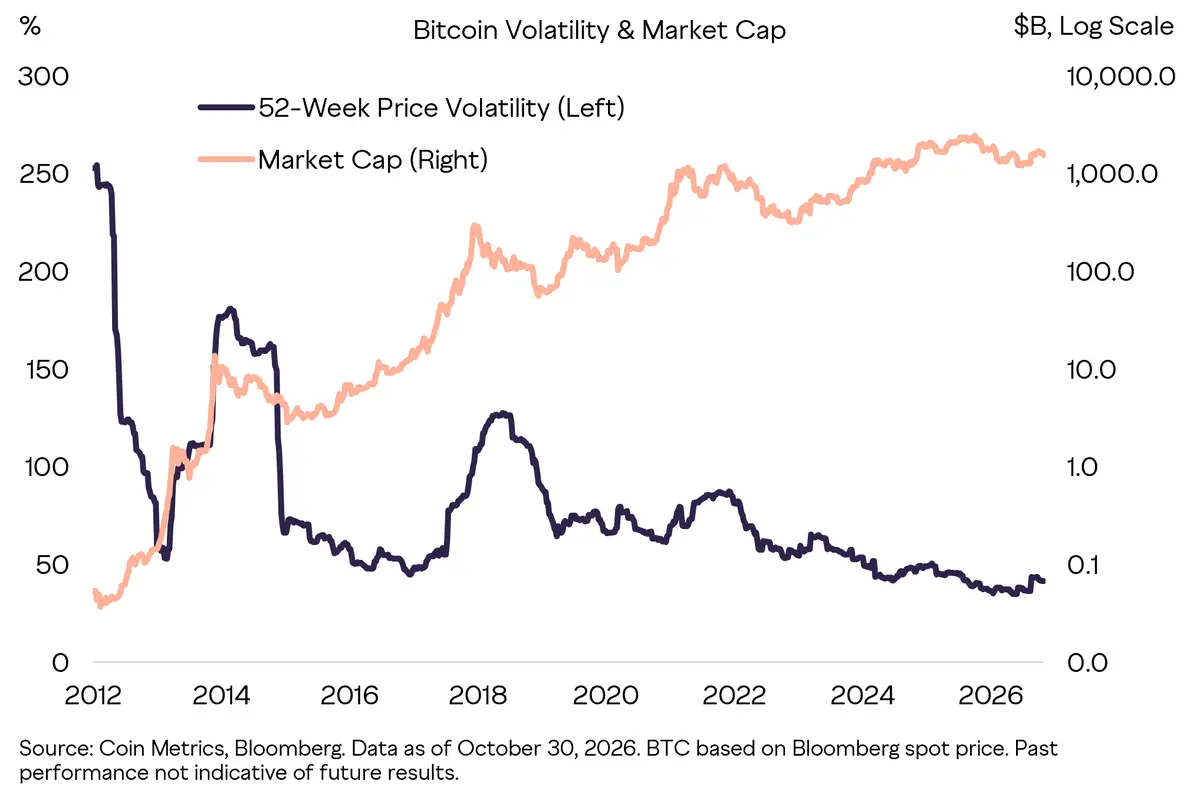
Chart 1: Bitcoin's Volatility Continues to Decline with Market Capitalization Growth
Bitcoin's volatility is often compared to that of the S&P 500 index, but the individual stocks within that index provide a more comparable reference point. The index is a portfolio whose volatility reflects the diversification effects of hundreds of offsetting positions. The situation with individual stocks is quite different. Bitcoin's volatility is about 43%, still higher than most S&P 500 constituents, but lower than approximately 19% of the stocks in that index—including some large-cap stocks that investors already hold (Chart 2). [2] Bitcoin remains a high-volatility asset, but its volatility has not departed from the observation range of publicly traded stocks.
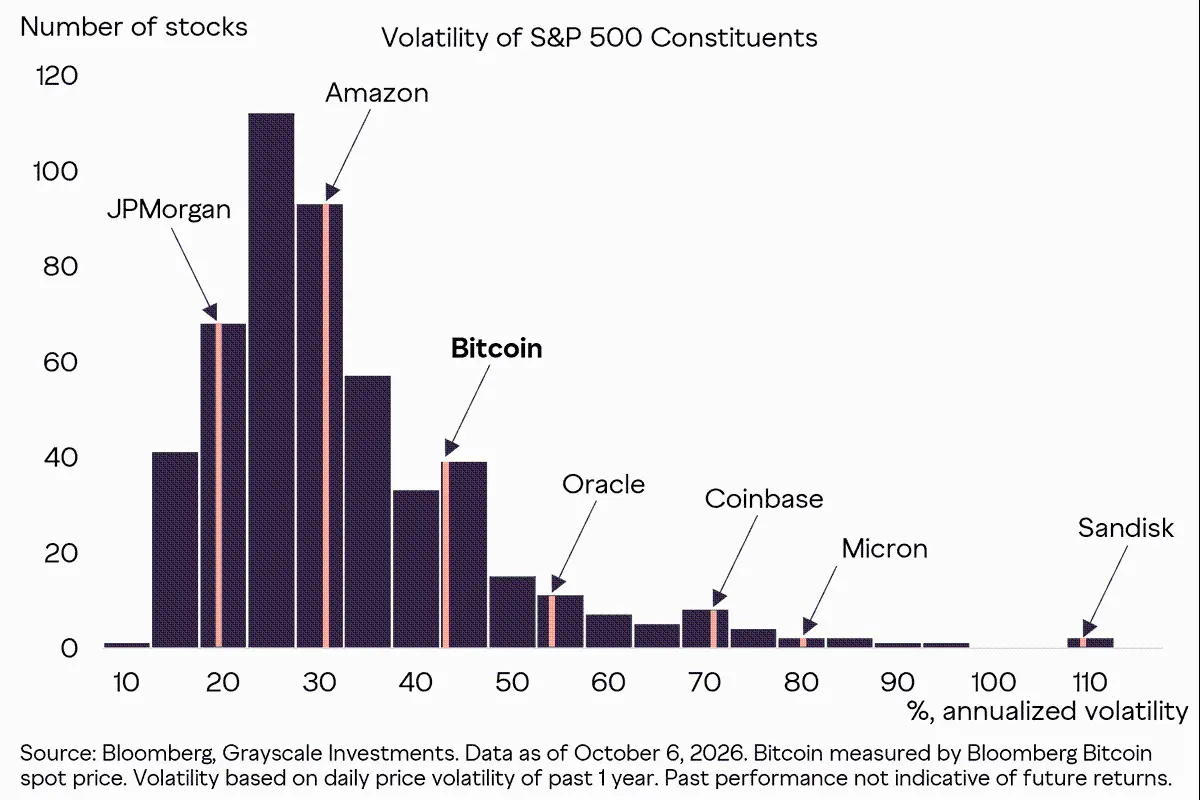
Chart 2: Bitcoin's Volatility Falls Within the Range of Large-Cap Stocks
Comparing Bitcoin to individual large-cap stocks does not lead to the conclusion that it is a low-risk asset; it merely places its volatility in a more familiar context. The more important question is what lies beneath this surface volatility. Standard deviation alone cannot reflect whether volatility comes from upward or downward movements, how frequently extreme returns occur, and whether these returns occur independently or cluster together. Therefore, understanding Bitcoin's risk requires a deeper examination of the form and temporal structure of its returns.
Beyond Surface Volatility
Compared to the S&P 500 index, Bitcoin's daily return distribution is significantly wider and exhibits thicker tail characteristics (Chart 3). Its one standard deviation range is about three times that of the former, while the extreme values contained in both tails are far more numerous than in traditional distribution forms. This creates a more severe environment for downside events, but it also brings greater positive returns and higher average daily returns over the statistical period. In other words, historically, Bitcoin's volatility reflects significant dispersion in both directions.
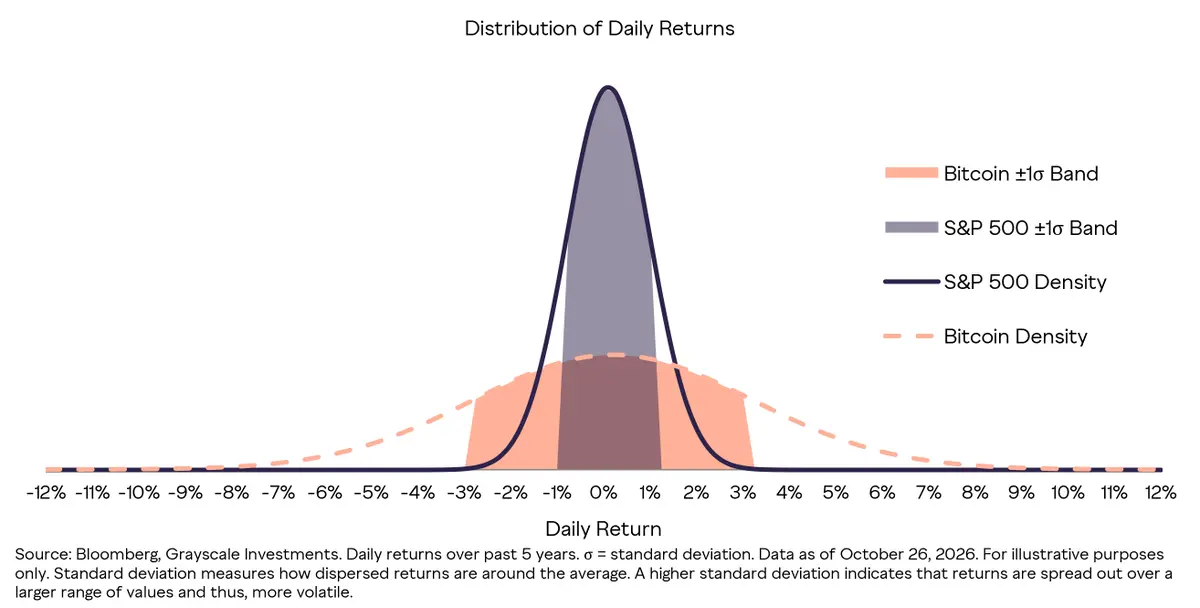
Chart 3: Bitcoin's Returns Have a Broader Distribution and More Pronounced Fat Tail Characteristics Compared to Stock Returns
The importance of fat tail characteristics lies in the fact that a very small number of trading days can determine long-term investment outcomes. Over the past three years, Bitcoin achieved an annualized return of 60%; if its best 10 days are excluded, that figure plummets to 7%; conversely, if its worst 10 days are excluded, that figure skyrockets to 197% (Chart 4). This does not imply that people can predict these days in advance, but it indicates how costly it can be to miss the rapid rebounds that often follow Bitcoin's largest declines.
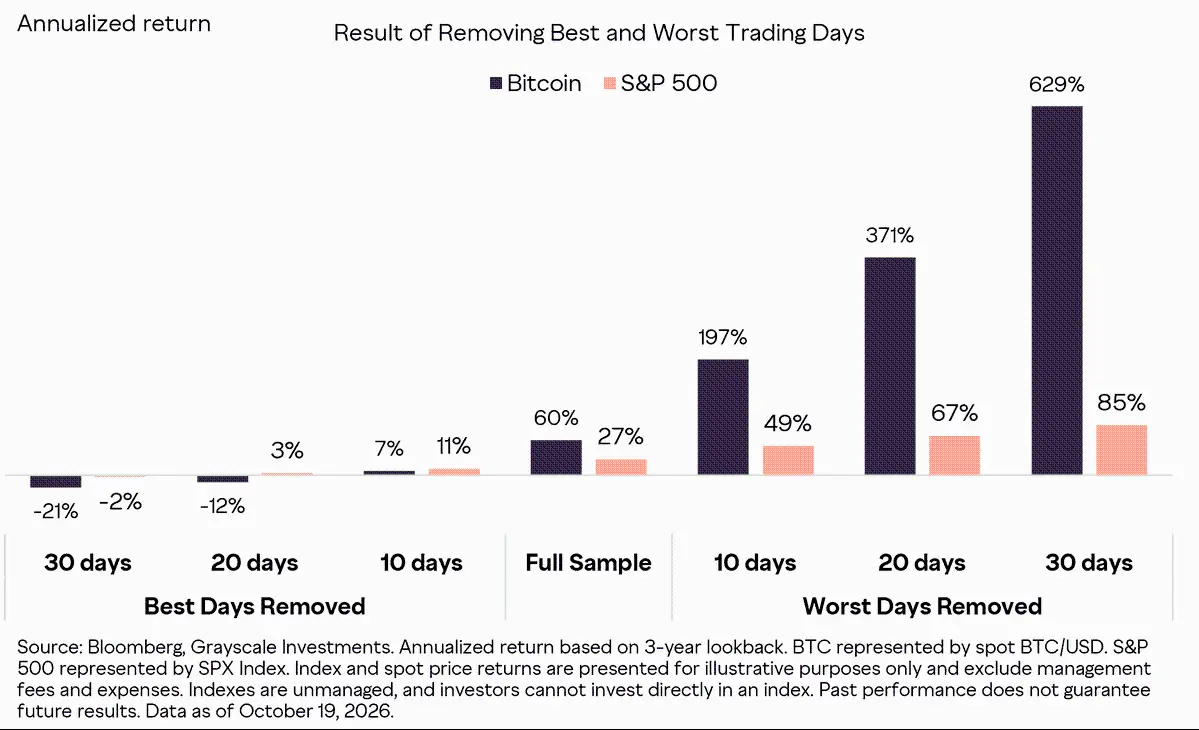
Chart 4: A Few Key Trading Days Drive Bitcoin's Compound Returns
This momentum also affects how Bitcoin's risk-adjusted returns are measured. Standard deviation and the Sharpe ratio [3] treat large upward and downward movements equally. The Sortino ratio [4] measures returns only relative to downside deviation. During periods of strong positive momentum, Bitcoin's return acceleration may outpace the growth of its downside deviation, leading to a soaring Sortino ratio that far exceeds the Sharpe ratio (Chart 5). This does not mitigate the risk of severe reversals, but it reveals why overall volatility can only provide an incomplete measurement perspective for assets with significant upside dispersion.
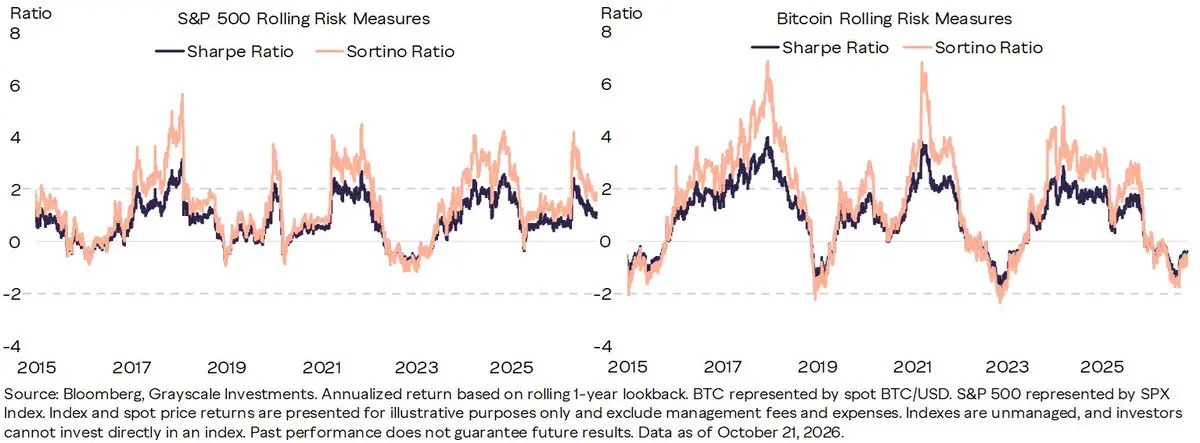
Chart 5: Bitcoin's Sortino Ratio Highlights Its Upward-Driven Volatility
In the temporal distribution of returns, the momentum effect of Bitcoin can also be observed. Historical data shows that after experiencing months of gains, the volatility-adjusted return rates are typically significantly stronger than those following months of declines, and this pattern is much more pronounced in Bitcoin than in traditional assets. In other words, Bitcoin's gains tend to have a self-reinforcing tendency. Although this pattern cannot be viewed as an independent trading signal, it helps explain why positive cycles can generate sustained upward momentum and why the Sortino ratio can surge significantly when upward momentum accelerates while downside deviation does not increase proportionately.
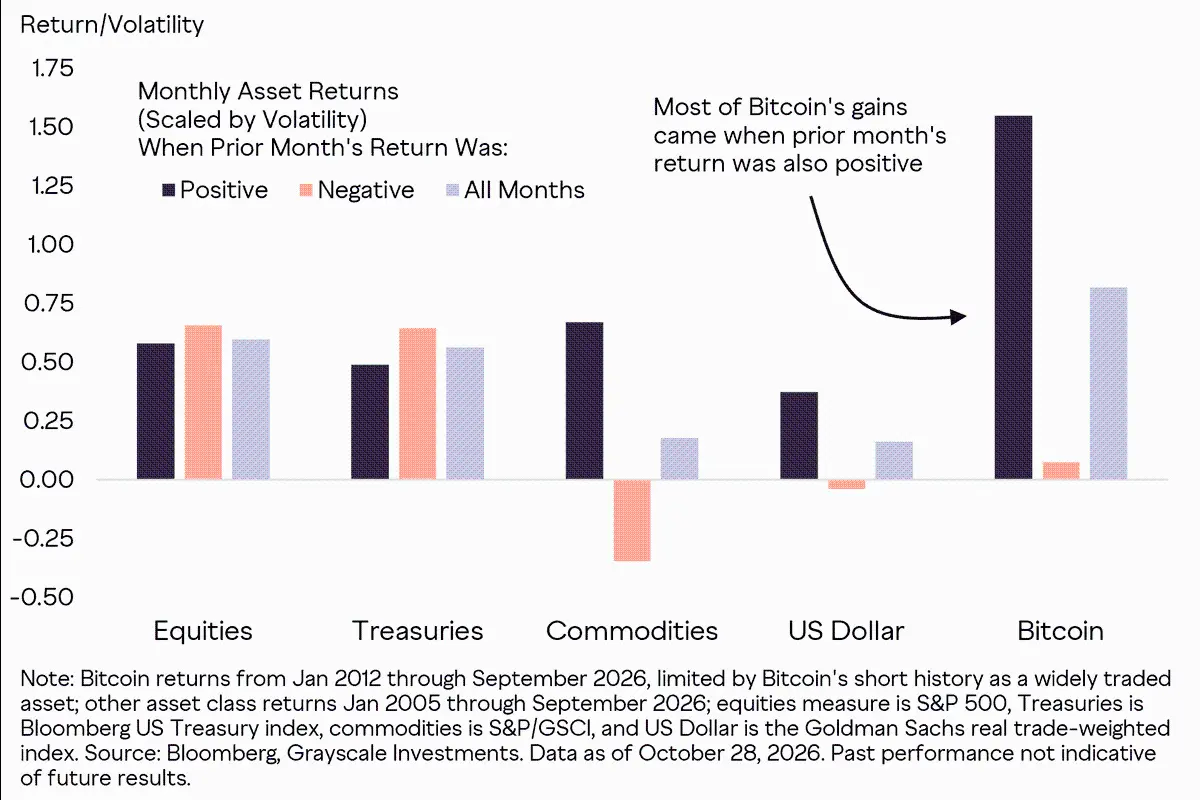
Chart 6: The historical increase in Bitcoin often builds on positive momentum
Even so, Bitcoin's strong momentum can trigger severe reversals. A sustained upward trend can quickly collapse, leading to extreme percentage-level pullbacks. Bitcoin's significant pullbacks are well-known: since 2011, this asset has experienced seven pullbacks of 50% or more. [5]
However, when the volatility levels between assets differ greatly, simply comparing absolute pullback magnitudes often lacks comparability. If standardized adjustments are made based on the market volatility at the start of each decline, Bitcoin's pullbacks appear less extreme and are more comparable to the pullbacks of stocks and bonds—what is truly eye-catching is the long and severe pullbacks that "low-risk" bonds have faced in recent years.
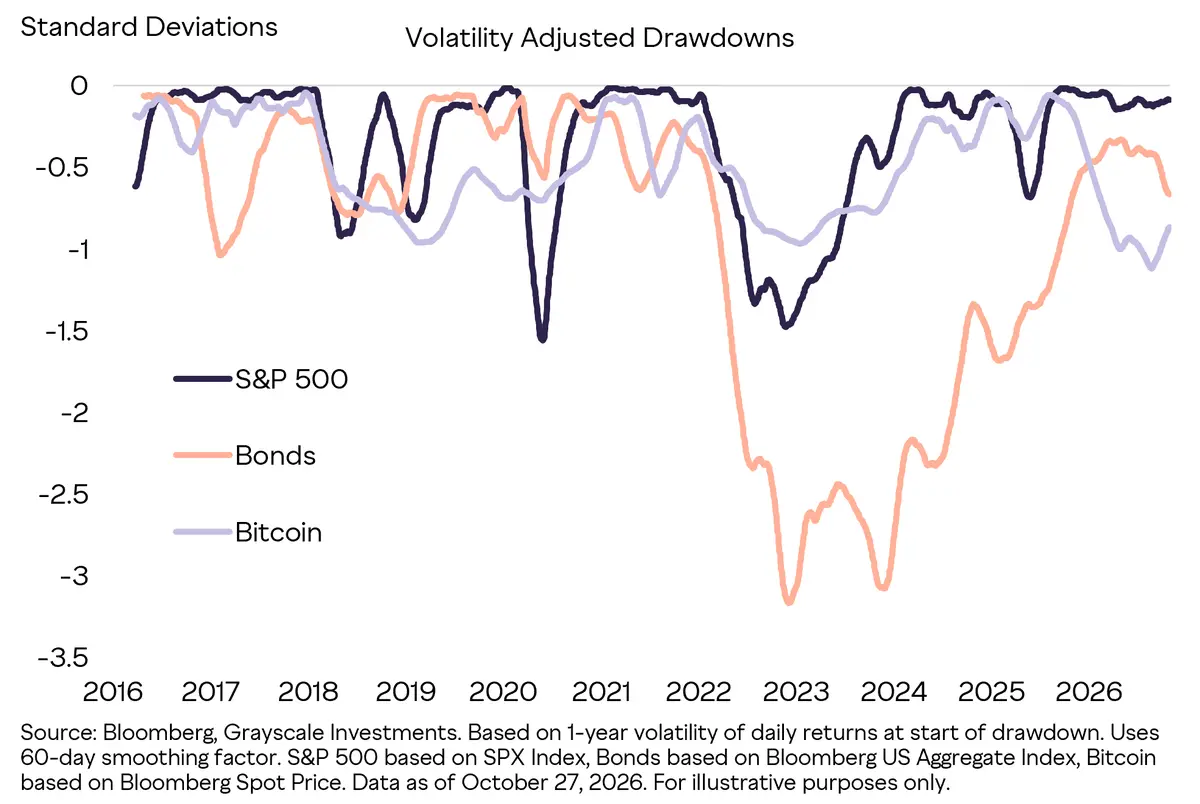
Chart 7: After adjusting for volatility, Bitcoin's pullbacks appear less extreme
Overall, these results outline a profile of an asset: its return distribution is wider, more concentrated, and exhibits more momentum-driven characteristics than what a single volatility estimate reveals. The core insight is not that Bitcoin's downside risk can be ignored, but rather that its pullbacks are closely linked to the historical upward dispersion that has driven most of its performance. For portfolio managers, viewing all volatility as equally adverse may obscure important features in the return picture of Bitcoin. The next question is whether this unique return pattern exacerbates existing risks for investors or introduces a differentiated source of returns.
Bitcoin for Portfolio Diversification
The entry point for exploring this issue is: to what extent do Bitcoin's return performance and the risk factors already borne by investors in other areas overlap? To test this overlap, we conducted a regression analysis of the returns of Bitcoin, stocks, bonds, and private markets against a set of common macro and market variables (Chart 8). These factors explain a significant proportion of the variability in traditional asset returns, but the explanatory proportion for Bitcoin is markedly lower. While a lower explanatory proportion does not guarantee diversification effects, it indicates that Bitcoin has historically not behaved as a simple repackaging of exposure to traditional markets.
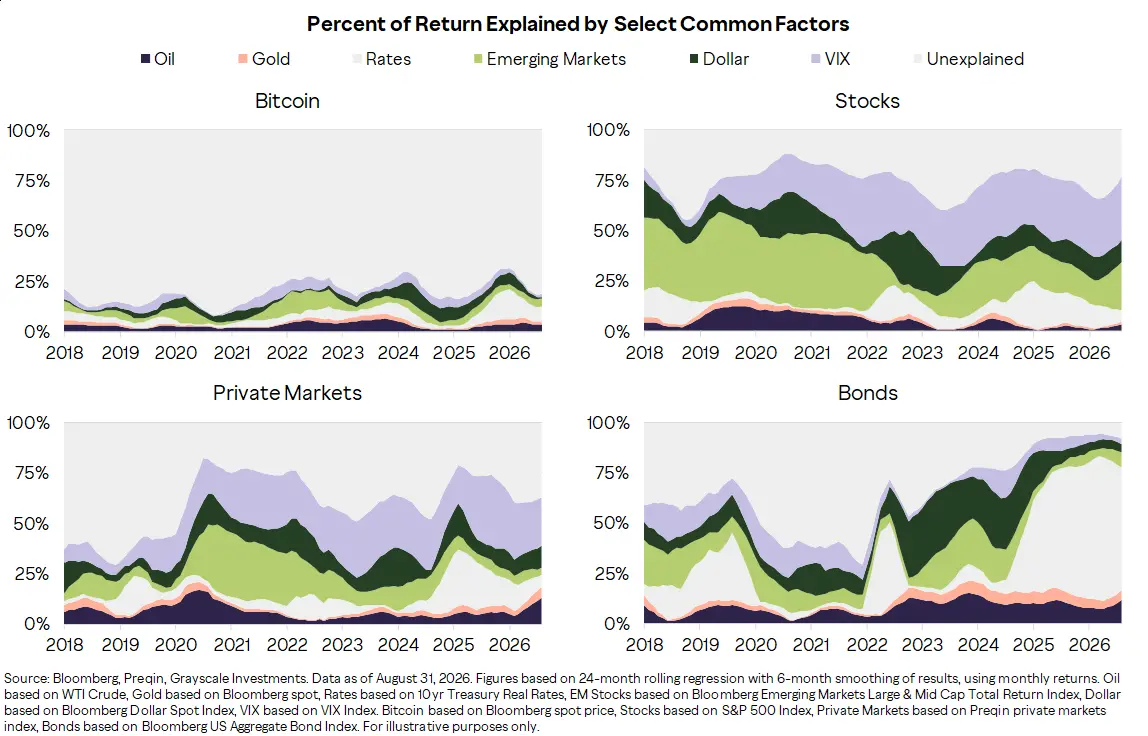
Chart 8: Traditional market factors have a lower explanatory power for Bitcoin returns
When directly comparing Bitcoin to publicly traded and private assets that constitute most institutional portfolios, this uniqueness is also evident. Historically, the correlation between Bitcoin and the broader cryptocurrency market and major private market benchmarks is lower than the correlations among these traditional benchmarks. Correlations are not static and may rise during market stress periods, but the long-term pattern indicates that compared to simply increasing exposure to stocks, credit, or illiquid risks, crypto assets introduce a differentiated source of returns.
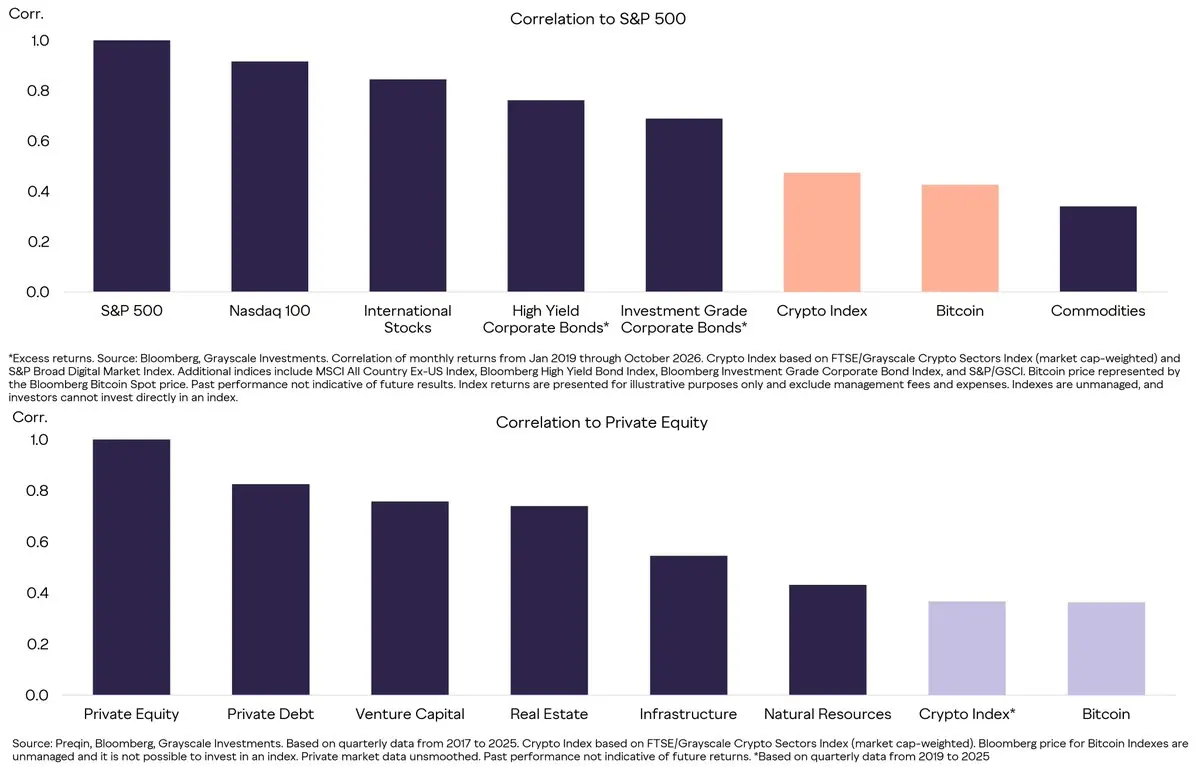
Chart 9: Crypto assets have a lower correlation with traditional assets than traditional assets have with each other
Of course, statistical differentiation only has substantive meaning when it can improve portfolio performance. The lower overlap of Bitcoin with traditional assets creates the potential for diversification, but the size of the positions determines whether this benefit can outweigh its own higher independent volatility. Therefore, we assess Bitcoin's impact on portfolios by combining forward-looking capital market assumptions and historical returns to examine whether moderate allocations can improve the expected risk-return trade-off of portfolios, rather than merely adding another source of risk.
Bitcoin's inclusion in J.P. Morgan Asset Management's 2027 Long-Term Capital Market Assumptions marks another significant milestone in its evolution as an institutional-grade asset. This investment giant, managing $50 trillion in assets, now views Bitcoin alongside mature asset classes, predicting a 10% annualized compound return and a 55% annualized volatility over the next decade. These estimates incorporate Bitcoin's potential returns—and higher risks—into a familiar portfolio construction framework. Its projected 10% annual compound return surpasses the expected returns of all other asset classes, while its expected correlation with U.S. large-cap stocks is only 33%—lower than that of international stocks, corporate bonds, and hedge funds. Assets that offer high absolute returns with low correlation to core equities are rare, making Bitcoin an extremely attractive potential portfolio diversification tool (Chart 10).
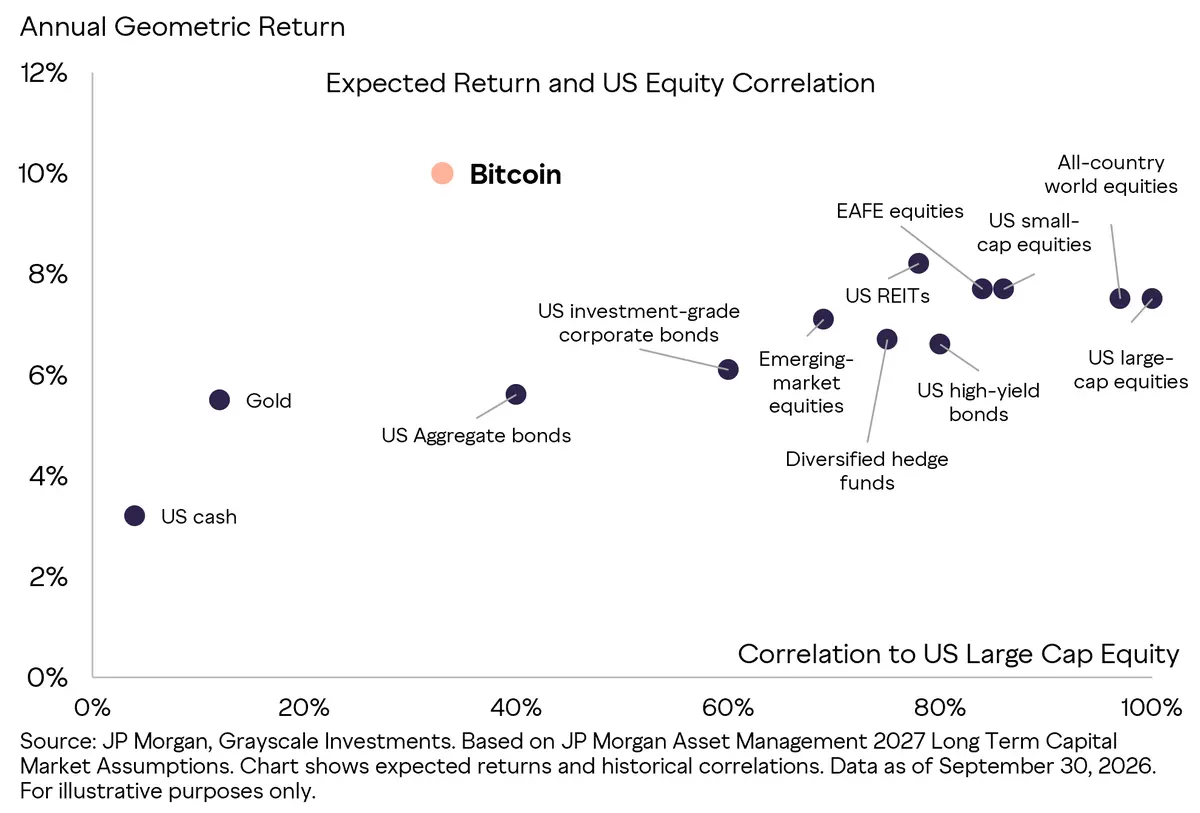
Chart 10: Capital market assumptions show Bitcoin's uniqueness in returns and correlation
Forward-looking projections rely on model assumptions, while historical analysis examines investors' actual experiences. In the sample presented, a moderate allocation to Bitcoin in representative institutional portfolios not only improved annualized returns and Sharpe ratios but also had a limited impact on volatility and maximum drawdowns. These results are consistent with factor and correlation analyses but also reflect Bitcoin's strong actual performance during the backtesting period, and it should not be viewed merely as an absolute predictive indicator for portfolio construction.
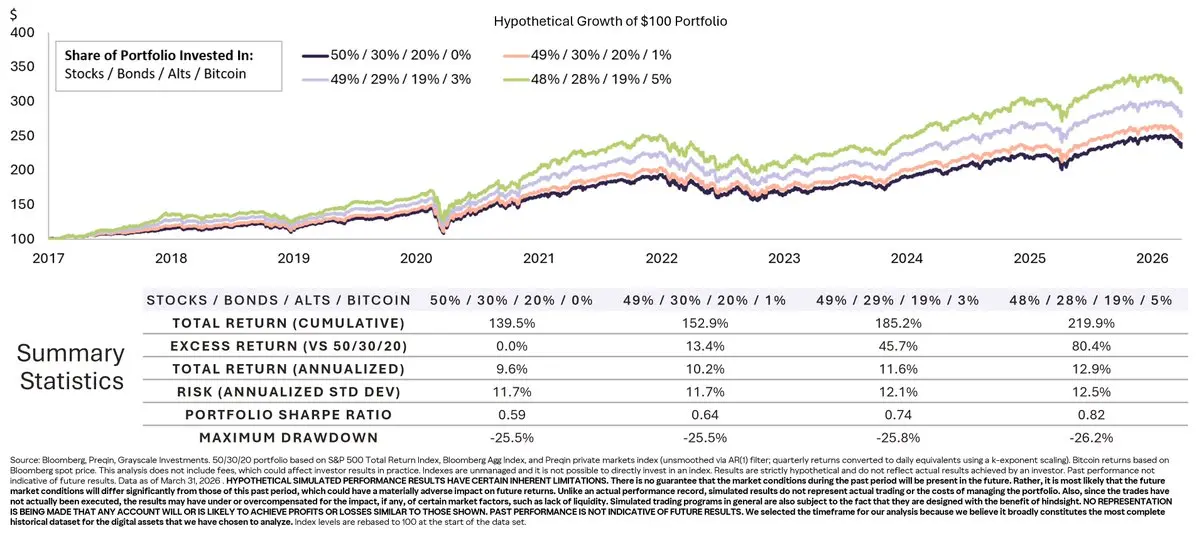
Chart 11: Moderate allocation to Bitcoin historically improved portfolio performance
These results reinforce an important distinction: Bitcoin's singular independent volatility does not proportionally translate into portfolio risk. Its differentiated return drivers allow for moderate allocations to improve historical portfolio efficiency while having a limited impact on overall volatility and drawdowns. For allocators, a more valuable question is not whether Bitcoin is highly volatile on its own, but how this volatility will affect the broader portfolio. Another important fact is that Bitcoin is just one part of an increasingly diversified landscape of crypto investment opportunities.
Diversified Allocations Beyond Bitcoin
Bitcoin occupies the vast majority of the total cryptocurrency market capitalization, and in many institutional portfolios, it represents the entirety of crypto allocation. However, the development of this asset class has far exceeded the scope of a single digital commodity (Chart 12). The current investable space has expanded to include smart contract platforms, decentralized finance (DeFi), consumer applications, artificial intelligence, and other segments, each with distinctly different economic models, user bases, and sources of demand. The core question facing asset allocators is whether these fundamental differences can translate into sufficiently differentiated return patterns from Bitcoin, thereby justifying the allocation of other digital assets alongside holding Bitcoin.
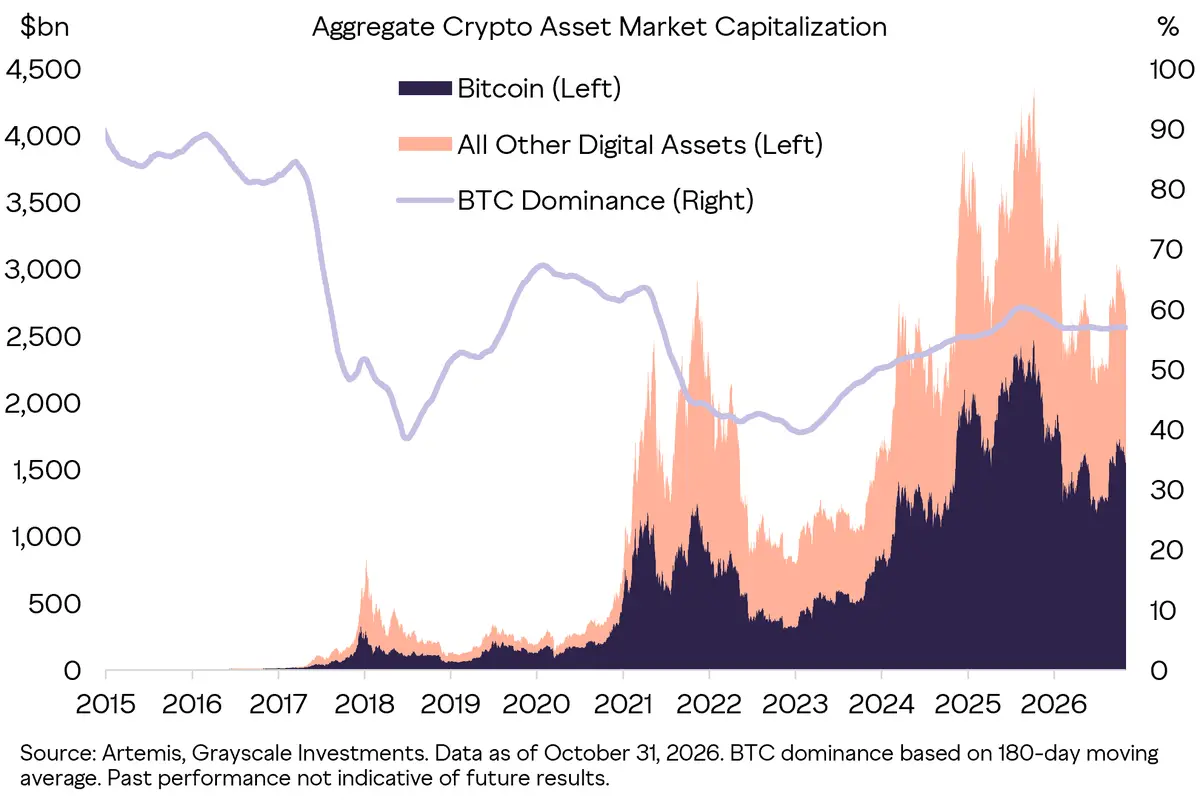
Chart 12: Bitcoin dominates in market capitalization but does not encompass all crypto investment opportunities
Market share reveals only the overall size of the field and does not reflect the specific dynamics of each component. A more effective test is to observe to what extent the returns of the sub-segments can be attributed to Bitcoin. If Bitcoin can explain nearly all the variations in returns, then the argument for diversification within crypto assets falls flat; conversely, if a significant portion of returns still belongs to characteristics unique to the segments, it indicates that investment opportunities are far richer than simply "Bitcoin Beta." Data from the past three years shows that in the FTSE Grayscale Crypto Industry Index listed below, Bitcoin can only explain about half of the return differences across segments, meaning that a considerable portion of returns is attributed to the endogenous drivers of specific segments and assets.
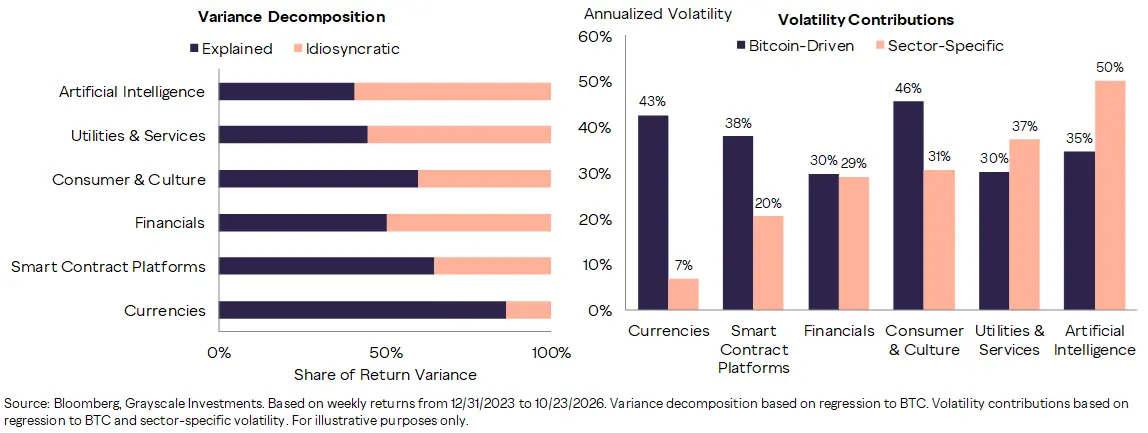
Chart 13: Bitcoin can only explain about half of the return differences in the crypto industry segments
The explanatory power of Bitcoin is merely one aspect of a diversified allocation issue. Allocators must also consider how different segments of cryptocurrency interact with each other. As new application scenarios, business models, and demand dynamics emerge across the entire asset class, the pairwise correlations between segments have retreated from previous peaks (Chart 14). This decline in correlation indicates that the maturation of the crypto market is giving rise to increasingly differentiated risk exposures, rather than merely a rehashing and replay of the same "Bitcoin Beta" trading strategy.
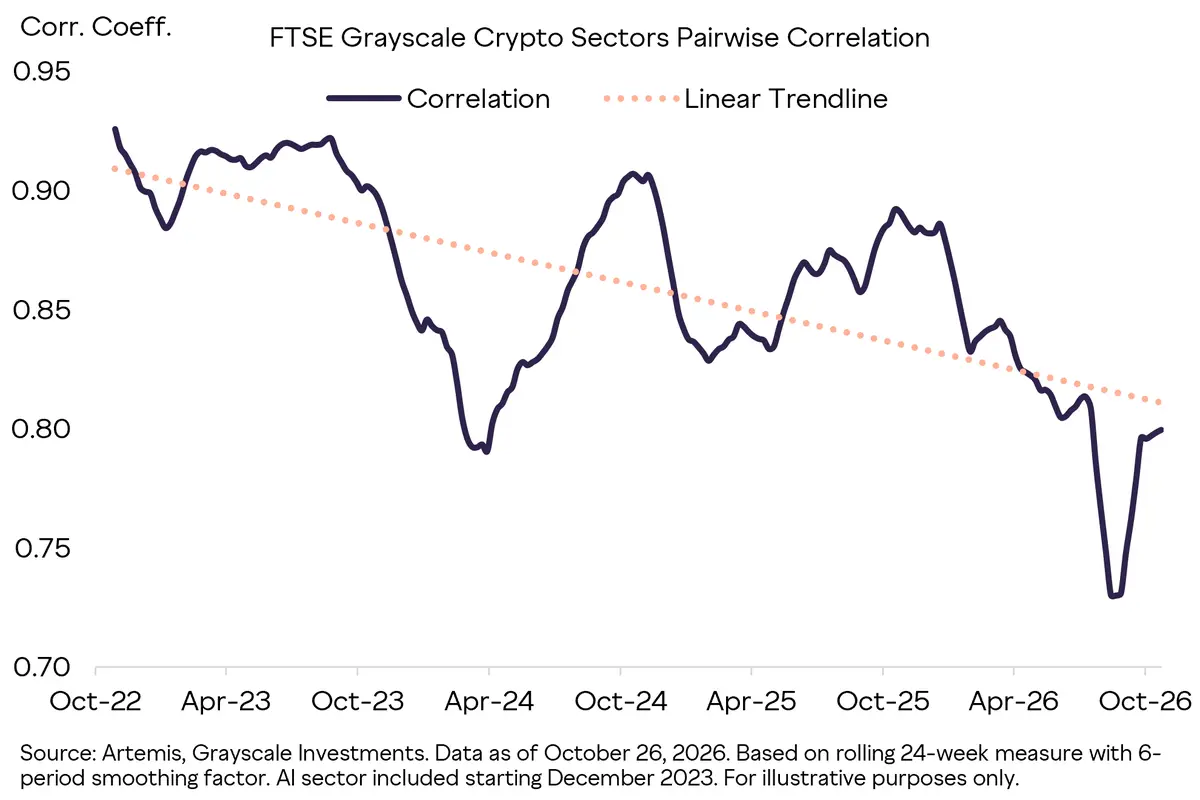
Chart 14: The correlation between different segments of the crypto industry has gradually decreased over time
This differentiation is also evident in quarterly performance. The leading position of crypto assets has sharply rotated between quarters, with Bitcoin not always being the strongest-performing asset. Different assets led in each of the shown periods, while Bitcoin's ranking mostly falls in the middle to lower range. This dispersion indicates that the crypto market is not just a single Bitcoin beta trade. Among the 10 largest non-stablecoin crypto assets, 6 different assets have led quarterly performance over the past two years; Bitcoin has not led in any quarter (Chart 15). [6] For investors who can identify high-quality projects with differentiated fundamentals, diversifying beyond Bitcoin may create opportunities to capture asset-specific alpha across different market cycles.
Chart 15: The leading position of crypto asset performance continues to rotate
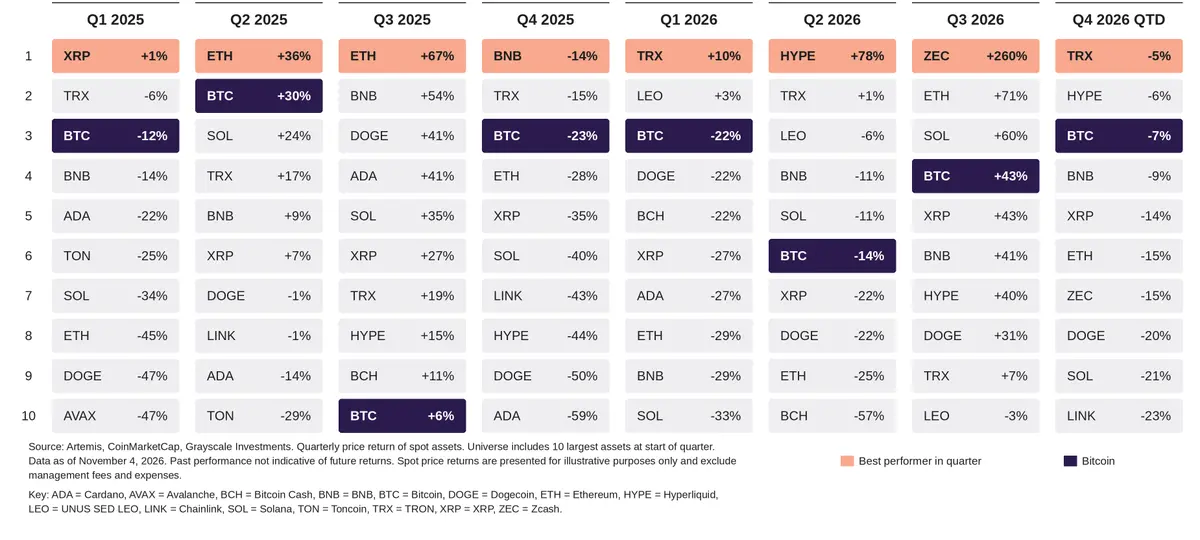
These results suggest that the broader crypto market is increasingly behaving as a set of different risk exposures rather than a single trade. Bitcoin may still be the foundation for many allocations, but the decline in segment correlation and the rotation of leading positions indicate that diversification within crypto assets can provide additional sources of portfolio opportunity. For portfolio managers, constructing a crypto asset allocation may therefore involve not only deciding how much Bitcoin to hold but also which other sources of return are worth considering alongside it.
Updated Framework for Crypto Risk
The crypto risk framework should reflect the evolution of this asset class. The realized volatility of Bitcoin has significantly decreased and is currently within the range of large-cap U.S. stocks. Its strong momentum also makes the return sequence particularly important; the experience of sustained increases and sharp reversals cannot be captured solely by headline volatility. Its returns still differ from many traditional market exposures, making moderate allocation helpful in improving portfolio efficiency as shown in this analysis. Beyond Bitcoin, the decline in segment correlation and the rotation of leading positions indicate that crypto assets are evolving into a broader set of distinct investment exposures.
This does not mean that crypto assets are low risk. It means that risk should be assessed from multiple dimensions: how much asset volatility there is, how these returns are distributed and ranked, how they interact with the rest of the portfolio, and how exposures within the asset class differ.
Chart 16: Portfolio Framework for Crypto Risk
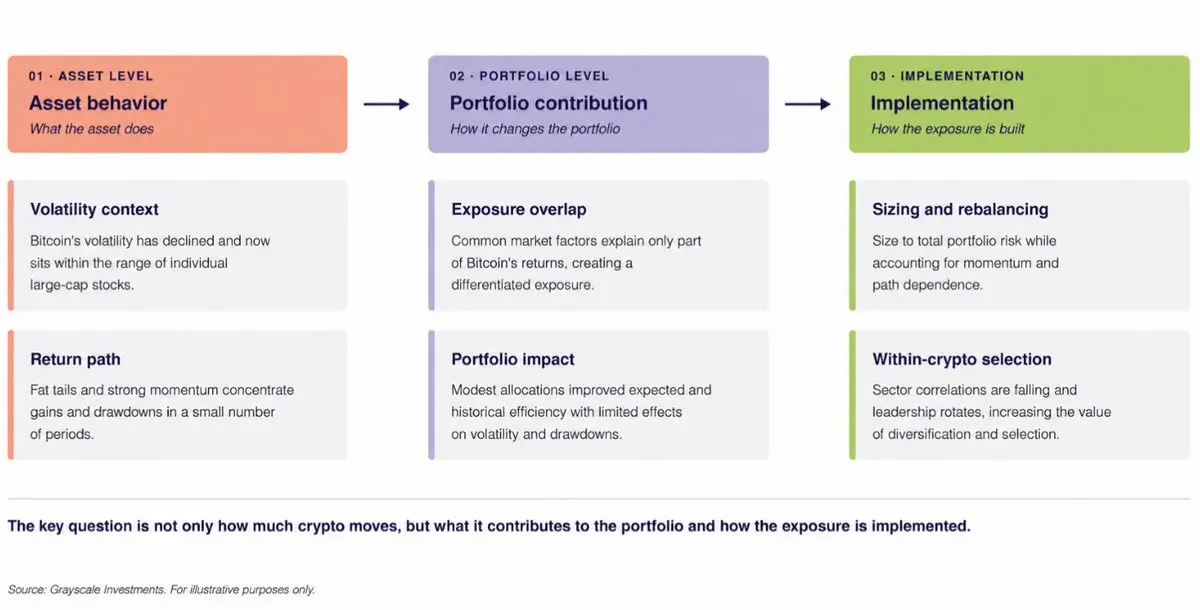
For portfolio managers, the practical implication is not to ignore volatility but to place it in the proper context. A framework that focuses solely on the magnitude of crypto asset volatility may miss where these fluctuations come from and what they contribute to the broader portfolio. A more useful question is: what risks do crypto assets add, what existing risks might they diversify, and what differentiated sources of return are emerging within the asset class?
[1] Coin Metrics. Based on a 15-year lookback period and 52-week rolling volatility. Data as of October 31, 2026. [2] Bloomberg. Data as of October 6, 2026. [3] Sharpe Ratio = (Portfolio Return - Risk-Free Rate) / Total Standard Deviation. The Sharpe Ratio measures an investment's return relative to its volatility, exceeding the risk-free rate; a higher ratio typically indicates better risk-adjusted performance. [4] Sortino Ratio = (Portfolio Return - Risk-Free Rate) / Downside Deviation. The Sortino Ratio measures an investment's return relative to its downside risk, focusing on negative returns rather than overall volatility. [5] Coin Metrics. Data as of November 3, 2026. [6] Artemis, CoinMarketCap. Excluding stablecoins. Data as of November 4, 2026.
 Risk warning Risk warning
Popular articles