The value, growth, and risks of the prediction market
 Core Viewpoint


 The prediction market is transitioning from event betting to pricing for interest rates, insurance, inventory, and computing power, increasingly resembling a new financial infrastructure. However, before it becomes a "better market," the issue of ordinary users bearing excessive risk needs to be addressed.
Author: Simon Taylor, Founder of Fintech Brainfood
Compiled by: Jiahua, ChainCatcher
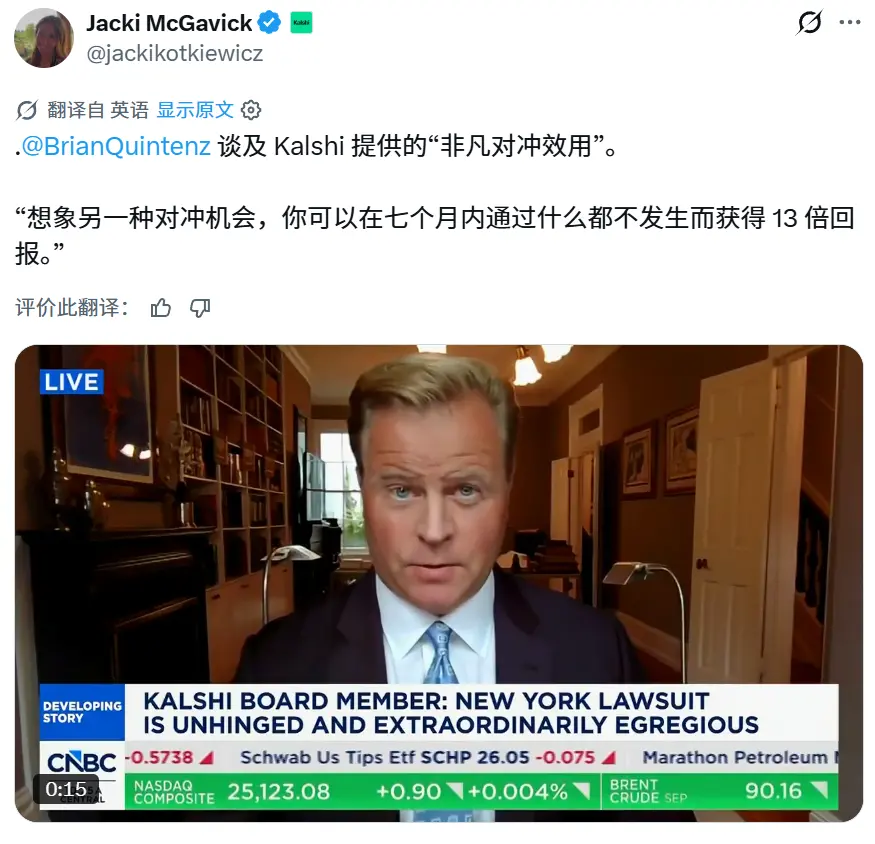
"Imagine, what other hedging opportunity could allow you to earn 13 times your investment in 7 months?" Former CFTC Commissioner and current Kalshi board member Brian Quintenz recently described a contract from Kalshi on CNBC.
This contract bets on how many times the Federal Reserve will cut interest rates by 2026. In January of this year, the price for "0 rate cuts" was only 6 cents, and it has now risen to 82 cents. If you had invested $10 in January, it would now be worth about $137; if you had made the same correct judgment using federal funds futures, which professional investors typically use to trade interest rate expectations, your profit might only be a few cents. This difference is significant for any business that relies on stable interest rates.
But predicting markets is like a Rorschach inkblot test (a psychological test that observes people's different cognitive tendencies based on how they interpret the same ambiguous inkblot). A former derivatives regulator might call a 13-fold return a hedging opportunity, a company's CFO might see it as insurance, while an average consumer with a mobile app might view it as a 13:1 bet. All three see the same contract, the same market, and the same price.
The power of prediction markets lies precisely in their simplicity. A "yes/no" contract can allow you to trade on the answer to almost any question: Will the Federal Reserve cut rates? Can the Knicks win the championship? Will Fintech Nerdcon be the best event of 2026? When the price of the "0 rate cuts" contract is 82 cents, it means the market believes there is an 82% probability of that outcome occurring, and if there are indeed no rate cuts, the contract will pay $1. Price is probability.
Event contracts are also a very good business. Robinhood disclosed in its Q2 earnings report that prediction market revenue has surpassed cryptocurrency and stock trading for the first time: event contract revenue reached $156 million, stock trading was $129 million, and cryptocurrency was $100 million; only options trading was higher, at $342 million.
One thing Robinhood excels at is capturing consumer attention with speculative products. If a speculative asset can bring users onto the platform, it becomes a very effective customer acquisition tool. One could reverse the question: if Robinhood never offered these speculative products, would it really have 28.4 million funded accounts?
There is already some evidence that a portion of users who came to Robinhood for prediction markets eventually build long-term investment portfolios. Robinhood Gold subscription users reached 4.8 million, a 39% year-over-year increase; net deposits set a record of $21.7 billion, with total assets reaching $369 billion.
Better hedging tools, more effective user acquisition, and better outcome probability data for others than polling agencies — this is the strongest defense prediction markets can make.
But this picture has three problems.
First, sports are becoming the largest category in prediction markets, directly replacing some traditional sports betting, which has triggered related taxes in various U.S. states. Kalshi and Polymarket are already facing at least 20 legal actions from state regulators, tribal entities, and individuals, with both companies counter-suing and appealing, while the CFTC is also suing several states, pushing the dispute to higher levels. Can the courts resolve these issues in the coming year? Probably not.
Second, prediction markets primarily launch contracts through a "self-certification" process with the CFTC. This system relies on the regulators' interpretation of the law, which often changes with shifts in government and regulatory bodies. Today's CFTC is very friendly to prediction markets and actively defends this model, but what if the winds change in the future?
Most importantly, prediction markets are competing for the same attention as traditional sports betting platforms. People who might have previously engaged in sports betting are now entering prediction markets, but they may not be covered by the state or federal protections that reduce consumer harm in traditional industries, and problematic betting behavior is already on the rise. Of course, platforms designated as DCMs (licensed derivatives trading markets regulated by the CFTC) still have to comply with at least 23 core principles, and new regulatory requirements are continually increasing.
If legal issues remain unresolved for a long time, if regulators may change in two years, and if consumers are not just customers but also "data inputs" for this market, then the only thing I can be sure of is that everything is filled with uncertainty.
Perhaps prediction markets should also open an event contract for their own regulatory fate?
But unfortunately, the future of prediction markets will not settle simply with one outcome like a "yes/no" contract. The future of financial markets and consumer interests may depend on how we ultimately resolve this issue.
Before rushing to judgment, we need to better understand the pros and cons of prediction markets. So, this is my attempt.
1. Sports as the Biggest Growth Engine for Prediction Markets
The growth data looks like a product that is about to explode.
In Q2 2026, prediction market trading volume reached $111 billion, surpassing the total trading volume for all of 2024 and 2025, with a year-over-year increase of 1795%.
June became the highest trading month in prediction market history, reaching $52.7 billion, primarily driven by the World Cup.
The nominal trading volume for World Cup-related prediction markets reached $17 billion.
According to Prediction Atlas, there are currently 125 active prediction market platforms, with Kalshi and Polymarket accounting for 91% of the total nominal trading volume.
In Q2, there were 23 public financings, with a total financing amount of $1.288 billion. Kalshi completed a $1.2 billion financing round, reaching a valuation of $22 billion; by the end of June, the Financial Times reported that it was negotiating a deal at a $40 billion valuation. The parent company of the New York Stock Exchange, ICE, has invested $2 billion in Polymarket, which only started charging in January of this year, and by June, its annualized revenue had already surpassed $1 billion.
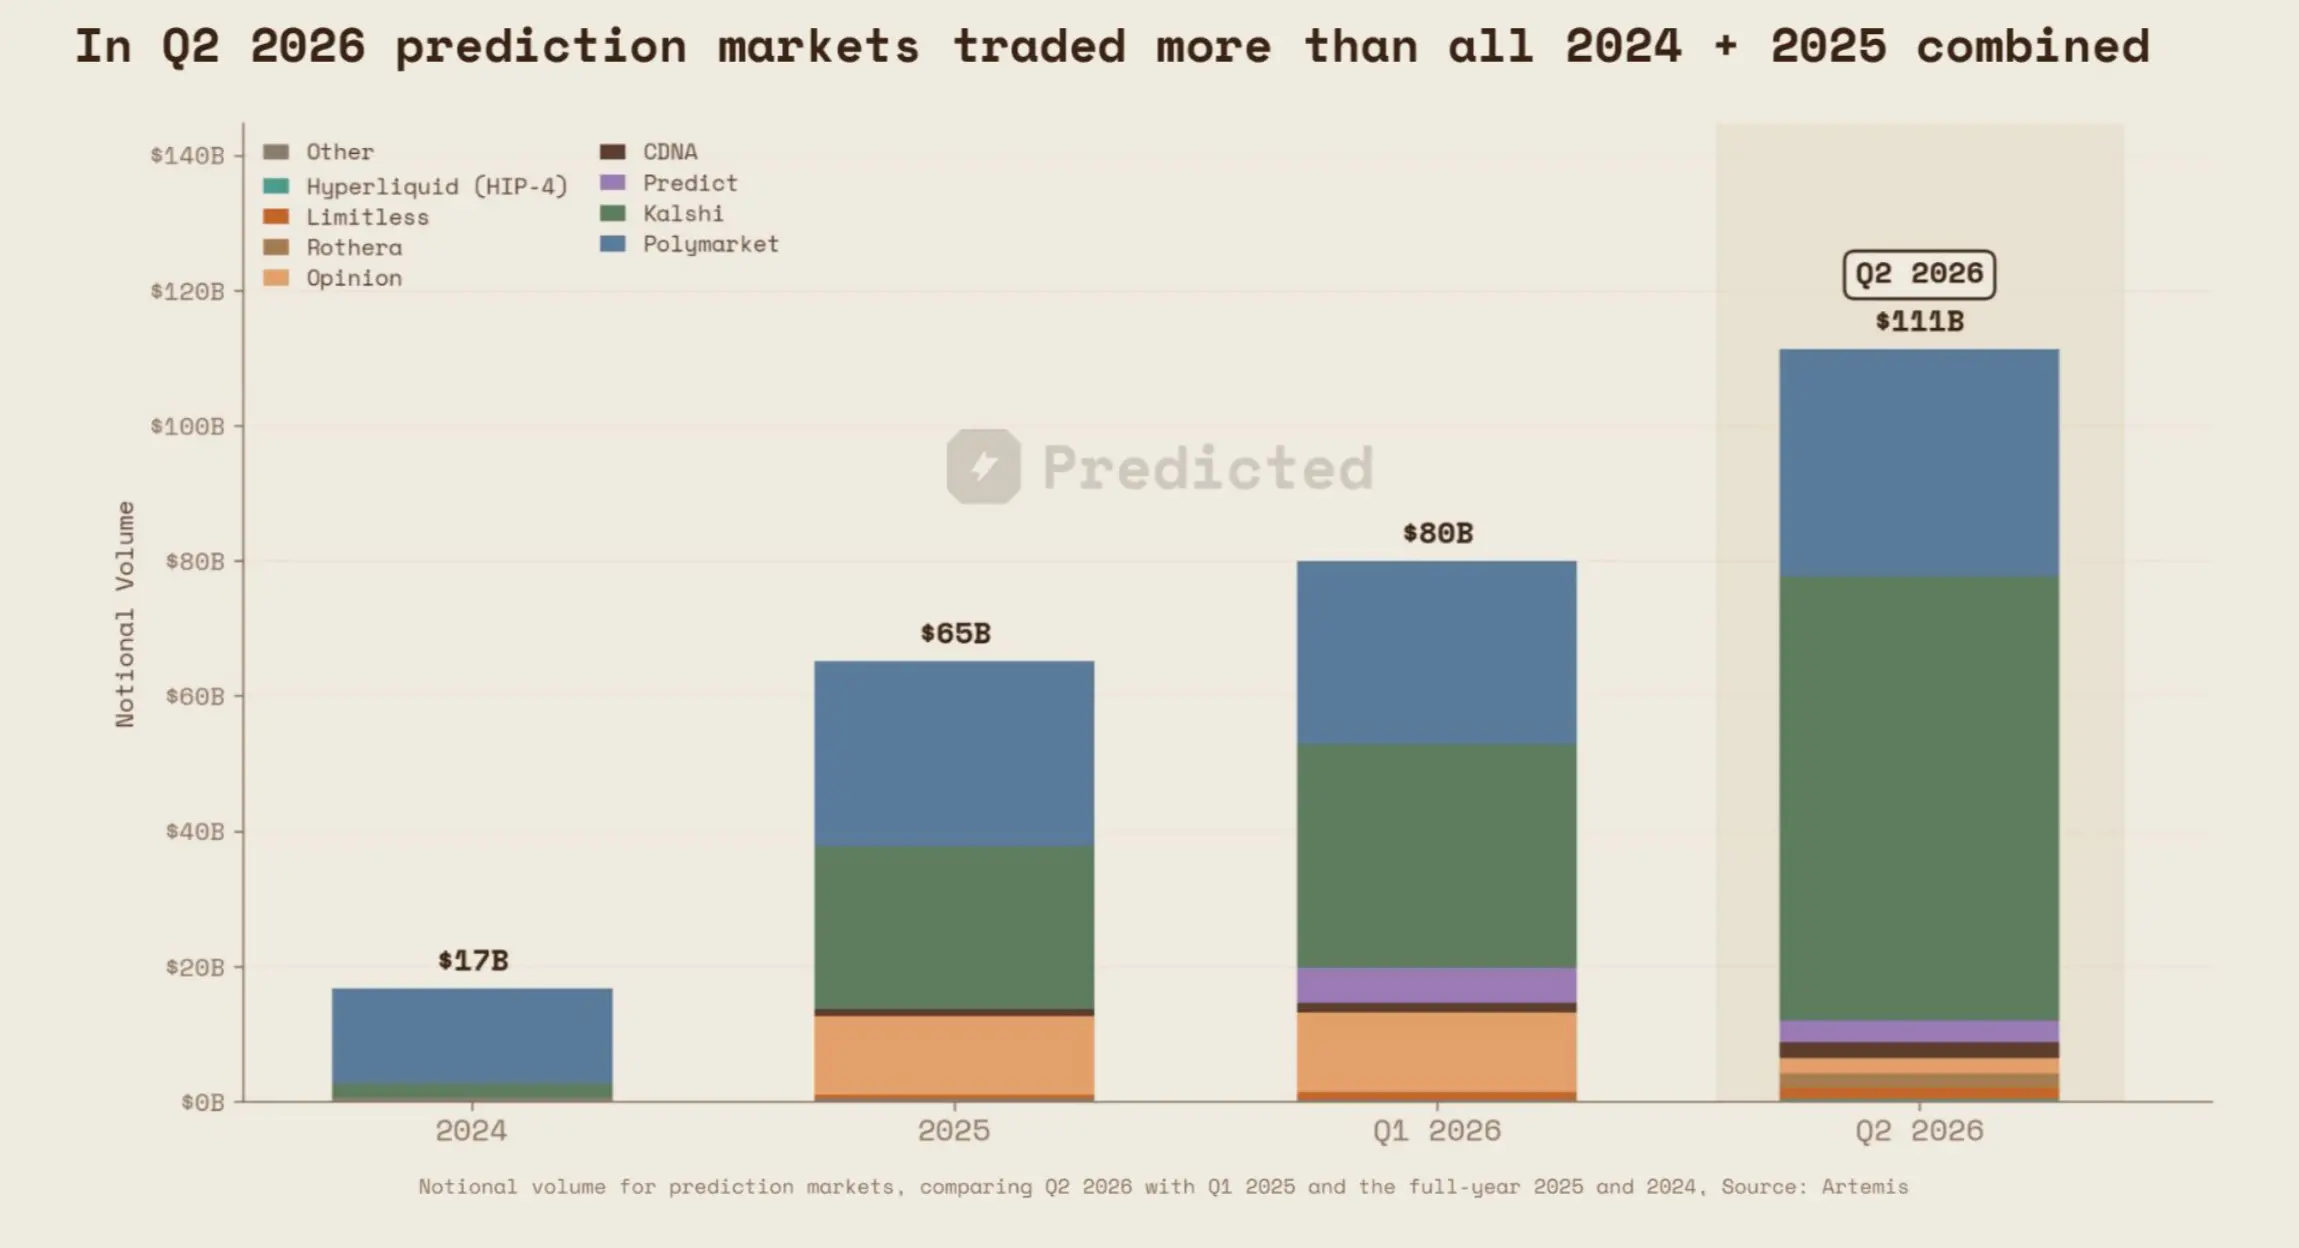
Sports are driving this round of growth. In Kalshi's June trading volume, 87% came from sports; in Robinhood's outstanding event contracts that month, 97% were related to the World Cup. The World Cup itself brought in $17 billion in trading volume, with some statistics even estimating it reached $20 billion. During the matches, according to Bloomberg citing Predicted reports, prediction markets accounted for about 27% of all sports betting activity in the U.S.
In the first half of June, Kalshi and Polymarket together accounted for 73.5% of new sports betting app downloads, while DraftKings had only 13.7% and FanDuel only 8.9%. During the World Cup, Kalshi gained 3 million new users, and at peak times, daily trading fees even exceeded $10 million.
These apps may operate differently from traditional sports betting platforms, but it is clear that they are competing for the same users. Data also supports this: according to Apptopia, during the World Cup, the daily active users of Kalshi and Polymarket surpassed those of DraftKings and FanDuel.
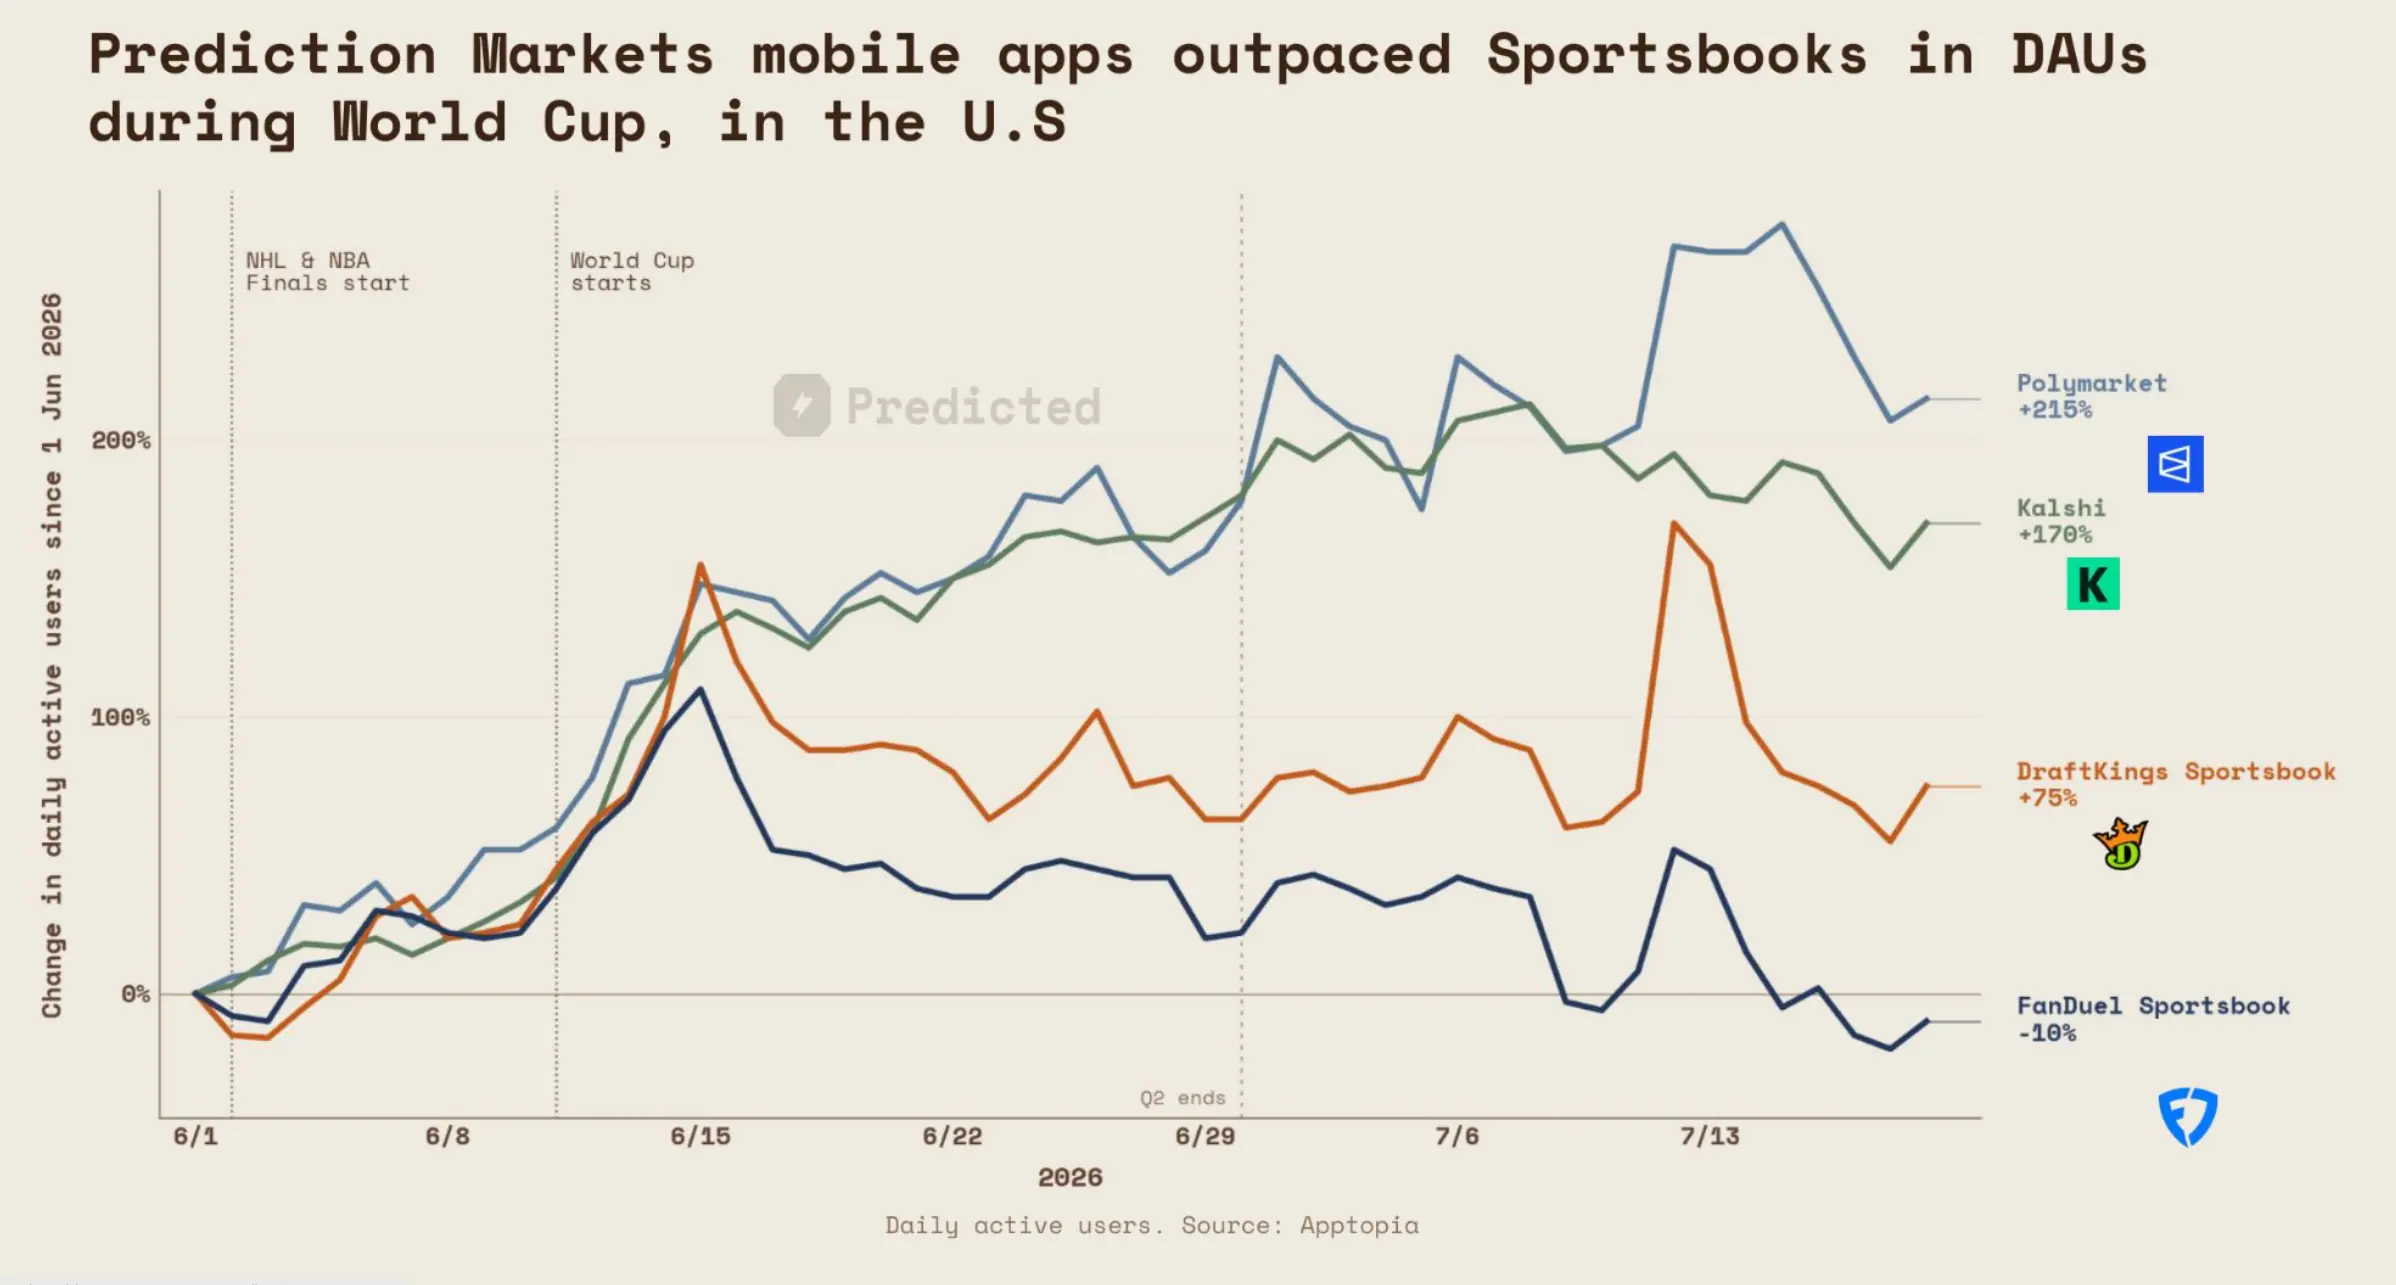
So, prediction markets are not creating a new demand out of thin air; they are directly competing for ordinary bettors and are winning. This naturally raises a question: are prediction markets just sports betting with a federal license?
Not entirely.
On traditional sports betting platforms, the platform itself is your counterparty. It sets odds to ensure its own profit, and if you win too much, it may even limit your account. When customers make money, it means the platform loses money, so these platforms need a large number of long-term, slowly losing users.
Exchanges, however, do not care who wins or loses. The market determines the price, and another trader stands on the opposite side of your bet, while the platform only needs to profit from trading activity. Betfair in the UK proved 25 years ago that the exchange model can work. What is truly new today is the regulatory license, dollar payment channels, and distribution capabilities.
But "not caring who wins" also brings another problem: the ones who usually make money are not the platforms, but professional traders and market makers.
In May 2026, The Wall Street Journal analyzed 1.6 million Polymarket accounts and found that only 0.1% of accounts took home 67% of all profits, while over 70% of accounts ultimately lost money. This 0.1% of advantaged traders are known as "sharps," who profit from the casual bets of a large number of ordinary users.
Kalshi's own data also shows that for every profitable user, there are 2.9 losing users, but co-founder Luana Lopes Lara responded that even so, people have a higher probability of making money in prediction markets than in sports betting or day trading.
So the current situation is this: prediction markets are rapidly growing thanks to ordinary bettors, while the money of ordinary users ultimately flows to professional players, and they receive less consumer protection than in similar markets.
So why can we still say that prediction markets are "better markets"?
2. The True Value of Prediction Markets Lies Beyond Predicting Outcomes
The strongest defense for prediction markets might be this.
Brian Quintenz's example regarding Federal Reserve interest rates is indeed striking, but let's not forget that he is currently sitting on Kalshi's board. So let's set him aside for now and look at other scenarios. You will find that a large number of events with real economic value can be assigned a price by prediction markets.
In the financial sector of large prediction markets, you can now trade oil prices, stock prices, Federal Reserve policies, election outcomes, inflation rates, and even "the highest-grossing movie worldwide in 2026." If your company's profits depend on any of these variables, then the logic of the earlier Federal Reserve interest rate contract applies equally.
Moreover, these odds may be some of the best estimates of outcome probabilities we currently have. Federal Reserve staff studied Kalshi's interest rate market this year and published a paper titled "Kalshi and the Rise of Macro Markets". The study found that Kalshi's predictive results can rival or even exceed those of federal funds futures and large professional prediction agencies; since 2022, it has maintained a perfect record for "the most likely outcome" before every Federal Reserve meeting.
Of course, this is just a paper from Federal Reserve staff and does not represent the official position of the Federal Reserve. The authors also caution that market prices are not completely unbiased probability estimates, but the result is still quite remarkable.
Today, if you want to trade Federal Reserve decisions, you typically have to use tools like federal funds futures or TLT (U.S. long-term Treasury ETF), but both of these products carry basis risk. Public COO Stephen Sikes explained it very directly in the Tokenized podcast:
"I don't want to trade TLT because it carries basis risk relative to the ultimate Federal Reserve decision. I just want to trade the Federal Reserve's decisions directly."
What prediction markets do is exactly this.
You can even use them to hedge some very indirect risks. A bar in New York's Upper East Side, The Jeffrey, promised to provide free drinks to customers if the Knicks won. To hedge the risk of this marketing campaign, the bar spent $5,000 to buy a "Knicks win" contract; after the Knicks actually won, it retrieved about $8,000 from the contract, just enough to cover the cost of the drinks.
This bar faced a real risk, but no insurance company was willing to design insurance specifically for such a small, binary, and clearly defined event, yet prediction markets can. Even for the most basic business risks like foreign exchange, only less than 10% of small businesses hedge, while this proportion reaches 92% among Fortune 500 companies. Kalshi has now formally submitted a corporate hedging plan to the CFTC.
Exchanges can also price things that traditional betting platforms or other markets would never touch. For example, an outcome that ultimately depends on an individual's private decision.
In July 2026, the market for "What team will LeBron James play for next" saw cumulative trading volume exceed $245 million on Kalshi and Polymarket. Traditional regulated betting platforms would not open such markets on a large scale because no company can accurately model a person's private decision to stabilize their profit margin. But exchanges do not need to do this; the market will find its own price. Of course, this time the market guessed wrong, and LeBron ultimately went to Philadelphia.
Some hedges in prediction markets even look very close to insurance. The La Liga team Osasuna paid €1.2 million in premiums to purchase about €6 million in relegation risk coverage. Relegation refers to a team dropping to a lower league after finishing last in the standings, resulting in a significant loss of television broadcasting revenue.
This coverage was designed by the insurance brokerage Howden and was reportedly executed through Kalshi, with quantitative trading firm Susquehanna as the counterparty on the other side. Ultimately, Osasuna successfully avoided relegation, and Susquehanna earned over $1 million, while the hedge purchased by the team went to zero. But this is exactly what insurance is supposed to do.
This transaction also reveals an uncomfortable truth. Osasuna was able to complete this hedge because a highly specialized institution, Susquehanna, stood on the other side; and Susquehanna was willing to come here largely because there was a significant volume of ordinary consumer trading.
The trading volume of ordinary users is the liquidity for hedgers.
This is the core contradiction of the entire issue: we seem to have found a way to build a more efficient financial market relying on less professional consumers.
E-commerce companies can also use prediction markets to hedge inventory. An e-commerce company once hedged inventory risk based on the performance of a local Latin American team in the World Cup, with the transaction completed through a broker on Polymarket, amounting to hundreds of millions of dollars. The company positioned itself on the opposite side of its own inventory risk to complete the hedge.
Dragonfly partner Rob Hadick told me on the Tokenized podcast: "The possibilities on the institutional side are almost limitless."
Even future computing power prices can be priced by prediction markets. The current demand for GPUs from AI is enormous, with Meta, Microsoft, Alphabet, and Amazon planning to invest hundreds of billions of dollars in AI capital expenditures, a significant portion of which is financed by debt. But without a reference price for future GPU earnings, lenders find it difficult to price credit based on GPUs.
So on July 14, Kalshi launched the forward curve for GPU leasing prices, the first publicly available forward price for computing power. In 2023, the rent for an H100 GPU exceeded $8 per hour; according to the Ornn index, it has now dropped to about $1.70. If your largest input cost can drop by 80% over three years and then suddenly surge, you will need a forward price curve very much.
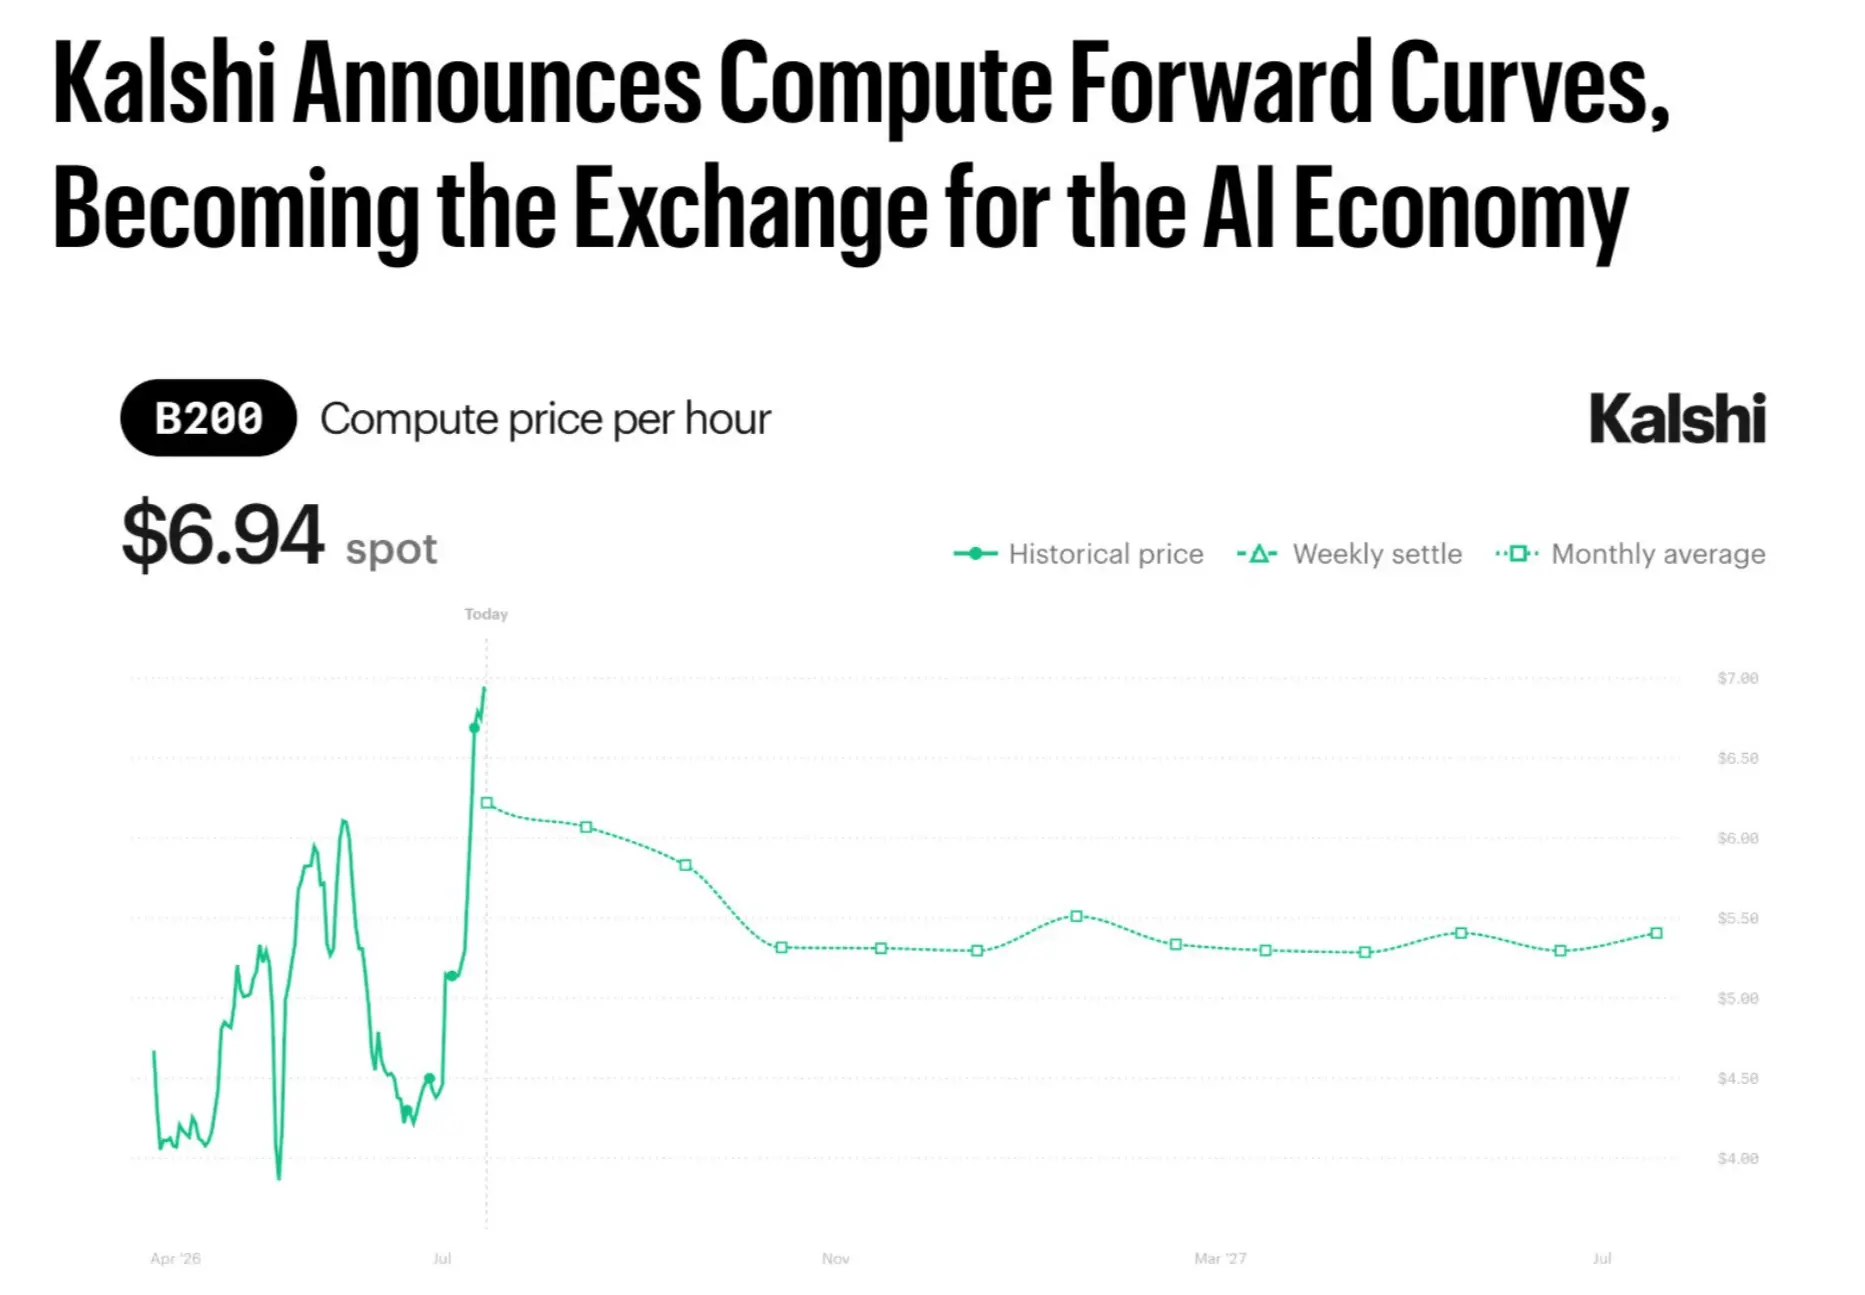
CME is developing futures for computing power, and ICE is also working with Ornn to develop a cash-settled version, but both are currently awaiting regulatory approval. Kalshi, however, has already launched because licensed exchanges can introduce event contracts through "self-certification" (where exchanges can determine that new contracts meet regulatory requirements and launch them first).
Today, lenders do not yet issue loans based on future expected prices of GPUs. But once this situation changes, prediction markets may redefine the pricing of the entire debt capital market almost unnoticed.
Of course, these applications are still in very early stages. From a platform that is more popular among sports bettors to truly becoming part of future capital markets, there is still a long way to go, and this path will inevitably be filled with legal and regulatory battles.
3. Who Regulates Prediction Markets?
The same contract, when it walks into three different buildings, can turn into three completely different things. At the Chicago Board Options Exchange (Cboe), it is a binary option regulated by the SEC; at Kalshi, it is a swap contract regulated by the CFTC; and at a state sports betting regulatory agency, it may be viewed as unlicensed sports betting.
Almost everyone is fighting over this legal ambiguity.
The CFTC's position is very clear: event contracts are derivatives. The agency is currently suing 9 states to prevent them from shutting down prediction markets and believes that event contracts should fall under the exclusive regulatory authority of the CFTC. Since Michael Selig was confirmed as CFTC Chairman at the end of last year, the agency has been strengthening its claims of jurisdiction in this area.
The CFTC has also proposed a comprehensive new framework. Under this proposal, broader sports contracts like "Will the team advance" and "Match outcomes" can exist because they have price discovery functions; however, contracts betting on player injuries, referee decisions, or specific events during the match that "violate public interest" would be prohibited.
In the past four months, the CFTC has released over 500 pages of new regulatory provisions, hoping to quickly fill the institutional void. It has recently also explicitly opposed platforms using "American betting odds" display methods, which DraftKings and FanDuel happen to do. It even raises suspicions that they might be deliberately trying to provoke regulators.
But the states completely disagree with the CFTC's logic. In these states' view, such sports event contracts are essentially a form of sports betting product.
Kalshi and Polymarket are already facing at least 20 actions from state regulators, tribal entities, and individuals. Recently, the attorneys general of 44 states jointly wrote to the CFTC, stating that the agency has no authority to regulate sports event contracts.
A few days later, the world's largest financial center also joined the fray. The New York Attorney General sued Kalshi in Manhattan state court, with potential claims reaching up to $36 billion. One of the allegations is that Kalshi allows 18 to 20-year-olds to participate in sports event trading on the platform. New York Attorney General Letitia James's position is very direct: prediction markets like Kalshi are betting platforms, "it's that simple."
Traditional exchanges and sports leagues want the regulatory boundaries to be drawn more strictly. The CME's general counsel wrote to the CFTC, arguing that its definition of "gaming contracts" constitutes "an astonishing overreach," effectively undermining state regulation of sports betting. The NFL has also urged the CFTC to tighten the rules, believing that the existing framework is insufficient to protect the integrity of the games and consumers.
Then there is another more complicated issue: insider trading.
As I wrote in "The Everywhere Insider" earlier this April: we created prediction markets to seek the truth, only to find that those who profit the most are often the ones who know the truth in advance.
In April 2026, a U.S. federal prosecutor charged a U.S. Army Special Forces sergeant with using confidential intelligence about operations in Venezuela to bet on Maduro's arrest on Polymarket, profiting about $400,000. In May, a Google engineer was charged with using internal data to place bets based on search trends, profiting $1.2 million.
In July, Kalshi's own monitoring system discovered that a White House teleprompter operator was betting on whether Trump would say certain specific words during a speech, and he had access to the speech script. Kalshi subsequently froze over $90,000 in his account. Three other political candidates reached settlements with Kalshi for betting on their own election outcomes.
Platforms have begun to take action. They are introducing professional monitoring services, requiring employees to disclose occupational information, and are indeed taking enforcement actions against violators. At least on the issue of insider trading, control mechanisms seem to be gradually functioning, and those caught will pay a high price.
So in the end, the question must still be left to the courts, and the current answers from the courts are a mess. In April of this year, the U.S. Third Circuit Court of Appeals gave Kalshi its first federal appellate victory, ruling 2-1 that sports event contracts are swap contracts and therefore should be exclusively regulated by the CFTC.
However, at the district court level, Kalshi's claims regarding the Commodity Exchange Act have already lost in New York, Maryland, Nevada, Michigan, Massachusetts, Utah, and Washington, while winning in Arizona and Tennessee, with several other cases still undecided. Minnesota has even classified trading in sports event contracts as a felony starting August 1, but a federal judge has temporarily blocked the implementation of that ban.
These cases are still continuing to appeal, and at least one is likely to reach the U.S. Supreme Court.
The motivations of the states are certainly not entirely to protect consumers. In 2025, state regulators and local governments in the U.S. received a record $18.09 billion in direct tax revenue from commercial sports betting and related industries. If the trading volume that originally belonged to sports betting shifts to federally regulated prediction exchanges, this money will not enter state government finances.
The "self-certification" mechanism allows prediction markets to quickly launch new contracts but also creates a huge gray area. In fact, Kalshi or Polymarket can launch a contract first and then have regulators review it afterward. This is why Kalshi has already been able to launch computing power forward contracts while CME and ICE are still waiting in line for approval.
Before the legal disputes between state and federal governments reach a final answer, prediction markets will likely continue to expand using this mechanism. From a risk appetite perspective, this is very similar to Uber's approach years ago.
If you operate a prediction market, the situation you face is: the courts won't resolve the issues for years; today's regulators are friendly to you, but no one knows what will happen in two years; and for every quarter you grow, your leverage in future regulatory negotiations increases. So from a rational perspective, the best strategy is, of course, to keep going, keep grabbing market share, and keep litigating.
But in this regulatory fog war, who is really on the side of consumers? Everyone claims to be, but is that really the case?
4. The Faster Growth, the More Prominent the Consumer Protection Issues
If prediction markets ultimately just create a more efficient way for those with problematic betting behaviors to lose money, then we have completely failed, because the current data on problematic betting is not good.
After the legalization of sports betting, according to researchers at the University of California, San Diego, the number of people seeking help for addiction increased by 61%. According to Bloomberg, since the beginning of this year, Kalshi users have net lost $294 million through trades similar to "parlays"; in July of this year, such contracts accounted for 36% of Kalshi's total contract trading volume. During the World Cup final, a very popular parlay combination had an implied success probability of only 2.7% at kickoff.
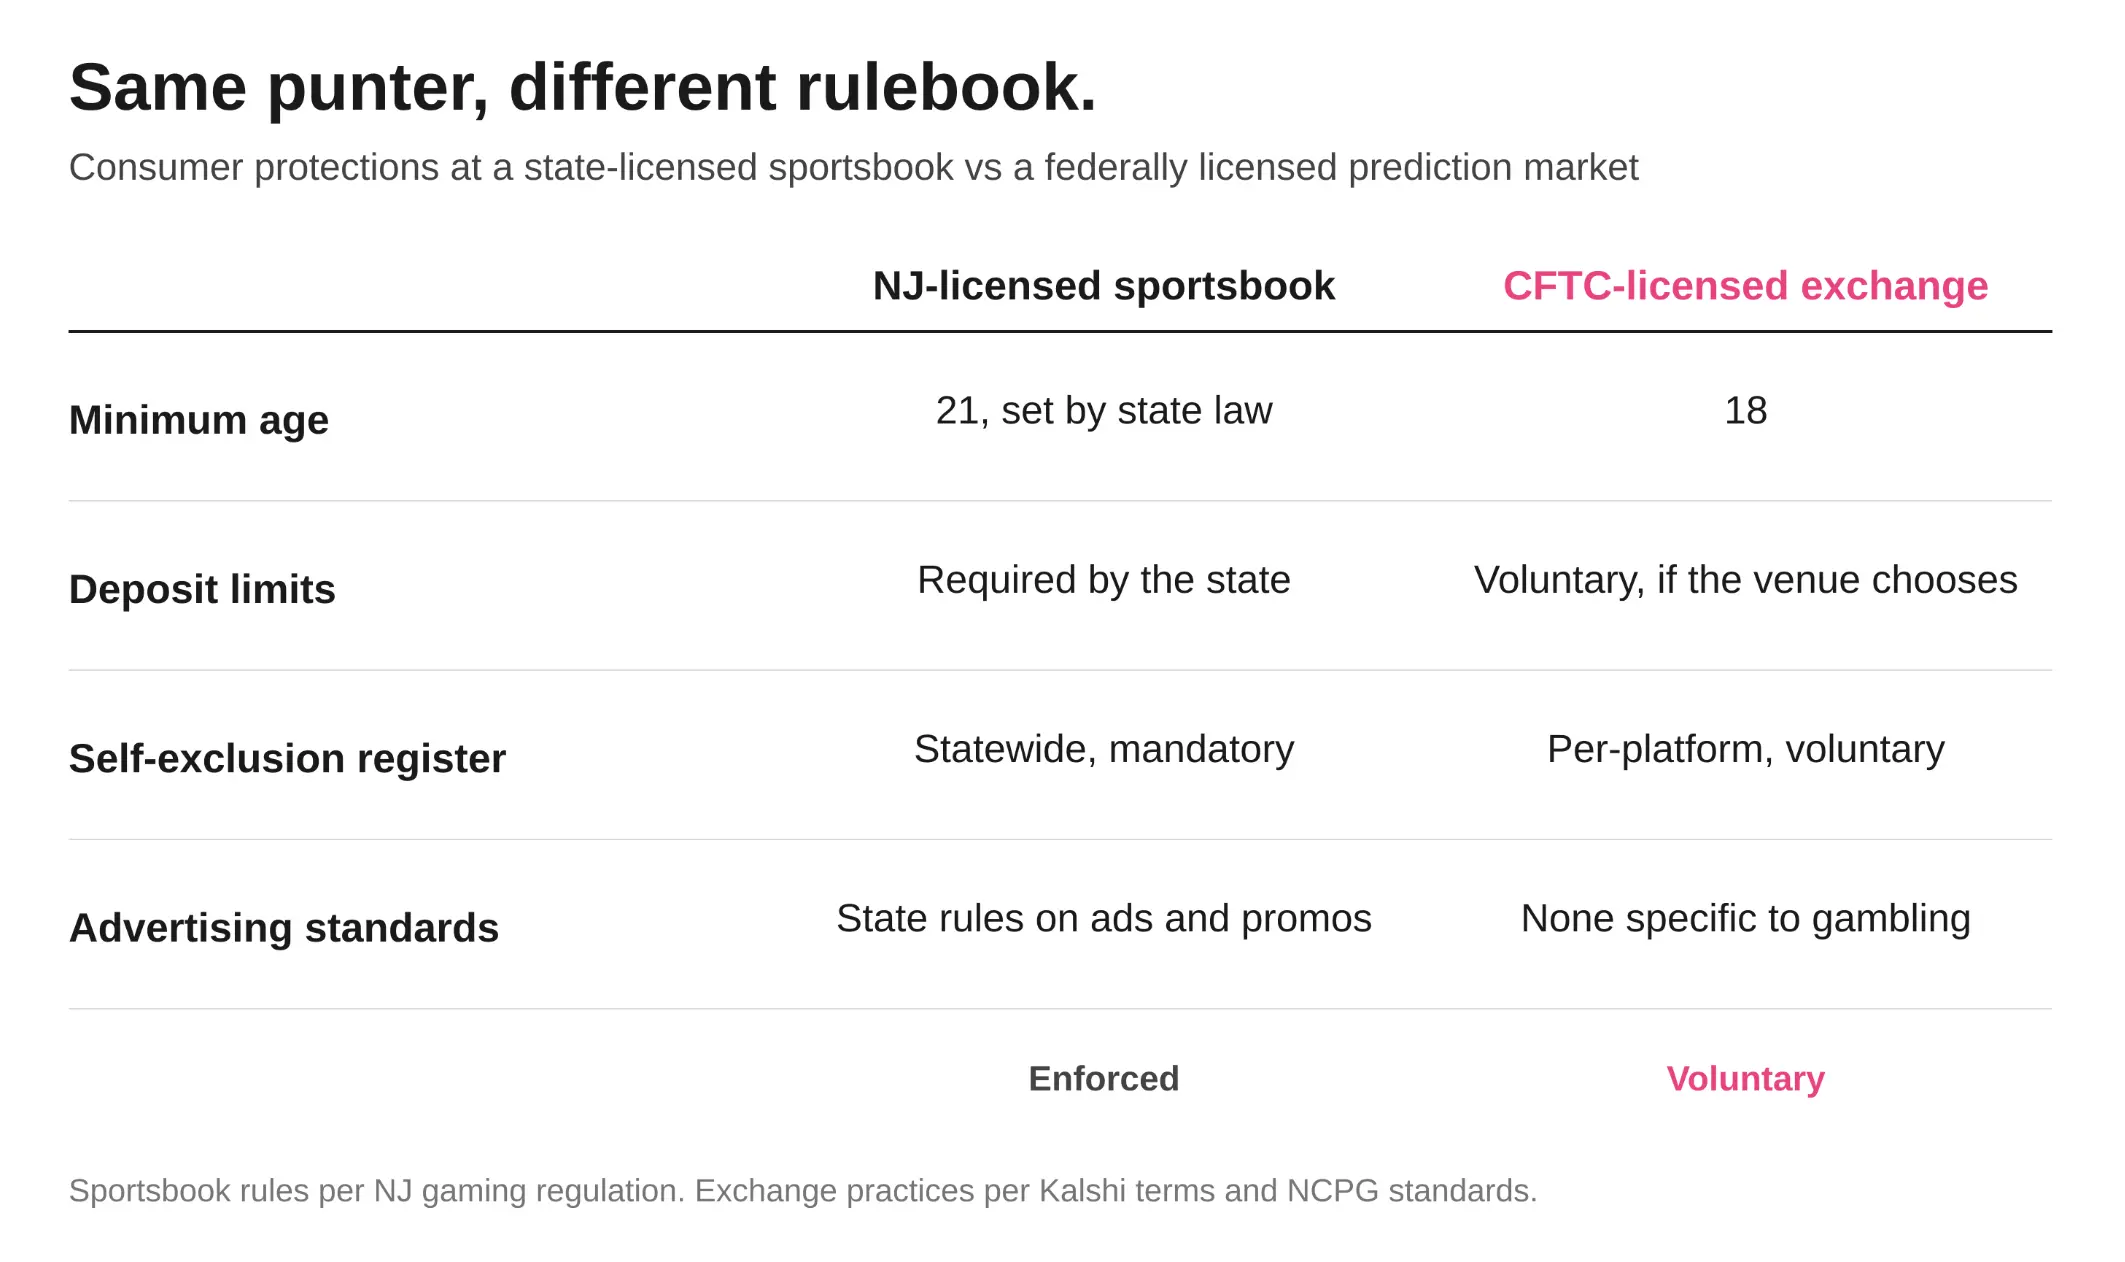
Kalshi allows users aged 18 and older to open accounts. The National Council on Problem Gambling has called for prediction platforms to raise the minimum age to 21 and prominently display relevant help information on their pages. The lawsuit in New York alleges that 18 to 20-year-olds are currently engaging in related trading on Kalshi. Kalshi itself also admits that most users on the platform ultimately lose money.
What’s more troubling is that these platforms are marketing products in almost the same way as traditional sports betting, even directly promoting parlays (combining multiple game results into one bet, where all must win to profit).
No one buys parlays for price discovery or risk hedging. A parlay is essentially a more attractively packaged high-risk betting ticket, and it is one of the highest-margin products in traditional sports betting for a reason: according to state data, for every $1 bet, ordinary single-game bettors lose an average of 6 cents, while parlay bettors lose an average of 19 cents.
There is also ubiquitous advertising. The Wall Street Journal and Politico found that Polymarket created a "clone website" almost identical to its own official site, replacing a lowercase "l" with an uppercase "I" in the URL, and then handed it to content creators in the college age group to record videos of how they "made a fortune" through simulated betting. If these trades actually occurred in the real market, more than half would actually lose money.
Fairly speaking, Kalshi has already introduced features like self-exclusion, deposit limits, and mental health support. The problem is that these are merely the platform's own product choices, not legal requirements.
A traditional sports betting platform operating in New Jersey must provide similar protective measures because the state government requires it. Users must be at least 21 years old, and advertising is explicitly restricted. But a prediction market that can operate nationwide can provide as much protection as it is willing to.
The reason is simple: the CFTC's regulatory rules were originally written for wheat farmers and the swap trading sector; they were not written for ordinary users who are still on their phones betting on the World Cup at 2 a.m.
Public's COO Stephen Sikes told me that they fully agree with the logic that "prediction markets are better markets." Public is also preparing to launch prediction markets, but they will not touch sports:
"High-risk betting should not appear in investment accounts; we will not do those products."
I greatly respect this decision, but I also know what this choice costs. Speculative trading products like cryptocurrencies and now prediction markets are at the top of the customer acquisition funnel for companies like Robinhood. Robinhood has 28.4 million funded accounts, while Public recently disclosed membership numbers exceeding 3 million, about one-tenth of Robinhood's.
Many users come to the platform for speculation, but some will eventually stay and start using more long-term investment products.
The question then becomes: if a company chooses to "do the right thing," it means it must give up the strongest growth engine to competitors that are unwilling to self-restrain; how many boards will truly choose correctly?
It is hard to expect these companies to voluntarily constrain themselves. For them, the most rational business choice remains to keep pushing forward.
And while everyone is fighting, it is often the ordinary people who end up losing.
5. How to Make Prediction Markets Better Markets?
Prediction markets are indeed better markets, but they have not yet provided better consumer protection.
I do not believe the solution is to ban prediction markets. The data value here is too great, and the real hedging uses are too numerous; an outright ban would only drive ordinary users overseas to platforms with weaker consumer protections.
But I believe at least four things can be done:
Integrate protection mechanisms directly into the market. Set cooling-off periods; establish position limits based on verified income levels; conduct affordability assessments before users make large trades; reward prediction quality rather than betting volume. I proposed similar suggestions last October; these measures will not destroy the market. The gaming industry understood long ago that "friction" in products can sometimes become part of the function. Of course, the problem is that once you start adding these consumer protections, a so-called "market" will increasingly resemble a betting product, but that is still a positive step.
Align risk warnings with the actual behavior of products. If the National Council on Problem Gambling believes the minimum age should be 21 and that help information should be displayed on the page, then at least for sports and parlay products, risk disclosures, age restrictions, and advertising standards should resemble those of sports betting platforms rather than brokerage accounts. Also, can we stop the crazy promotion of parlay ads? At the very least, more risk disclosures should be added.
Establish a pathway from bettors to investment portfolios. Robinhood actually already has all the necessary products: Gold has 4.8 million subscribers, it offers retirement account subsidies, and net deposits have set new records. Since the platform can attract users with speculation, the same machine can theoretically guide them gradually towards savings and long-term investments. There is already evidence that some prediction market users will eventually build long-term investment portfolios; the evidence is just currently thin. So let's thicken the evidence, measure it, make the relevant data public, and then include it in financial reports alongside parlay revenue.
Separate sports event contracts and provide accompanying consumer protections. There is indeed a real hedging demand in the sports field, but this demand is actually very niche. The vast majority of sports event contracts are essentially competing with traditional sports betting products. So why not impose a separate tax on sports-related activities and establish unified position limits and consumer protections, rather than continuing to rely entirely on voluntary compliance by platforms?
If you think "turning speculative impulses into financial health" sounds overly naive, look at what the UK did 70 years ago. They not only did it but did so consciously on a national scale.
6. Integrate Lottery Mechanisms into Savings Accounts
In April 1956, the UK faced two problems: inflation and insufficient savings.
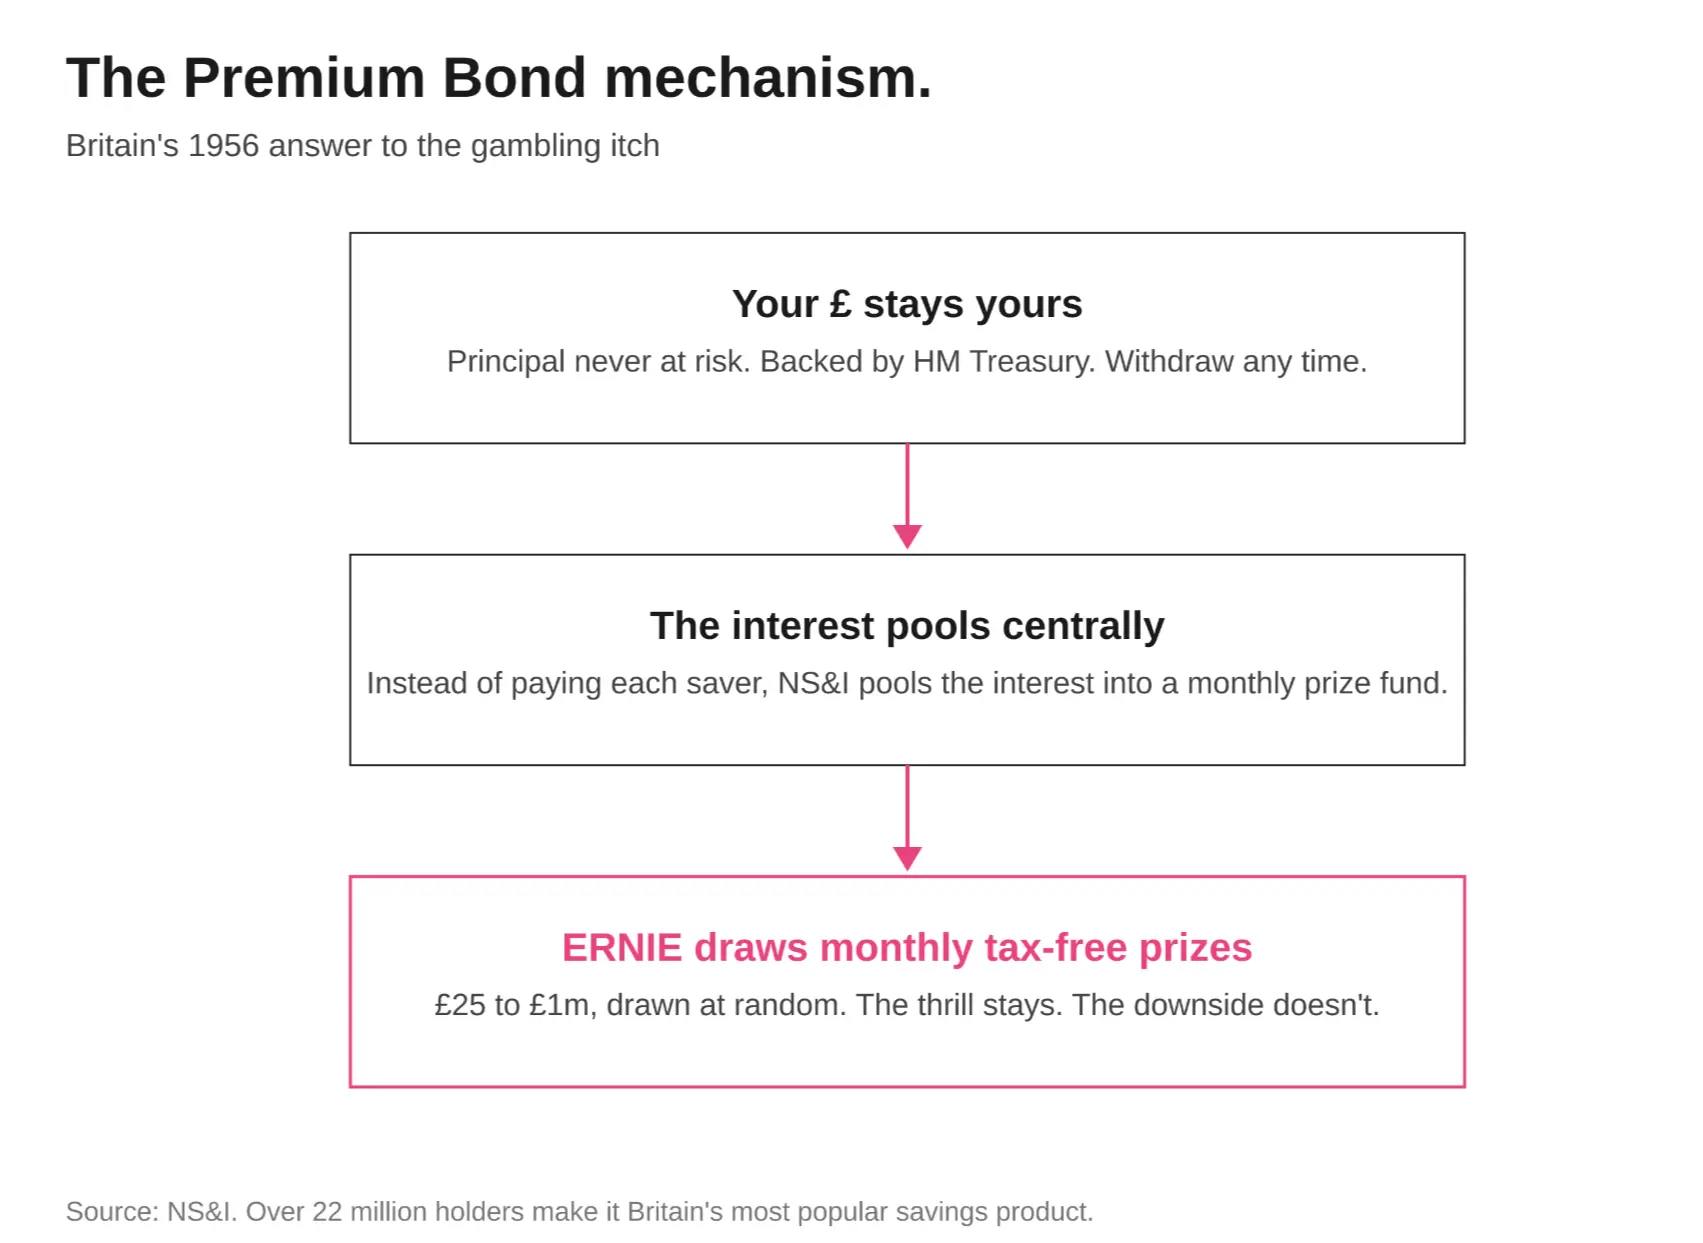
At that time, Chancellor Harold Macmillan wanted to absorb more funds from the circulation system, but simply raising interest rates was not enough to attract ordinary people to save. So he announced the introduction of Premium Bonds on budget day, which are "prize bonds."
Your principal does not bear risk, but the government no longer pays you fixed interest; instead, it pools everyone's interest and distributes tax-free prizes monthly through a lottery. The lottery is conducted by a machine named ERNIE, designed by an engineer who had participated in the Bletchley Park codebreaking efforts.
The opposition at the time derided it as a "dirty lottery." That phrasing was indeed brilliant, but the public did not care at all. On the first day of the product's launch, the British bought £5 million worth of prize bonds.
Seventy years later, Premium Bonds have become the UK's most popular savings product, with over 22 million holders. Today, a monthly draw distributes about £447 million, equivalent to approximately $590 million in tax-free prizes.
If we are destined to live in an era where speculative activities are becoming increasingly common, then at least we can find ways to ensure that this impulse does not ruin people's lives.
The U.S. actually legalized a similar mechanism back in 2014, known as "prize-linked savings," but almost no one has really scaled it up. In a year when inflation in the U.S. reached 4.2%, and almost every household felt the pressure of rising prices, converting speculative desires into savings is not a nostalgic old idea; the solution has always been there.
The event contract mentioned at the beginning that could earn 13 times is essentially pricing the same issue in real-time: inflation. Quintenz's so-called "hedging opportunity" is observing the very number that Macmillan desperately sought to address in 1956.
A Disappointed Old Father of Prediction Markets
I always find it hard to resist looking at the potential of something.
The crypto industry is slowly maturing, stablecoins have emerged, and tokenization has appeared. But now, I have another gifted yet headache-inducing problem child: prediction markets.
In my entire career, including digital assets, I have never seen a market product with as much potential as prediction markets. But now, the deadlock between U.S. states, the CFTC, and prediction market platforms has not resolved the issues we truly care about: consumer protection.
Last October, I wrote that we probably have 18 to 24 months to establish sufficient protective mechanisms. Otherwise, once a rebound occurs, regulators may take overly harsh measures, ultimately destroying the truly valuable parts of prediction markets.
Now, 10 months have passed. New York State has proposed a lawsuit seeking up to $36 billion, and the attorneys general of 44 states want to overturn the CFTC's regulatory logic. The rebound has come sooner than I imagined, and the U.S. midterm elections have not even begun.
Prediction markets are better markets, but for the vast majority of ordinary people, they are not currently friendlier than other high-risk betting products.
I truly believe this will eventually change.
Those companies that can survive and grow today while genuinely pushing their products towards healthier directions are actually preparing for the next era. That era may not arrive until something truly erupts, and the courts finally make a definitive ruling.
I just hope that exchanges, state governments, and regulatory agencies can wake up sooner and decide to do better.
After all, tomorrow is a new day.
 Risk warning



Popular articles