








Blockchain Capital Investor: Why is the power trading platform a false proposition?
 Core Viewpoint


 The article points out that GPUs are not in a complete shortage; fluctuations in training and inference have left a large amount of computing power idle, but a deep computing power spot market has yet to be established. The core obstacle is that large clusters rely on take-or-pay contracts for financing, where lenders underwrite tenant credit rather than the GPUs themselves. After resale, the original tenant still bears the risk of default, making it difficult to form an anonymous order book. To allow contracts to circulate freely, lenders must trust the assets and rely on forward prices and the buyer's market, but this is also a prerequisite for a deep spot market.
Author: Jonah Burian, Investor at Blockchain Capital
Compiled by: Gu Yu, ChainCatcher
Large-scale cloud vendors and labs may be pushing startups out of the most critical input factor for AI: computing power. This has sparked extensive discussions about establishing a computing power exchange—a market where GPU hours can be traded like oil. Although several companies are working in this direction, there is still a lack of a deep and highly liquid computing power market. In this article, we will explain why establishing a liquidity-rich computing power exchange is far more complex than it seems. We will show how the structure of the GPU credit market hinders the formation of a spot market and explore potential solutions at the end.
Part One: The Problem
Imagine you are an AI lab looking to acquire 100,000 GPUs to train the next large model. If you go to procure them today, you will find almost no available capacity. Nearly all cloud resources have been booked out years in advance.
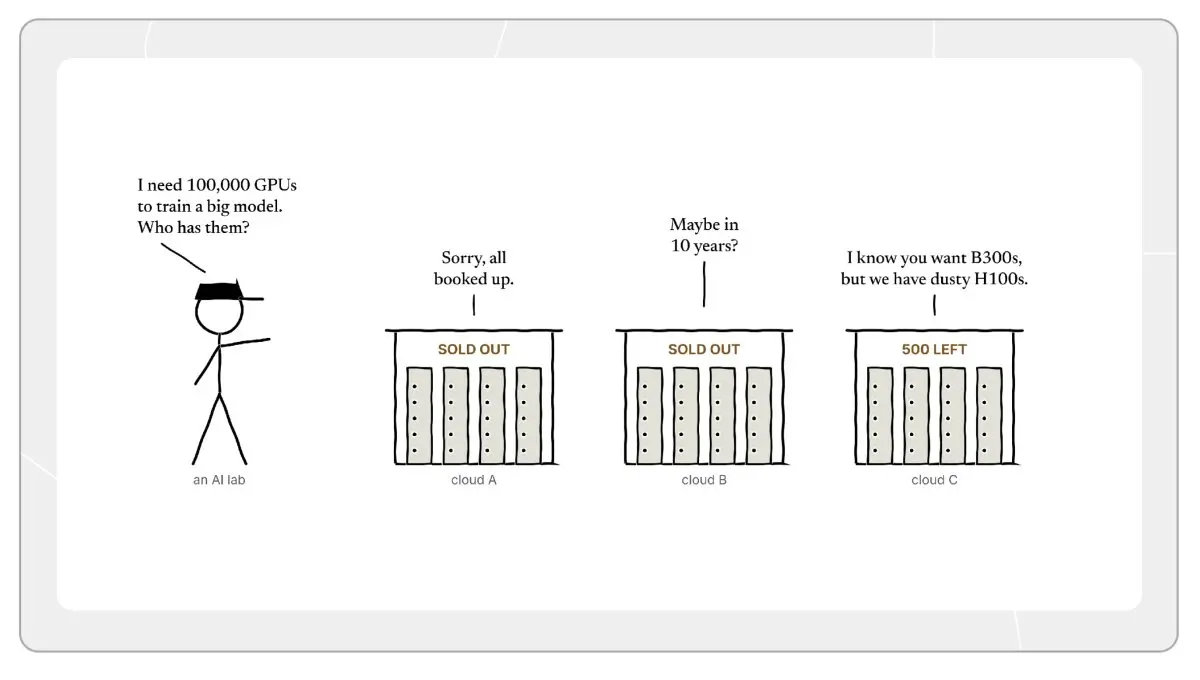
The common reasoning given is that there is currently a supply shortage. Everyone is eager for GPUs, and new supply takes years to come online.
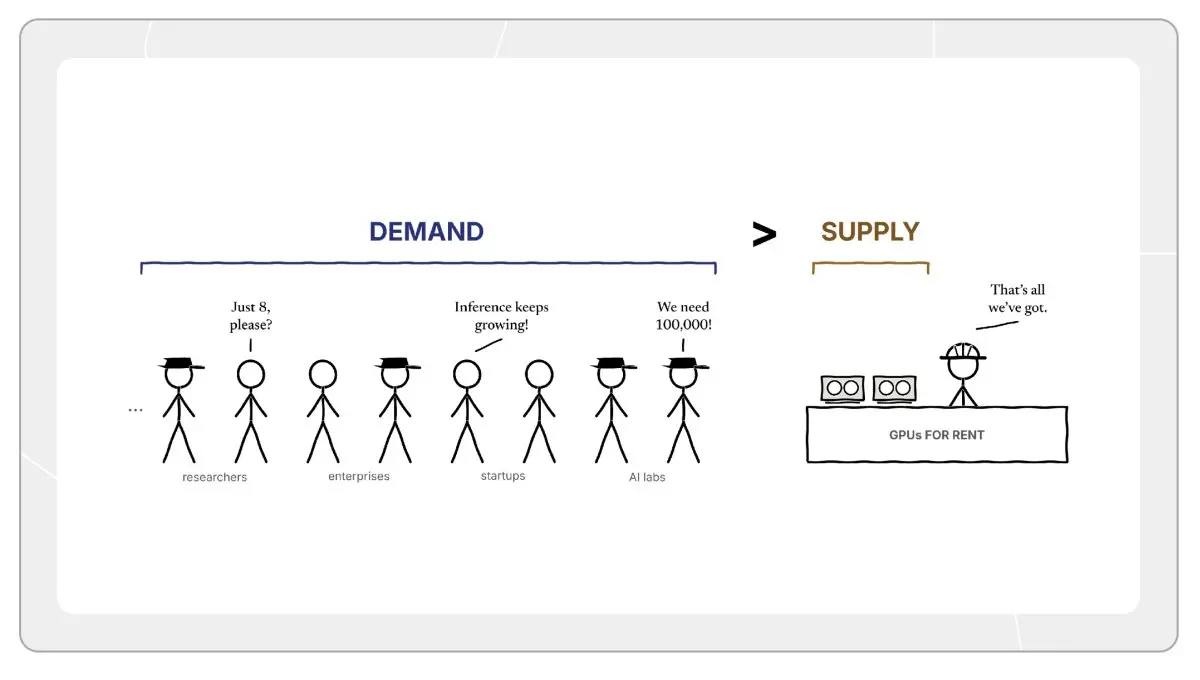
However, "supply shortage" is not entirely accurate. There is a fact that contradicts the mainstream narrative: there is actually a significant amount of idle computing power in the market.
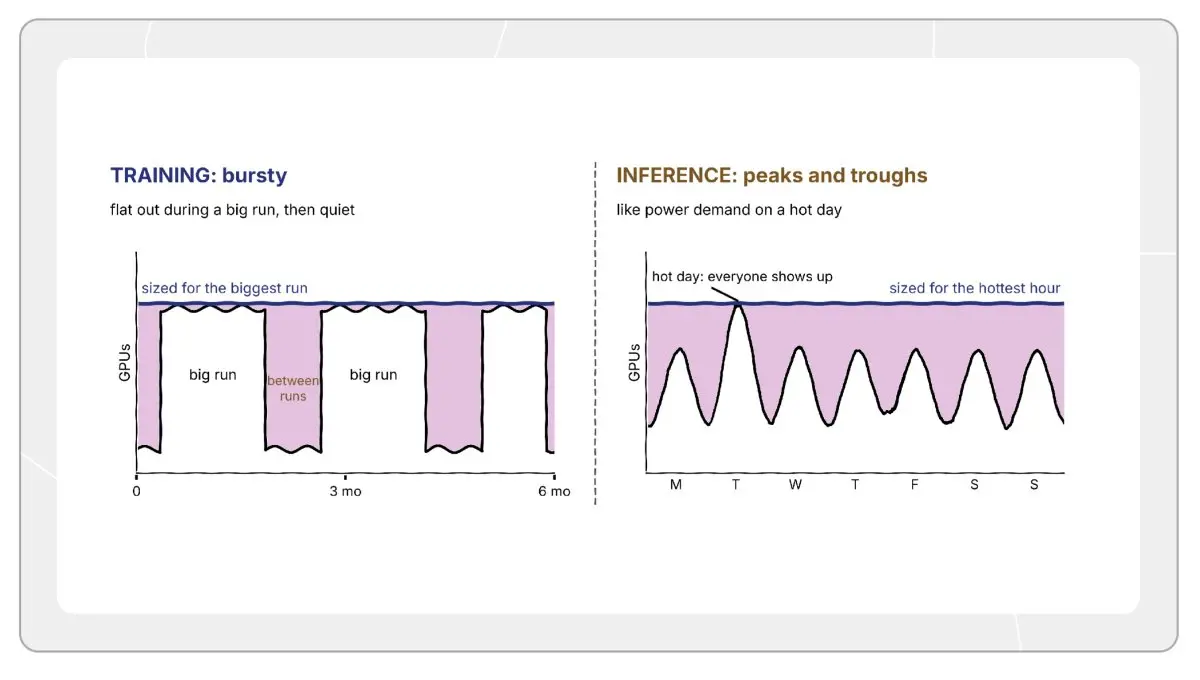
If you talk to existing buyers of computing power (those institutions with large reserves of computing power and strong balance sheets), you will find that many of them do not always use their computing power at full capacity. Model training is sporadic: during large-scale training runs, they will utilize most of the GPUs, but in the gaps between training cycles, much of the computing power remains idle. Inference tasks are volatile: usage is often much lower during nights, weekends, and holidays compared to peak days, while overall capacity is often configured based on peak demand.*
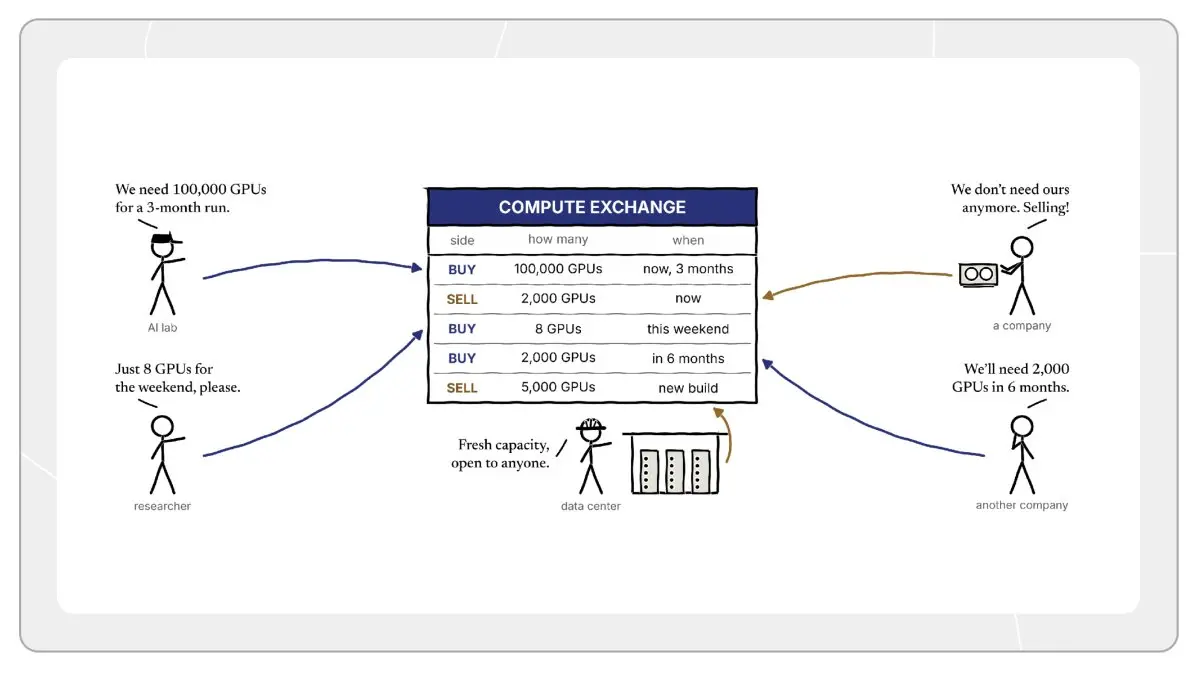
All this idle computing power points to an idealistic vision: to establish a GPU hour exchange. The market would be extremely efficient in resource allocation and price discovery, and since we see that the current GPU allocation may lack efficiency, theoretically, a trading platform could smooth out this supply-demand mismatch. However, there has yet to be a large-scale, deep computing power market example. While some platforms support renting small amounts of GPUs, such as Vast.ai, where owners can list GPUs and set their own prices, giant clusters cannot complete transactions on such platforms. In March of this year, CoreWeave launched Spot, offering lower-priced but potentially preempted capacity. Yet, there is still no centralized, large-scale, and liquidity-rich order book. Why is that?
A common explanation is that computing power is not a homogeneous product. There are H100s, B200s, and B300s, differences in network architectures between InfiniBand and Ethernet, as well as different cooling solutions, physical locations, and so on. Given such heterogeneous assets, how can a unified market be built?
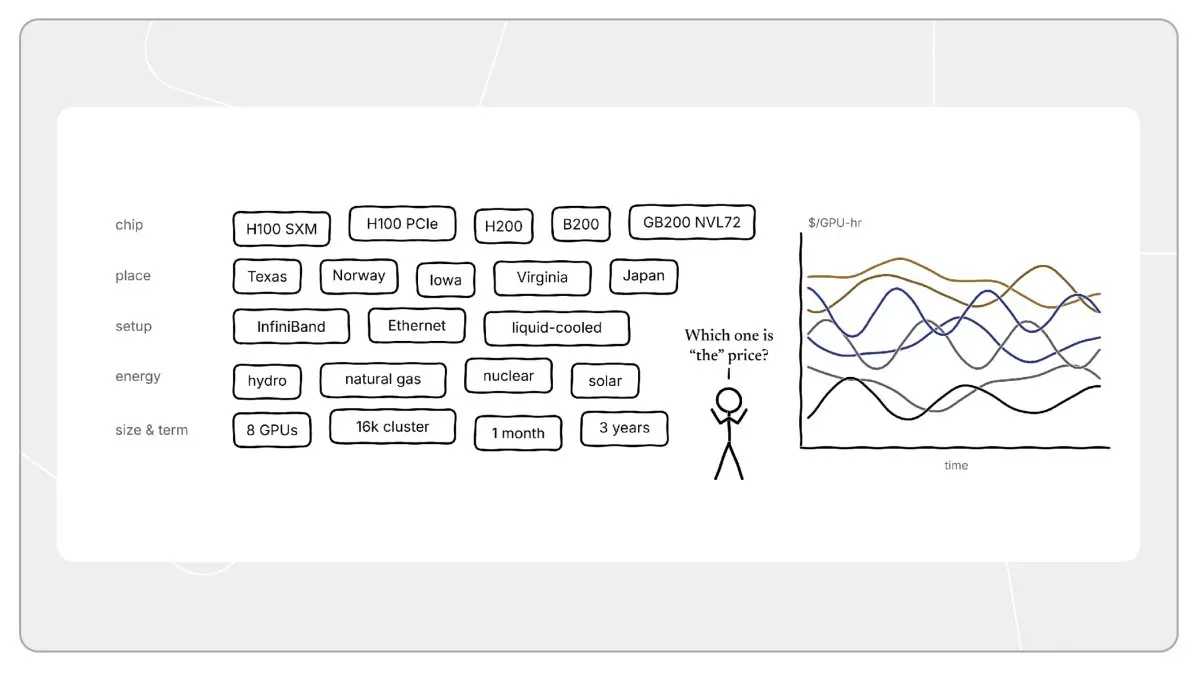
I believe this is not the only driving force. Crude oil also has hundreds of varieties. The market ultimately achieved standardization around a few benchmarks (such as WTI and Brent crude), with other varieties priced accordingly based on these benchmarks. Many markets trading heterogeneous goods also operate well, so while heterogeneity is a reason, it is by no means the whole story.
Another less mentioned underlying reason lies in the financing methods for GPUs. Large GPU clusters typically rely on borrowed funds for construction. The loan terms ultimately determine who can sell computing power and to whom it can be sold. To understand this, we first need to examine the current GPU financing model.**
Part Two: How GPUs Are Financed Today
Today's GPUs are often financed through "take-or-pay" contracts: a multi-year agreement where customers must pay for the capacity regardless of whether they actually use the computing power. This means that almost all computing power is subscribed before it is powered on. For example, CoreWeave derives 96% of its revenue from commitment contracts, and the contract terms are getting longer: about three years two years ago, four years a year ago, and now most are five years, with some even lasting six years.
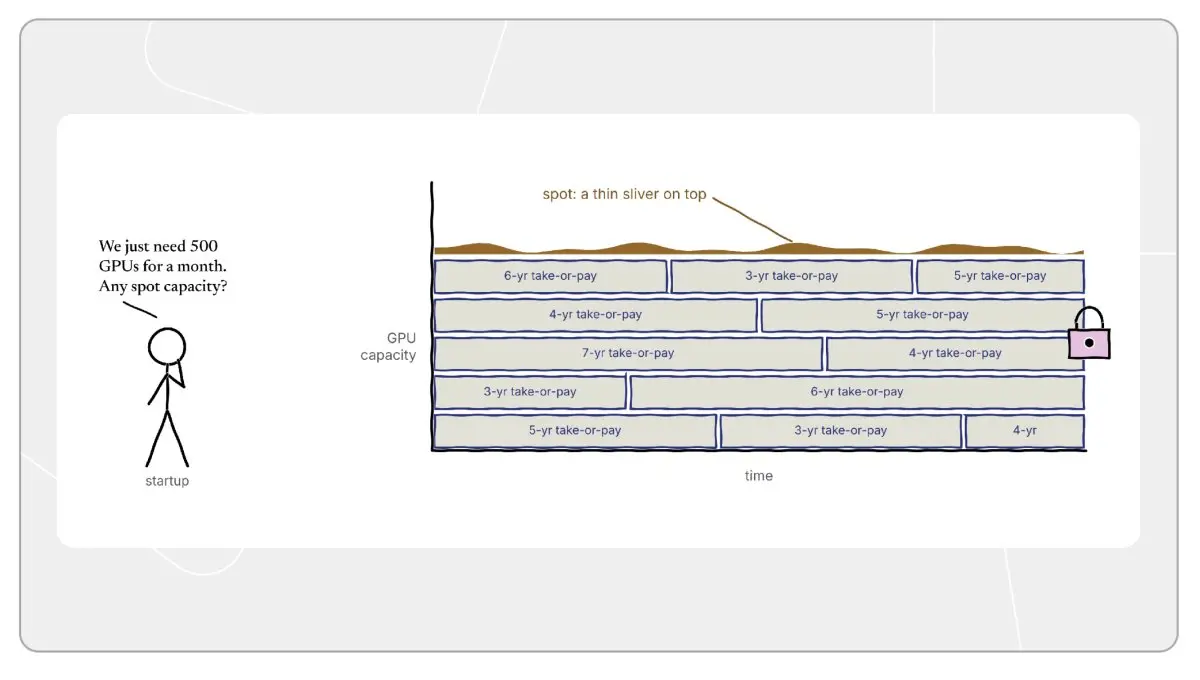
The Mechanism of "Take-or-Pay"
Here is the underlying logic of how GPUs are built in this way. Suppose you are an AI lab that needs 100,000 GPUs, and all sources in the market are sold out. A data center (such as a new cloud service provider or colocation developer) is willing to build a cluster for you, but it does not have billions of dollars in idle funds. It needs the intervention of a lender.
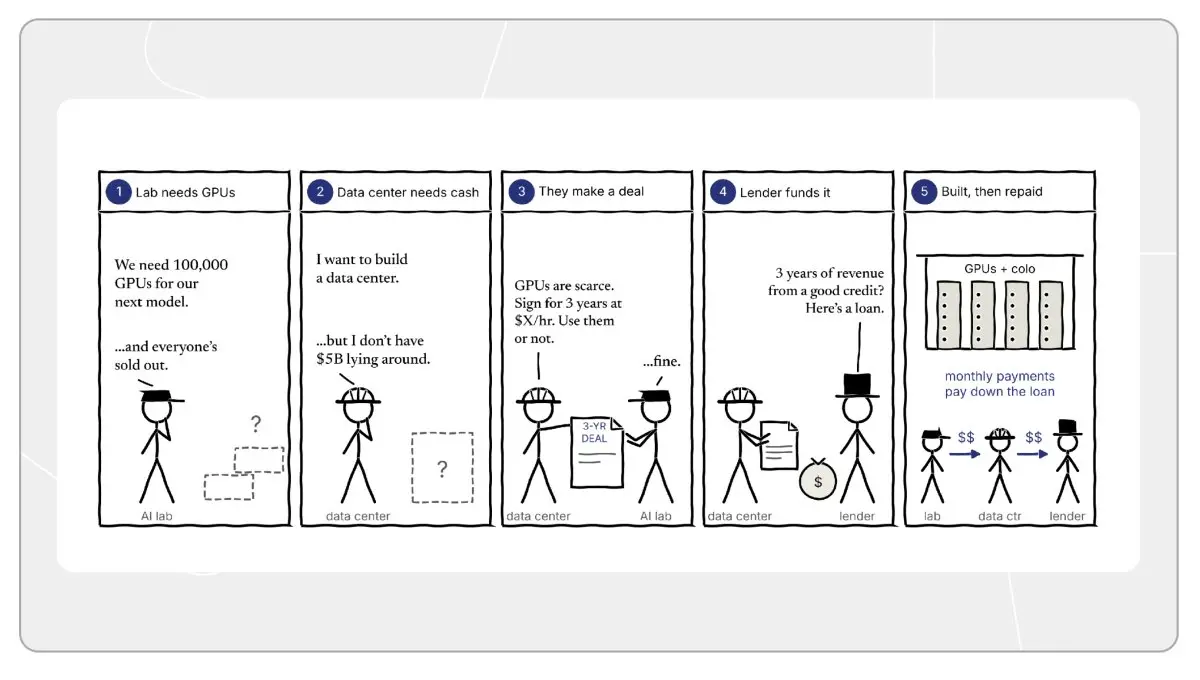
Now imagine you are the lending institution, facing an emerging market, being asked to invest billions of dollars in an asset you do not know how to value. How much will these GPUs be worth three years from now? What if the data center's clients go bankrupt? You cannot know the answer.
The "take-or-pay" contract solves this problem. Lenders do not need to guess the residual value of the GPUs because the cash flow (and the payment obligor) is relatively certain. Lenders can underwrite based on the contract revenue of well-known tenants. The data center procures GPUs and space, and the lab's monthly rental payments are used to repay the loan.***
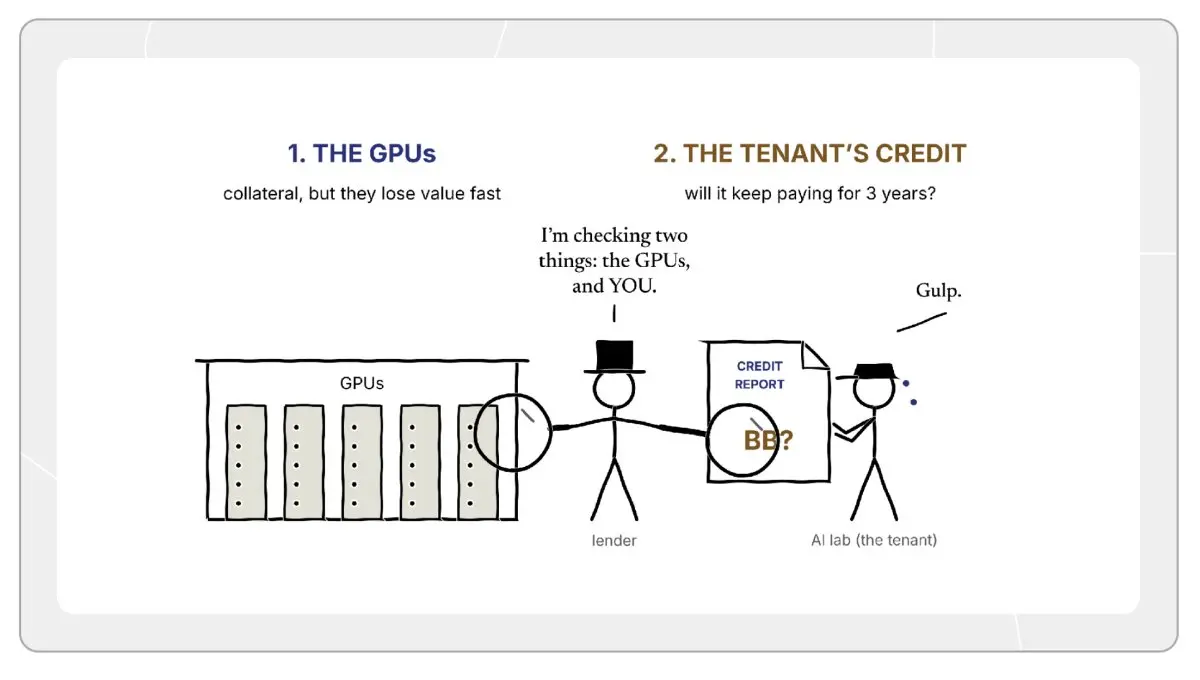
It is important to note that the creditworthiness of the tenant directly determines the cost of capital for the data center.
Customer Perspective
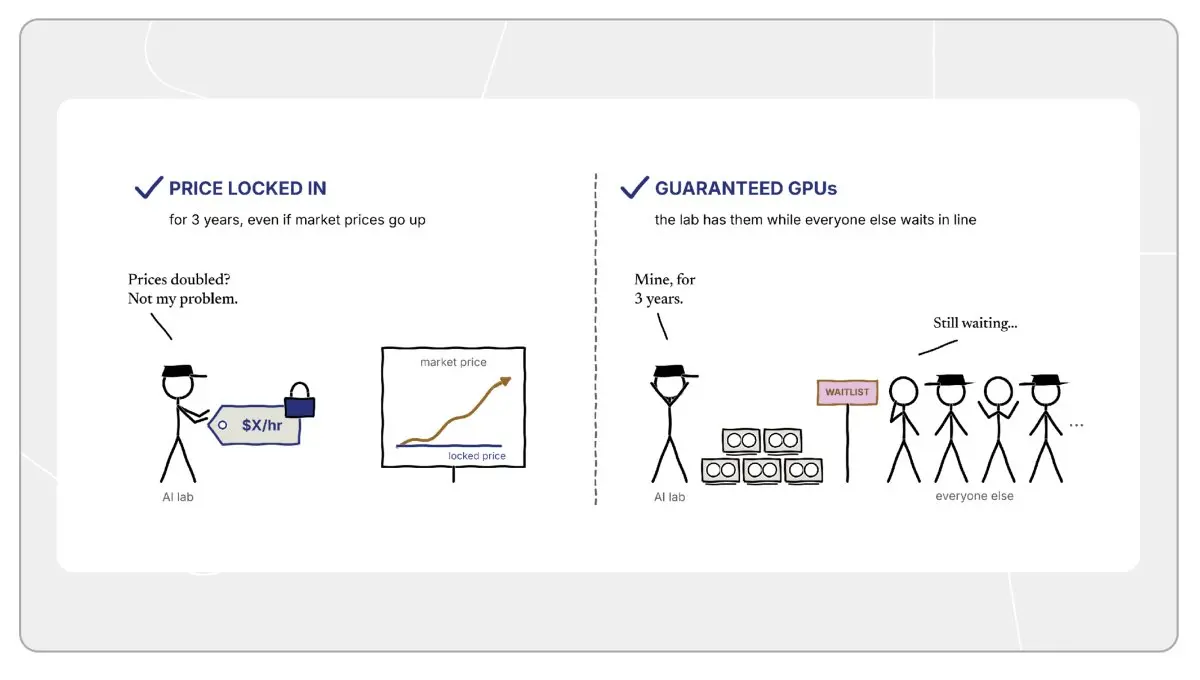
From the customer's perspective, prices are locked in for several years, and if market prices rise, as shown by Ornn's H100 rental price index in early May, the customer's costs do not change. This is a favorable aspect. Additionally, GPU supply is guaranteed: customers have a defined capacity throughout the contract period.
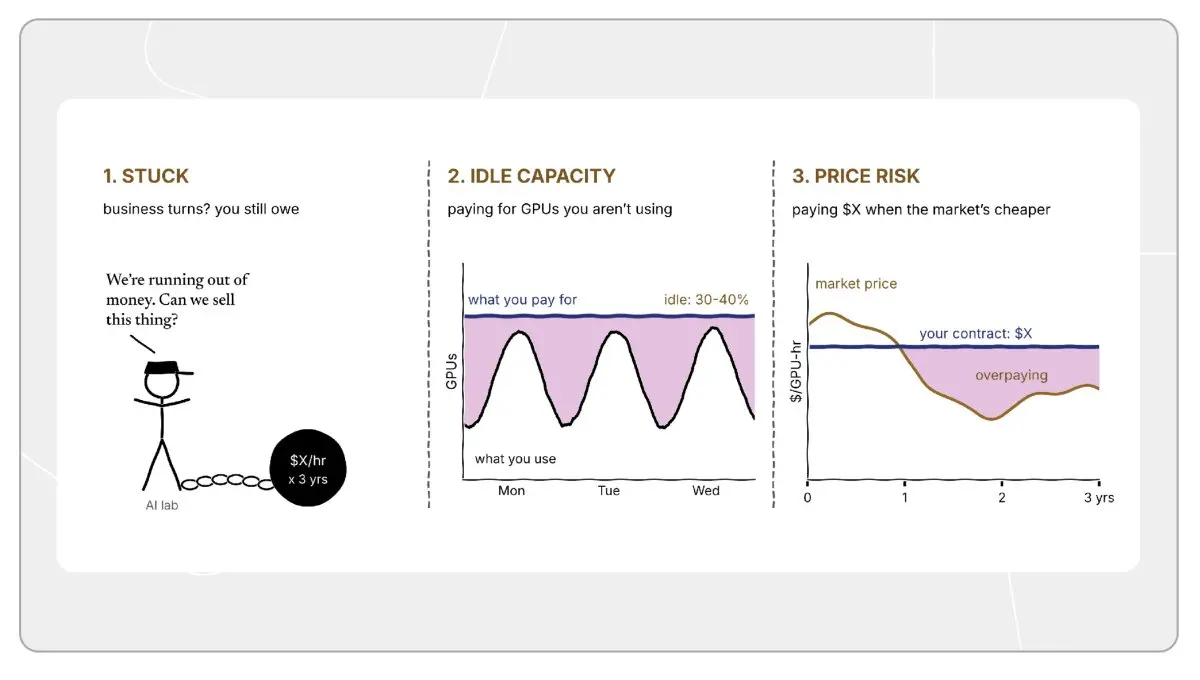
Conversely, customers also bear multiple risks. First, if the business runs out of funds or pivots, they still owe payments for each period. Second, customers are paying for idle capacity. Since procurement is based on peak demand, they are often paying for GPUs that are not actually used. Finally, if market prices fall, customers still have to fulfill their obligations at the locked-in high price.
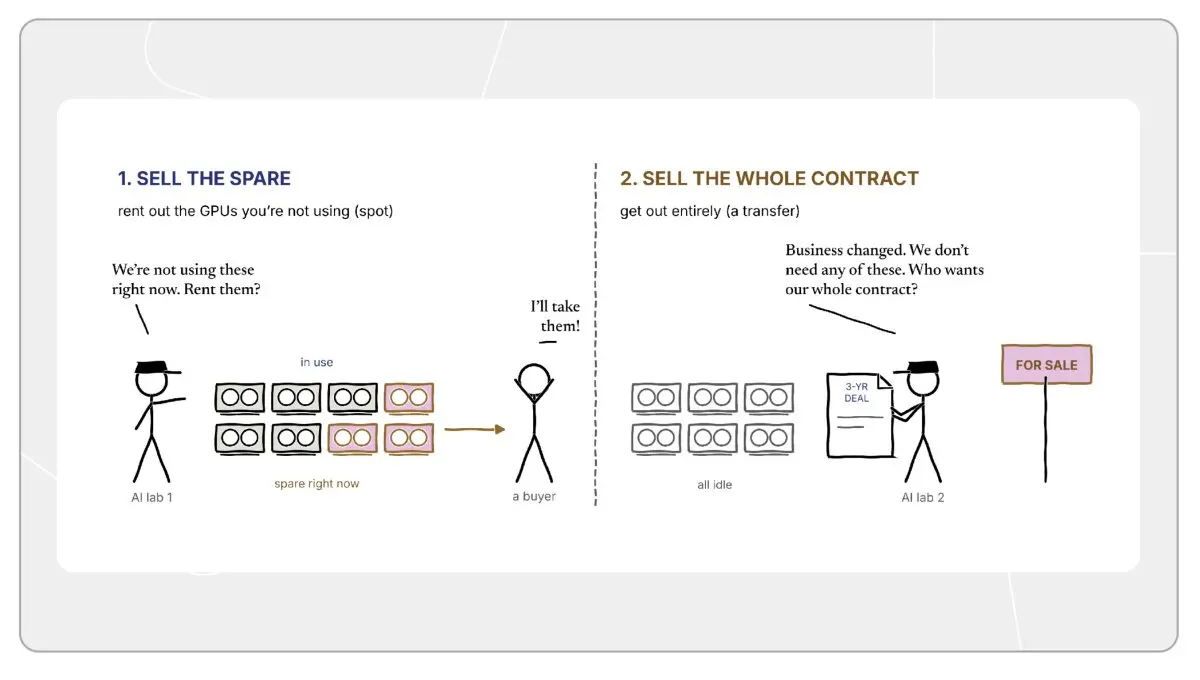
In this scenario, one can naturally envision the formation of a market: some customers may want to sell excess capacity during certain time periods, while others may want to completely transfer contracts to exit.
Part Three: Why Exchanges Are Difficult to Form
Imagine a large lab no longer needing the GPUs it owns and wanting to resell the contract to another institution. The lending institution would have concerns about this practice because, at the time of the initial loan issuance, it was essentially underwriting the credit of that lab.
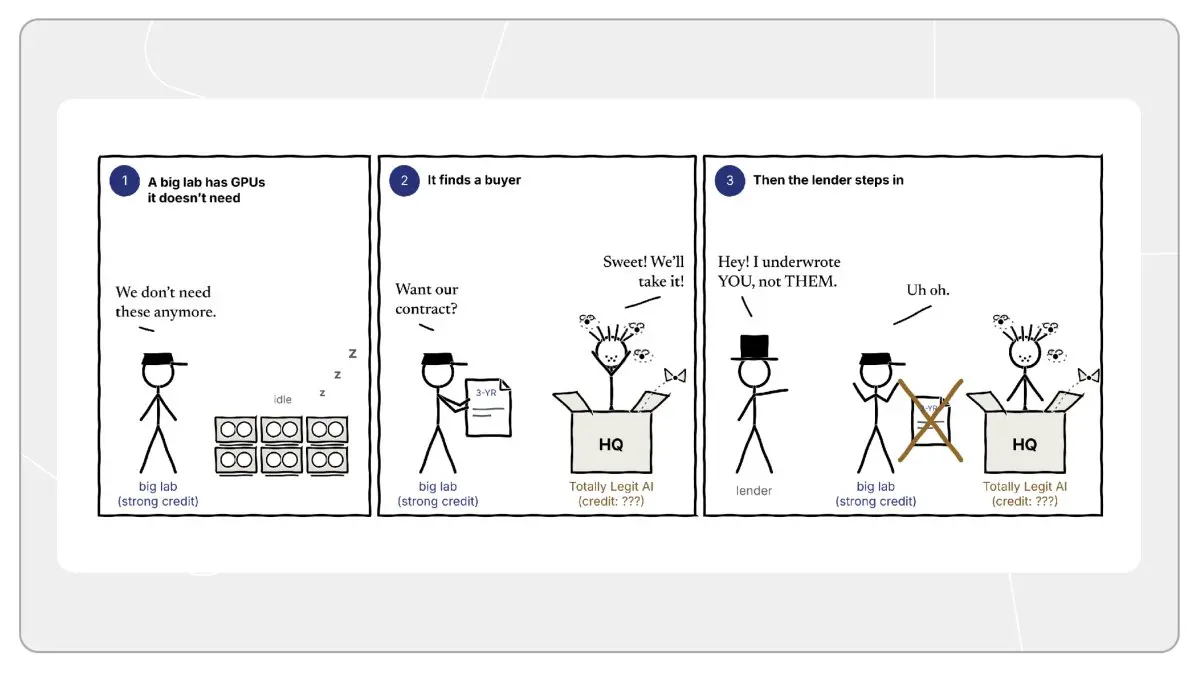
If your tenant is a large corporation with a high investment rating, you can obtain loans at much lower interest rates. If it is a higher-risk startup, the financing rate for the same GPU cluster would be much higher. The tenant determines the price of the loan, which is why if the tenant changes, lenders usually have to approve it. Therefore, the current market often operates through a subleasing model: the original AI lab continues to pay the data center, while the new buyer pays the original AI lab.****
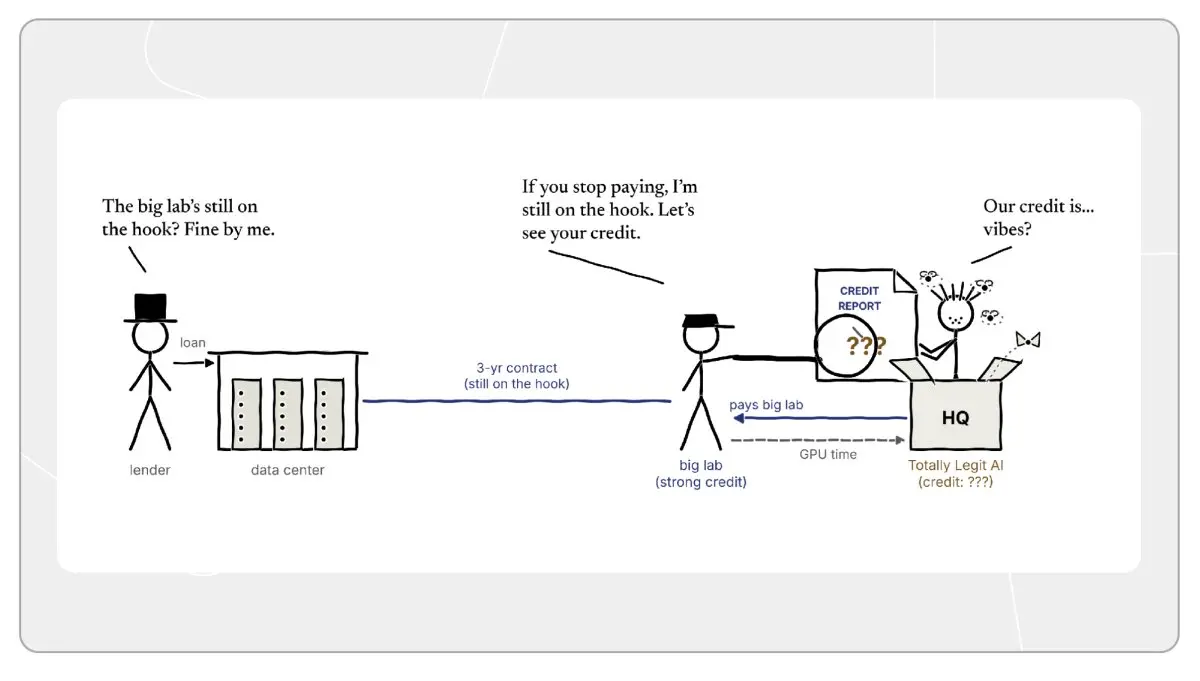
If the sublessor stops payment, the original AI laboratory still has the obligation to pay for the data center. This mechanism makes it difficult for the market to adapt to the traditional order book format.
If I sell Apple stock on the exchange, from the moment of trade settlement, my connection with the buyer ends. I don't even know who bought the stock; the best price wins. But in computing power trading, after selling, you still cannot escape joint performance liability, so you must be clear about the identity of the counterparty. The highest bidder could be a startup facing default risk, while the lending institution may not accept the next priority buyer.
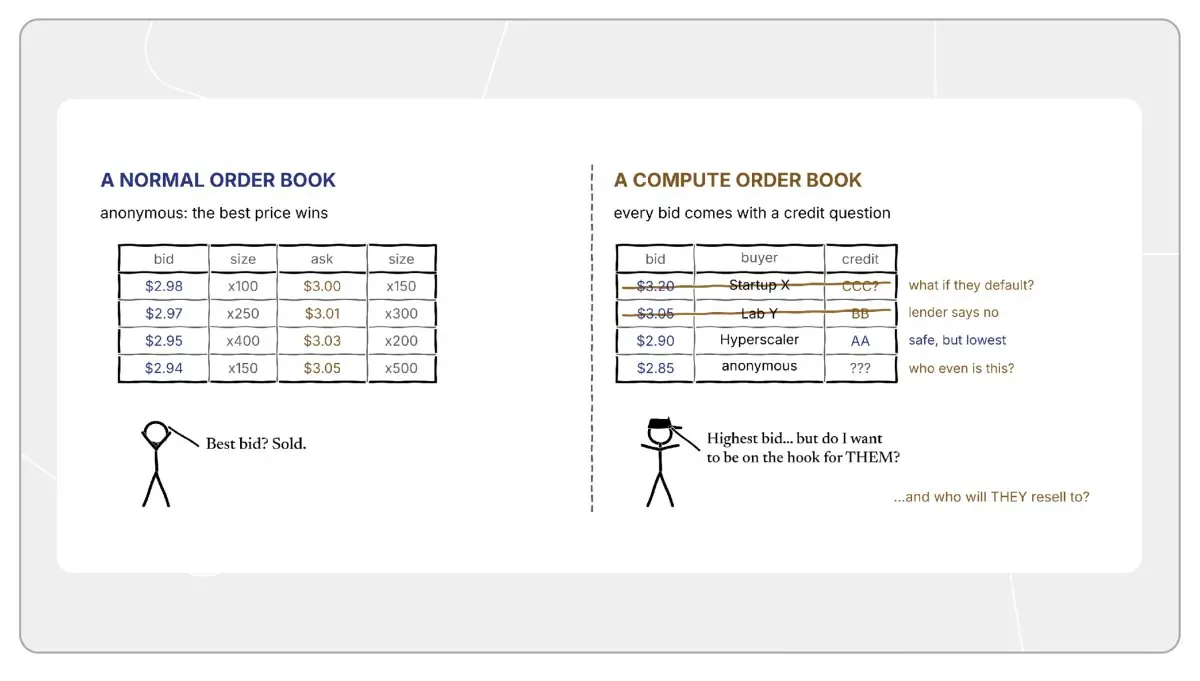
Next, a series of more complex scenarios will arise: Can the buyer resell to others? Does the original AI laboratory, which still bears responsibility, need to know the identity of the buyer?
What you ultimately face is a complex credit network, making it difficult for computing power to achieve scalable trading.
Part Four: Potential Solutions
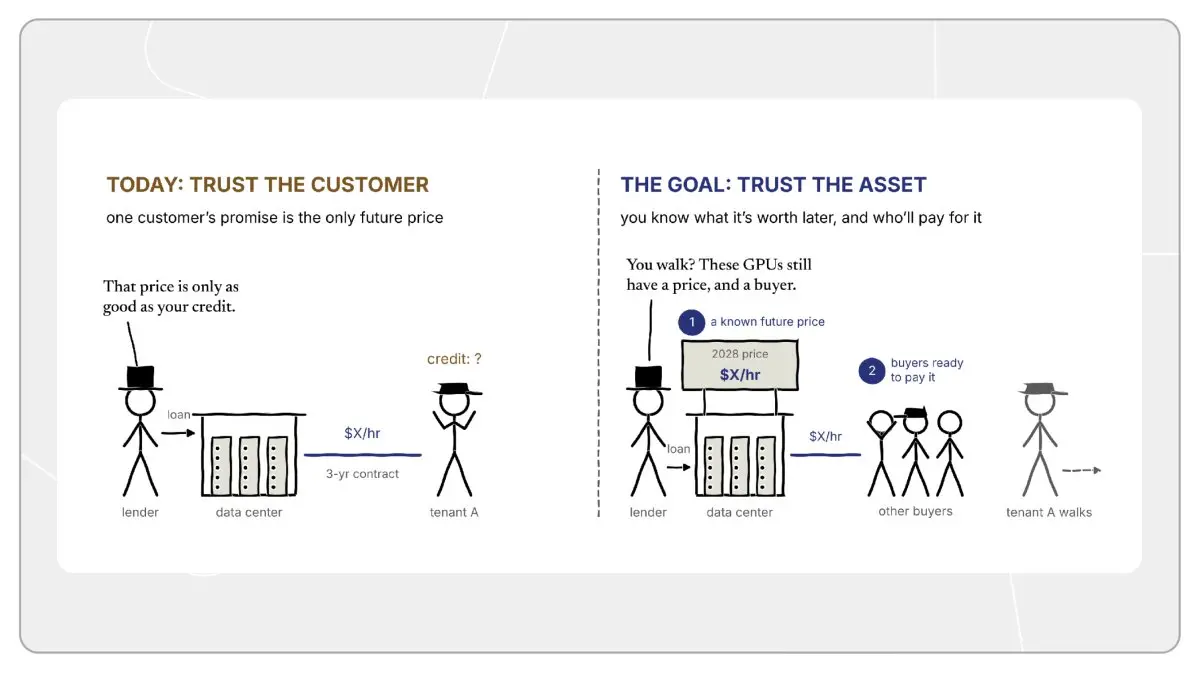
It can be found that the root of many problems lies in one point: in the eyes of lenders, GPUs and customers are bundled as a whole. Most mature markets are not like this. A barrel of crude oil does not care who the final buyer is.
To make the computing power market operate, lending institutions must trust the underlying assets themselves, rather than customer credit. In other words, lenders need to be confident that even if a customer withdraws midway, they can quickly find another customer to lease these GPUs. Trusting the asset requires two prerequisites: predictable future prices (similar to the forward price of crude oil) and a buyer market ready to take over at that price. Only with both can customers be replaceable, and contracts can flow smoothly.
But the reality is far more complicated than it appears. To trust the asset, lenders need a deep spot market to liquidate computing power when tenants withdraw. However, a deep spot market first requires lenders to trust the asset, which in turn allows GPUs to be built without "no questions asked" contracts. This is a chicken-or-egg dilemma.
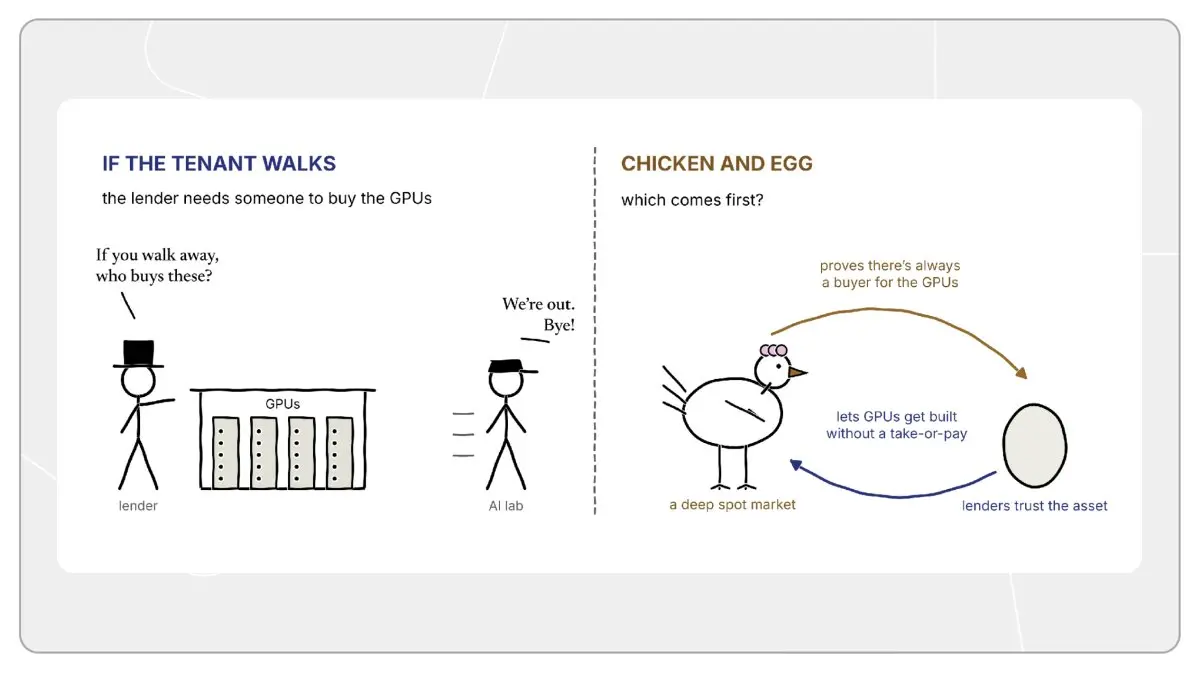
Moreover, even if the chicken-or-egg problem is overcome, it is uncertain whether a deep spot market can completely solve the issue, as risks are often systemically correlated. If a tenant defaults, the market usually faces a deeper systemic crisis, meaning many people are also trying to sell their GPUs. Therefore, when lenders truly need buyers to take over, it is often precisely when buyers are most scarce and prices are weakest.
So where is the hope for a breakthrough? The GPU market is one of the most important markets globally, with endless market demand, while existing resource allocation is inefficient: on one side are idle GPUs, and on the other side are buyers waiting in line. In extreme cases, the profit-seeking mechanism will eventually find a way to smooth out this inefficiency.
If you are also an entrepreneur thinking about this problem, feel free to reach out for discussion. My Twitter DMs are always open: jonah_b.
Appendix
* Top AI laboratories are exceptions. Because they simultaneously carry model training and inference services, rather than engaging in a single business, they can achieve much higher utilization rates. Additionally, as personal agents begin to execute scheduled tasks, they can insert these jobs into any remaining idle time windows, further boosting utilization.
** I do not wish for readers to conclude that "the credit market is the only reason for the lack of a liquid spot computing power market" after reading this article. The main point of this article is to clarify that the structure of the credit market is one of the core driving forces hindering the formation of a spot market.
*** The explanation of "no questions asked" in Part Two is a simplified version. In actual business operations, the construction of large computing power clusters involves more participants, and their credit commitments are often nested layer by layer.
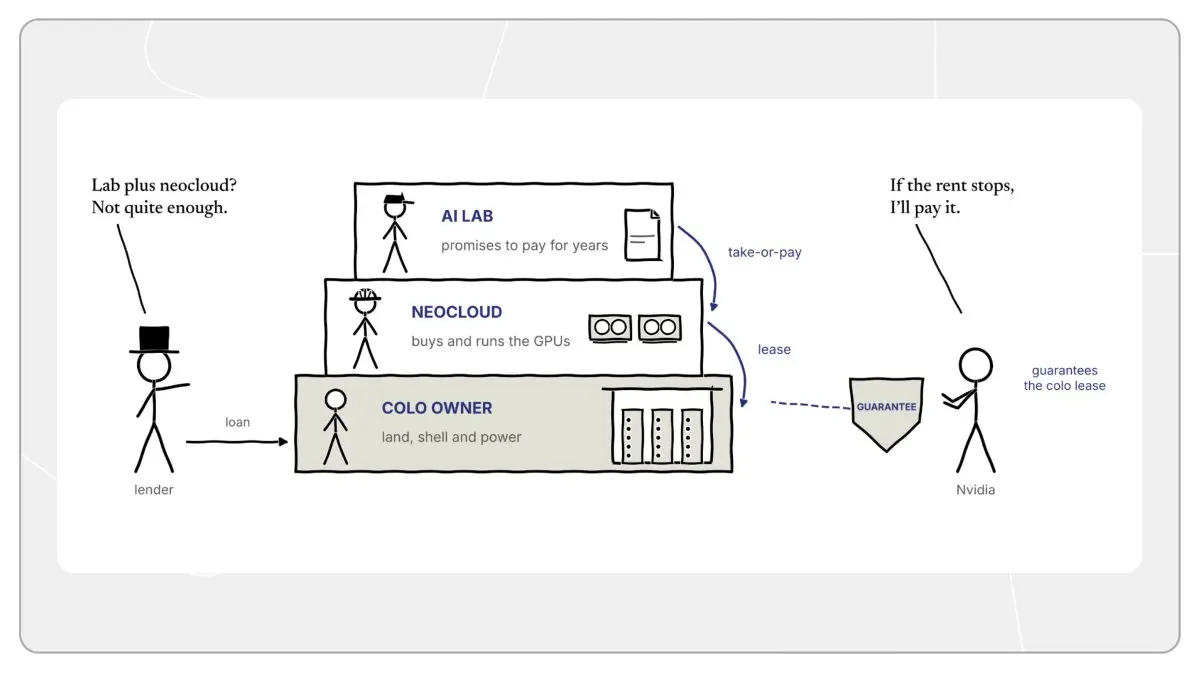
Data center hosting property owners (bottom layer): Usually real estate investors. They own land, building structures, cooling facilities, rack shells, and power resources, leasing physical space and borrowing against the lease contract for construction.
New cloud service providers (middle layer): Purchase and operate GPUs, pay data center rent to the hosting party, and borrow against contracts signed with AI laboratories to pay for chip procurement.
AI laboratories (top layer): The final purchasing party. They sign "no questions asked" agreements, committing to pay the new cloud service providers for several consecutive years.
The lending institutions of the hosting property owners are pricing the risk of the new cloud service providers' performance in paying rent. New cloud service providers often have limited capital strength, and laboratory contracts are usually signed for only a few years, while data center leases often last over ten years. Therefore, lending institutions may require the introduction of guarantors: entities with stronger credit strength to endorse the lease. Nvidia has currently begun to intervene and play this role.
**** Some contracts do allow transfer to new tenants, a process known as assignment. Lending institutions may accept replacement with tenants of equivalent credit risk ratings but will not accept tenants with poorer qualifications. Furthermore, unless formally released from contract obligations, even if the transfer is completed, the original signing party may still bear residual liability. This mechanism fundamentally cannot support a truly programmatic, automated matching order book system.
 Risk warning Risk warning

Popular articles





