SpaceX conference call: Musk stated that next year's ARR could reach 1 trillion, and a committee has been established to explore the merger with Tesla
 Core Viewpoint


 Musk stated that he expects SpaceX's ARR to reach $500 billion to $1 trillion by the end of 2027; for the remaining months of this year, they will invest 200,000 NVIDIA GB300 GPUs each month, aiming to achieve 13GW of AI computing power by 2027, including a single training cluster composed of 440,000 NVIDIA Rubin GPUs; due to a conflict of interest, he is avoiding discussions about a merger between SpaceX and Tesla, and the merger is not a done deal, requiring the support of half of Tesla's shareholders.
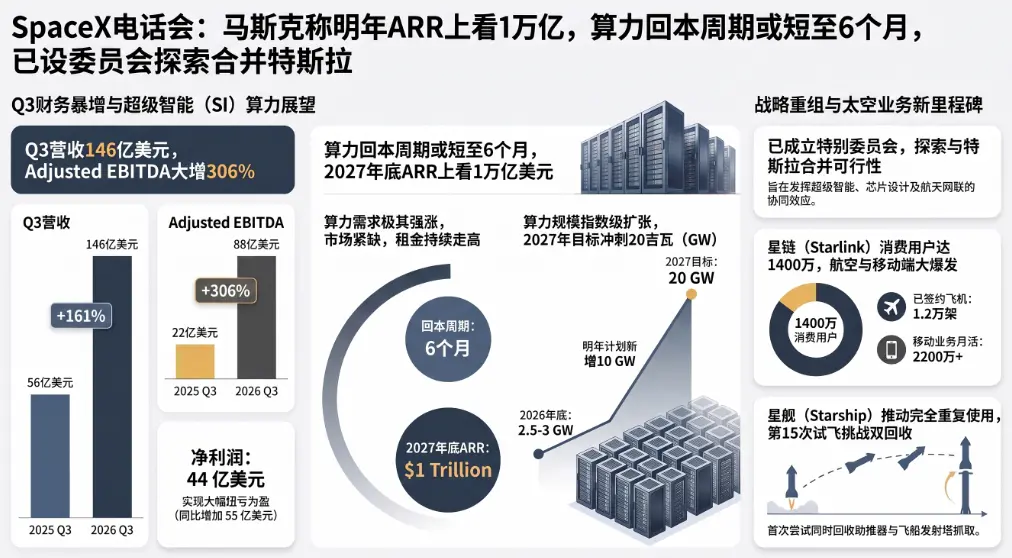
SpaceX's third-quarter performance has seen a significant explosion, with Musk not only announcing a minimum of 13GW by 2027, but also challenging a 20GW aggressive expansion plan for AI computing power. He boldly stated that the company's annual recurring revenue is expected to reach the trillion-dollar mark by the end of next year.
Wall Street Journal mentioned that after the U.S. stock market closed on Tuesday, October 20, SpaceX announced that for the third quarter of 2026, ending in September, the company's revenue grew by 161% year-on-year to $14.58 billion, exceeding analysts' expectations of about $12.8 billion by more than 10%.
Behind the explosive revenue growth is the rapid increase in the super-intelligent cloud service business. The super-intelligent business achieved quarterly revenue of $7.6 billion, a sequential increase of $5 billion and a year-on-year increase of $6.7 billion. Meanwhile, net profit turned from a loss of $1.1 billion in the same period last year to a profit of $4.4 billion, with adjusted EBITDA reaching $8.8 billion, a year-on-year increase of 306%.
During the conference call, CEO Musk stated that the market demand for super-intelligent computing power is extremely strong, with the payback period for deploying supercomputing infrastructure now compressed to less than a year, and short-term contract renewal prices continuing to rise.
Musk further predicted that the company's annual recurring revenue (ARR) in 2027 is expected to reach between $500 billion and $1 trillion.
Musk stated that by the end of 2026, 2.5 to 3GW of computing power will be operational, and SpaceX is quite confident in achieving 10GW of computing power online by 2027, saying that if the computing power online by the end of next year is less than 13GW, he would be surprised.
To support this expansion, SpaceX plans to add an additional 20GW of power supply and cooling infrastructure by 2027. Musk stated that SpaceX's speed in deploying power, cooling, and supporting infrastructure is expected to exceed the total of all other vendors combined.
Regarding rocket launches and Starlink data, SpaceX's Chief Operating Officer Gwynne Shotwell stated during the conference call that the company expects to achieve reusable rocket second-stage launches early next year. Shotwell mentioned that the production of Starlink aviation terminals is expected to double by the end of this year.
Shotwell revealed that Starlink's mobile direct-to-phone service has surpassed 22 million monthly active users. The acquisition of spectrum will allow Starlink to become a major mobile operator in the U.S. Starlink's enterprise and government business revenue is expected to exceed consumer business revenue in the future. Starlink is expected to carry a significant portion of global internet traffic.
Regarding the merger of SpaceX and Tesla, Musk stated that SpaceX and Tesla have formed a special committee to explore the possibility of a merger. Media pointed out that if the merger happens, it would become the largest corporate merger in history.
Exceeding Expectations in Computing Power Stacking and NVIDIA Orders
Previously, the market generally underestimated Musk's companies' ambitions in AI computing power. During this meeting, Musk provided a shocking timeline for computing power deployment, significantly raising previous targets.
Musk stated during the conference call:
People are starting to realize that the constraints on deploying super-intelligence are more about power, cooling, and infrastructure, rather than chips.
He mentioned that SpaceX has transferred its top team, which has captured nearly 90% of the global orbital mass share in the aerospace field, to the deployment of ground computing power. Musk said:
It's a bit like the New York Yankees playing in a little league; it's not fair. But the end result is that we are deploying power and cooling infrastructure much faster than anyone else, possibly even faster than the total of everyone else combined. I want everyone to digest this fact first.
In terms of specific NVIDIA GPU orders and delivery timelines, the incremental data is extremely impressive. Musk revealed that the team is currently working day and night:
Our current progress is that in each of the remaining months of this year, we can bring about 200,000 GB300 online each month and will maintain this pace next year, primarily deploying Vera Rubin.
For future total computing capacity, Musk provided extremely high performance guidance:
By the end of this year, we will have about 2.5 to 3GW of computing power online. I am very confident that we will add 10GW of computing power by 2027. In other words, if the computing power we have online by the end of next year is less than 13GW, I would be surprised.
What draws more market attention is that he left a huge space for imagination:
To ensure that power and cooling do not become bottlenecks, our actual goal for next year is to add 20GW of power and cooling infrastructure… So, next year SpaceX may have more than 20GW of super-intelligent computing power online.
Additionally, he confirmed that by the end of the second quarter of next year, the strongest training cluster composed of 440,000 Vera Rubin computers will be online to support the Grok large model.
Rapid Payback Period of 6 Months and Computing Power Shortage
SpaceX expects Q4 capital expenditures to reach $35 billion to $40 billion, and in the face of massive capital expenditures, the market is highly concerned about the sustainability of its commercial monetization. SpaceX's management provided extremely optimistic feedback.
Chief Financial Officer Bret pointed out that the current market conditions are "unusual," and under current pricing, the payback period for new computing power deployments has been reduced to less than a year. Musk's statement was even more aggressive:
I want to say that it's not impossible; next year our payback period for computing power may shorten to 6 months.
Musk firmly believes that the value of computing power per watt will rise as AI models are optimized, so SpaceX prefers to sign short-term lease contracts at spot market rates rather than long-term commitments. He used a famous sketch from the British comedy group Monty Python, "The Cheese Shop," to describe the current industry's hunger for computing power:
We are actually being relentlessly pursued by every hyperscale cloud vendor and dozens of small companies, demanding to rent more of our computing power. If we say 'yes' to everyone, our computing power could be rented out several times. It's like that person going to the cheese shop to buy cheese… We tried to outsource some inference computing power to other cloud service providers, and ended up encountering the 'cheese shop scenario.' We asked, 'Do you have GB300?' No. 'What about GB200?' No. 'TPU?' No. 'H100?' No. This is simply absurd.
With the high-margin cloud service agreements, SpaceX's supercomputing division (SI) generated $7.6 billion in revenue in the third quarter, a sequential increase of $5 billion. The company maintains its goal of achieving an annual recurring revenue (ARR) of $100 billion for this business by the end of this year. For the longer-term future, Musk provided an astonishing forecast:
In short, this means that by the end of 2027, SpaceX's annual recurring revenue (ARR) will be between $500 billion and $1 trillion.
Starship Full Reusability Breakthrough and the Trillion-Dollar Ecosystem's Moat
In the traditional space business sector, SpaceX is also nurturing a significant fundamental transformation.
Musk emphasized that the 15th flight of Starship will take place next month, attempting to "simultaneously recover the booster and the spacecraft" during an orbital launch for the first time. He said:
This is a profoundly significant technological milestone in the history of civilization… If the 15th flight is not successful, we will eventually achieve it.
SpaceX expects Starship to achieve weekly flights in the first half of next year and to achieve weekly launches twice or even more frequently in the second half of the year.
The maturity of Starship directly grants the Starlink network the capability for dimensionality reduction strikes. The recently launched V3 satellites provide bandwidth equivalent to 10 Falcon 9 launches in a single deployment.
Musk expects that within three years, Starlink's bandwidth will reach about 100 times its current level, and in the future, approximately 100,000 satellites with bandwidth exceeding the current level by more than 10 times will be launched to meet the "exponential communication bandwidth demand brought by the AI agent explosion."
Additionally, regarding the market's hot discussion on "self-developed chips (TerraFab)," Musk confirmed that the internal goal is to manufacture the first functional test chip in the Austin lab by May or June next year, with the aspiration to achieve mass production in the TerraFab main plant by the third quarter of 2028, with the ultimate goal of achieving an annual production capacity of "1 Terawatt" of super-intelligent chips.
Musk Avoids Discussion of SpaceX and Tesla Merger Due to Conflict of Interest
Regarding the merger of his two companies, Musk stated that SpaceX and Tesla have formed a special committee to explore the possibility of a merger. Media pointed out that if the merger happens, it would become the largest corporate merger in history.
Musk stated:
Although there is currently no guarantee of an agreement, I believe there is significant value in merging the two companies, as we are at the singularity of super-intelligence.
Musk mentioned that due to his own conflict of interest, he has not participated in the discussions of the aforementioned committee; currently, the committees have not reached a consensus on the merger terms.
Musk cautioned that the merger still has uncertainties and must gain shareholder support. He stated that Tesla needs to obtain approval from 50% of all shareholders, not just a majority of those participating in the vote. He said:
Some people believe that the merger of SpaceX and Tesla is a done deal. I think that statement is exaggerated.
Full transcript of SpaceX conference call (AI-assisted translation):
Head of Investor Relations Andrea Williams:
Hello everyone, welcome to our Starlink factory in Bastrop, Texas, which will also be the production base for Starmind in the future. I am Andrea Williams, Head of Investor Relations, and thank you all for attending SpaceX's third-quarter financial results conference for 2026.
Also attending this meeting are Elon, Gwynne, and Bret, and this meeting is being live-streamed on the X platform. Our third-quarter financial performance was officially announced after 3 PM Texas time, and all relevant materials have been published on our investor relations website ir.spacex.com.
This conference will be divided into two parts: first, prepared remarks, followed by a Q&A session. We will first take live questions from stock analysts, then answer questions from investors—these questions come from the exclusive financial Q&A platform built by the SpaceX team in collaboration with Brock.
In this live broadcast, we will provide an outlook on the company's business prospects, and all statements are based on our current forecasts and expectations. As of today, actual events or performance results may differ significantly from expectations due to various risks and uncertainties, including the risk factors mentioned in our financial report release and the latest documents submitted to the SEC (including the final offering memorandum). During the presentation, we may discuss several non-GAAP financial metrics; for relevant disclosure information and adjustments to comparable GAAP metrics, please refer to today's financial report release and SEC documents.
Here are the financial results for the third quarter of 2026 (compared to the same period last year):
Operating revenue: $14.6 billion, a year-on-year increase of 161% (compared to $5.6 billion in the same period last year); Net profit: $4.4 billion, a year-on-year improvement of $5.5 billion (compared to a net loss of $1.1 billion in the same period last year); Adjusted EBITDA: $8.8 billion, a year-on-year increase of 306% (compared to $2.2 billion in the same period last year).
Now, let's welcome Elon to speak.
Co-founder and CEO Elon Musk: Thank you.
Currently, SpaceX has reached important turning points in the fields of launches, connectivity, and super-intelligence.
In terms of Starship, the 14th flight is a key milestone—Sasha has entered orbit for the first time and successfully deployed operational Starlink V3 satellites. We have a recap video that will be played later. The 15th flight is expected to take place next month, and we will attempt to recover both the booster and the spacecraft simultaneously. If successful, this will be the first complete recovery in the history of orbital launch vehicles, marking a significant technological milestone.
Achieving sustained presence beyond Earth, fully reusable orbital launch vehicles are the only way forward. Therefore, I believe this is a profoundly significant technological milestone in the history of human civilization. Next, we will play a simulation animation of the 15th flight, showcasing the flight process under successful conditions.
Even if the 15th flight does not succeed, we will persist. The success of the first few flights does not guarantee a 100% success rate, but I believe the probability of success for the next flight exceeds 50%. If we do not succeed, we will continue to schedule Starship flight attempts before the end of this year and further increase the frequency next year.
We also announced the development plan for the Louisiana space launch site. This will be an important asset of great value to the United States and the world, with approximately 20 or more launch towers expected to be built, capable of transporting millions of tons of payloads to orbit and beyond each year, which is significant.
We expect Starship to achieve a flight frequency of once a week in the first half of next year, twice a week in the second half of next year, and possibly even higher frequencies by the end of next year. With breakthroughs in rapid fully reusable technology, the launch frequency of Starship will be greatly enhanced.
After achieving full reusability, there will initially be some maintenance work required between flights, but we will gradually eliminate the need for maintenance, ultimately achieving the ability to relaunch rockets immediately after landing, just like airplanes. As I mentioned earlier, this is a profoundly significant technological milestone, and although most people may not yet realize its importance, it will be obvious in hindsight.
Regarding Starlink, we are also just getting started. The 14th flight deployed 26 Tbps (terabits per second) of Starlink bandwidth, equivalent to the total bandwidth of 10 Falcon 9 launches. In other words, a single Starship launch—still only half-loaded—achieved the effect of 10 Falcon 9 launches.
I expect that it will not take long, within about three years, for the bandwidth of our Starlink constellation to reach approximately 100 times the current level—because we will launch satellites that increase bandwidth by an order of magnitude while also increasing the total number of Starlink satellites by an order of magnitude, reaching about 100,000, each with bandwidth exceeding 10 times that of the existing Starlink system. Starlink's revenue will generally grow in proportion to the total bandwidth provided.
We will also have high-bandwidth direct-to-cell capabilities and will build ground networks to provide extensive connectivity in all areas where SpaceX and Starlink are authorized to operate. I believe that within the next 3 to 5 years, bandwidth demand will far exceed today’s—potentially 1,000 times the current demand. The reason is that AI agents will consume bandwidth far beyond that of individual human users, and the number of agents will also far exceed the human population, necessitating several orders of magnitude increase in communication bandwidth to meet the enormous communication needs.
Regarding superintelligence, I refer to it as SpaceX SI (SpaceX Superintelligence). People are gradually realizing that the bottleneck limiting the deployment of superintelligence is more about power, cooling, and infrastructure rather than the chips themselves.
SpaceX has an outstanding team that has achieved nearly 90% of the global mass-to-orbit share, with China accounting for about 6%, and the rest of the countries and regions (including other U.S. entities) collectively accounting for about 4%. The achievements of this team surpass those of all space competitors combined by an order of magnitude. Now, we are applying this same team to the deployment of ground computing power. It’s like the New York Yankees playing in the minor leagues, where the outcome is almost a foregone conclusion. The end result is that we can deploy power and cooling infrastructure at a speed far exceeding that of any other company, and at times possibly surpassing the total of all other companies combined. Please take a moment to digest this statement.
I personally have spent a lot of time in Memphis recently, often going four days a week, tirelessly pushing forward the launch of the Memphis supercomputing cluster. We plan to steadily bring online about 200,000 GV300 units each month for the remainder of this year, continuing this pace into next year, with the main focus switching to Vera Rubin computing power next year. Currently, I am quite confident that we can bring online an additional 10 GW of computing power by 2027, which will be in addition to the approximately 2.5 to 3 GW expected to be completed by the end of this year.
In other words, if we do not bring online at least 13 GW of computing power by the end of next year, I would be surprised. As mentioned earlier, power and cooling are somewhat limiting factors. To ensure that infrastructure does not become a bottleneck for our expansion, we have set a goal for next year to add 20 GW of power and cooling infrastructure, ensuring that the available power and cooling capacity far exceeds what is required for GPUs.
There is also a possibility—currently low probability but not zero—that SpaceX's online superintelligence computing power will exceed 20 GW next year. While this probability is small, it is no longer zero.
We also plan to complete the launch of the most powerful training cluster in history by the end of the second quarter, deploying 440,000 Vera Rubin computing units for optimized training. I believe this will greatly assist Grok in becoming the top model, or at least highly competitive.
Regarding Grok Bot, I have never seen any product grow so rapidly. Moreover, the user engagement of Grok Bot continues to increase over time rather than decline—as we continuously enhance its practicality, the frequency of user engagement each week is also rising. We will also deploy Grok Bot on a large scale for enterprise customers, allowing company teams to collaborate as efficiently as virtual team members. We have already begun early deployments with some trusted customers and expect to roll it out to enterprise customers in a few weeks. I believe Grok Bot may ultimately become the application that consumes the most of our superintelligence computing power.
In summary, what does all of this mean for SpaceX's annual recurring revenue by the end of 2027? The answer is between $500 billion and $1 trillion. Next, I would like to invite Bret.
Head of Investor Relations Andrea Williams: Thank you, Elon. This quarter we once again achieved outstanding execution. Today, I will focus on operational and commercial highlights, as well as priorities for the next quarter.
I will now introduce each aspect in conjunction with the KPI slides.
In terms of space business, we remain the world’s leading launch service provider, carrying the vast majority of mass-to-orbit payloads. In the third quarter, we completed 35 launches, including: 21 Falcon 9 Starlink launches, 2 Starship launches, 1 Falcon Heavy launch (to be detailed later), and 12 high-profile commercial customer missions—among them, the launch of NASA's Roman Space Telescope into deep space using Falcon Heavy. We also executed 6 national security space launch missions.
In new business, we successfully secured 3 additional crewed Dragon spacecraft missions extending to 2028; we also signed a Starlink communication contract for NASA's Artemis 3 mission, 18 new national security space launch contracts, a contract for delivering payloads to the lunar surface using Starship, and 3 new Starship Starfall missions. By the way, we just completed a Falcon 9 Starfall mission today. Starfall is our space capsule that provides regular, relatively low-cost access to microgravity environments for scientific research, helping to advance research on diseases such as cancer and diabetes, and providing optimized medical solutions for patients on Earth.
In the last week of the quarter, we completed the orbital mission of Starship's 14th flight (as Elon mentioned). Then on October 1, we achieved another feat—executing three Falcon missions at three Falcon launch sites in just 13 hours: safely delivering Crew 13 to the International Space Station, a Falcon Heavy NRO mission, and a rideshare launch carrying 130 payloads. This fully demonstrates SpaceX's strong capability to simultaneously deliver crewed, commercial, and national security missions within a single day.
We are equally excited about the future of Starship—delivering large payloads to orbit, other planets, and the Moon, collectively building a space economy. As Elon said, the 14th flight of Starship is an important technological milestone. We are still on track to achieve our goal of recovering both the booster and upper stage to the launch pad this year, completing the re-flight verification of the upper stage early next year, and continuously increasing launch frequency, moving towards rapid full reusability. We plan to conduct in-orbit refueling experiments early next year and begin launching mobile V2 and Starmine satellites in 2027.
We have had productive in-depth communications with the Federal Aviation Administration (FAA), and we expect the license for the 15th flight to cover the return to the launch site and the recovery of both stages at the launch pad. I am also incredibly excited about expanding Starship operations to Louisiana—this "second Louisiana purchase" aligns perfectly with Starship's bright future in terms of geography, community atmosphere, and local work spirit.
Regarding Starlink, driven by the continued growth of consumer, enterprise, and government business, this quarter has once again performed impressively. As of the end of the quarter, we have commenced operations in 174 markets, including new markets such as Vietnam and Uganda.
In terms of user growth, we added 1.6 million consumer users this quarter, bringing the total global broadband consumer subscriptions close to 14 million. Notably, this figure does not include several hundred thousand additional enterprise subscription users and aviation customers.
The profound impact of Starlink on global communities continues to inspire us, including serving hundreds of thousands of students and teachers in schools worldwide and providing emergency support during natural disasters. In the third quarter, Starlink's rapid response capability supported 25 crisis rescue efforts, including earthquakes in Venezuela and western Colombia, as well as Hurricane Lowell in Hawaii. In Venezuela alone, Starlink donated over 1,400 sets of equipment to emergency agencies, providing critical broadband connectivity to over 250,000 people.
As mentioned last quarter, there is still significant growth potential in enterprise and government business, with aviation business continuing to be an important breakthrough point, and fixed-site business also accelerating. Starlink has currently signed agreements with about 12,000 aircraft, covering about a quarter of available flights, and is continuously expanding cooperation with both new and existing customers. We have signed agreements with three of the four major U.S. airlines while also expanding partnerships with international airlines.
This quarter, Lufthansa, Swiss International Air Lines, Avianca, Korean Air, Austrian Airlines, and Asiana Airlines all completed operations with their first Starlink-equipped aircraft. To keep up with this demand, we have quadrupled our aviation product capacity this year and expect to double it again by the end of the year.
Feedback from aviation partners indicates that Starlink has become an important reason for passengers to choose their flights—whether it’s business travelers increasingly reliant on full connectivity or ordinary travelers wanting to stay online anytime, anywhere. Our data shows that flights equipped with Starlink have higher seat utilization rates, and full connectivity is rapidly becoming a basic expectation for passengers.
In government business, Starshield continues to provide unique critical mission capabilities, and we believe there is still significant growth potential. We expect that enterprise and government revenue will surpass consumer connectivity revenue in the future.
The successful deployment of operational V3 broadband satellites during Starship's 14th flight marks an important turning point for Starlink. The capability enhancements brought by this batch of satellites, combined with the Starship launch platform itself, will provide greater capacity to various markets and open up new business opportunities in high-demand areas.
We expect the growth of the communication market to far exceed the scope of traditional human communication. The connectivity of automobiles, the interconnection of robots, and the proliferation of superintelligence will cause communication demand to grow by orders of magnitude rather than by percentages. In the coming years, Starlink alone is expected to account for a significant share of global internet traffic.
In terms of mobile business, in the third quarter, we continued to expand international cooperation, launching services with operators in several countries including Uganda, the Democratic Republic of the Congo, Kazakhstan, and Costa Rica. By the end of the quarter, Starlink's mobile monthly active users surpassed 22 million, a quarter-over-quarter increase of 37%. Our recent priority is to continue launching the mobile version of the V2 constellation next year and to integrate our spectrum assets to enable service launch in early 2028. A few weeks ago, we received FCC approval to launch 15,000 mobile V2 satellites and announced the acquisition of a batch of low-frequency spectrum assets, laying the foundation for Starlink Mobile to become a major mobile operator in the United States.
In terms of superintelligence, the industry's demand for large-scale computing power remains strong. We are rapidly expanding our computing power to meet the internal demand for Grok and related products at scale, as well as the needs of external cloud service customers. Feedback from enterprise customers on recent model releases has been positive, with particularly strong market adoption of Grok Bot. Grok Bot (our intelligent assistant) went live in August and had 800,000 paid weekly active users by the beginning of this month, doubling from the previous month. B2B is the fastest-growing business category, with more and more enterprises using Grok Bot as a force multiplier in sales, marketing, IT, and engineering, viewing it as an all-weather team member for tackling complex end-to-end workflows.
We are also accelerating the release pace of Grok models, having recently achieved significant performance improvements, with ongoing optimizations planned. Meanwhile, the integration work for Cursor is progressing smoothly, further enhancing our product capabilities and scaling enterprise sales outreach. This momentum has preliminary evidence: the number of Grok enterprise customers with annual operating revenues exceeding $1 million, including Cursor, has increased by 50% compared to the previous quarter. Last week, we further integrated our product portfolio, launching a new plan that combines Grok, Grok Bot, Cursor, and X Premium into one package.
Overall, our business is showing strong development momentum across all three major segments. The engineering team continues to advance the scaling process of Starship and the next-generation satellites (covering broadband, mobile, and Starshield), while the commercial team continues to drive Starlink expansion in aviation, enterprise, government, and global markets. At the same time, leveraging our hardware expertise, we are accelerating the expansion of our superintelligence business in the critical computing power infrastructure sector. Now, I would like to invite Bret to speak.
Chief Financial Officer Bret Johnsen: Thank you, Gwynne. In the third quarter, we once again delivered impressive results.
Revenue grew significantly by 161% year-over-year to $14.6 billion, driven by the continued strong momentum in the connectivity business and a clear inflection point in the superintelligence (SI) business. EBITDA growth once again outpaced revenue growth, reaching $8.8 billion, a year-over-year increase of 306%.
Our leading position in the launch sector, the recurring revenue from Starlink, and the substantial expansion of the SI infrastructure business collectively drove significant operational leverage for the business. Our balance sheet remains very robust, and our focused capital allocation allows us to maintain an accelerated pace of innovation, providing strong support for significant revenue opportunities across the three major business segments.
Next, I will introduce the financial situation by business segment.
Space business revenue was $1.8 billion, an 84% quarter-over-quarter increase and a 6% year-over-year increase, benefiting from a favorable customer mix. Based on the strong customer mission pipeline for Falcon and Dragon, we expect to achieve steady growth for the full year.
In terms of capital allocation, we continue to invest in the Starship project, accelerating the production of Raptor engines and spacecraft, advancing Gigabay construction, and simultaneously progressing with the construction of multiple launch pads at the interstellar base and Cape Canaveral. Additionally, we have identified the next phase of development for U.S. space launch capabilities—Louisiana. These investments are crucial for achieving the leap in cost and capacity that Starship brings.
The connectivity business once again achieved strong revenue growth and profitability, with revenue of $5.2 billion, a year-over-year increase of 69% and a quarter-over-quarter increase of 22%. As Gwynne mentioned, our Starlink consumer subscription users reached 13.6 million, adding 1.6 million in just the third quarter, with growth primarily coming from mature markets. This quarter, we initiated the ramp-up of the V5 suite's production capacity, effectively alleviating inventory tightness. We strategically managed channel distribution, prioritizing retail channels to prepare for the holiday season, which is expected to drive an increase in activations in the fourth quarter.
Starlink consumer average revenue per user (ARPU) increased by 5% quarter-over-quarter to $69 per month, benefiting from a favorable customer mix during the quarter. Revenue from enterprise and government customers grew by 91% year-over-year and 18% quarter-over-quarter, primarily driven by growth in the U.S. government's Starshield project and the continued strong momentum in the aviation sector. The aviation business remains an important growth opportunity, as we are still in the early installation phase with several large airlines globally and have a clear forecast for the accelerated activation path of major partners in 2027.
The gross profit of the connectivity business doubled year-over-year, with a gross margin of 55%, which includes about 3% of one-time benefits, primarily from tariff refunds this quarter. Excluding one-time factors, the adjusted EBITDA profit margin still improved by about 2% year-over-year.
Looking ahead, the satellite roadmap is the core driver of capacity and capability for the connectivity segment. From the end of this year through all of 2027, we expect each Starship launch to deploy a large number of V3 broadband satellites, with each launch's payload providing more than 20 times the downlink capacity of the current Falcon 9 launches. At the same time, we will start launching Starlink Mobile V2 satellites on Starship in 2027 and leverage our newly acquired wireless spectrum assets to expand direct-to-terminal services, as Gwynne mentioned, to become a major mobile operator in the United States. The launch cadence of Starship is expected to bring a leap in total capacity, coverage, and service quality across Starlink broadband, Starlink Mobile, and Starshield.
Superintelligence (SI) once again became the standout growth engine this quarter. Segment revenue surged to $7.6 billion, an increase of $5 billion quarter-over-quarter and $6.7 billion year-over-year, primarily driven by the rapid rollout of cloud service agreements. As new computing power is put into commercial operation, we have significantly improved the profitability structure of the segment, achieving strong operational leverage.
As of the end of the third quarter, our nameplate computing power was 1.7 GW, with more data centers going live in early October.
Revenue from SI solutions and infrastructure was $7 billion, which includes approximately $608 million contributed by Cursor, acquired mid-quarter. Even excluding Cursor, SI solutions and infrastructure revenue still grew by 192% quarter-over-quarter, primarily driven by the activation of new cloud service agreements. There is currently a large demand for computing power from customers, and we are actively expanding supply to meet internal and external needs, expecting to continue expanding new customers and new contracts in the future. We will continuously assess the optimal high-margin uses of computing power assets between new and existing cloud service agreements and our own SI product inference services.
The current market demand situation is rare—at current pricing levels, the payback period for new computing power investments is less than a year. The current pricing per watt is slightly above the upper limit of the $30 to $50 range we discussed last quarter, further highlighting the attractiveness of these ground-based superintelligence computing power investments. We will continue to be demand-driven, maintaining a prudent pace in computing power deployment, closely matching capital planning for semiconductor supply with recent customer demand.
Our current SI computing power customer contracts allow us to flexibly manage computing power assets, which can be used for both our own model training and for generating revenue from cloud service agreements when market supply tightens and prices are favorable. Advertising revenue grew by 19% year-over-year, benefiting from the growth momentum brought by our new advertising technology platform launched in the previous quarter (Q2).
The adjusted EBITDA for the SI segment was $5 billion, an increase of $3.8 billion quarter-over-quarter and $5.4 billion year-over-year, primarily driven by high-margin cloud service agreements. The operating profit for the SI segment was $431 million; however, excluding the $1.2 billion stock-based compensation expense related to the Cursor acquisition, the segment achieved an operating profit of $1.6 billion in Q3 alone.
To further clarify the stock-based compensation expense related to the $6 billion equity value of Cursor: at the time of acquisition, $2.3 billion was allocated to retain key employees and replace unexercised equity awards (including re-vesting agreements for key management personnel), which will be recognized as stock-based compensation over a vesting period of approximately three years.
The company's total capital expenditure for the third quarter was $19.6 billion, primarily for SI computing power construction, Starship infrastructure, and satellite production.
As of September 30, our total backlog reached $63 billion, of which $17.5 billion is recognized as deferred revenue, and approximately $42 billion of the backlog is expected to be recognized within the next year.
Looking ahead, demand across all three business segments remains strong, especially in the cloud service business—we expect to achieve the previously announced goal of reaching an annualized revenue of $100 billion by the end of this year, based on December's monthly revenue. The ongoing rollout of SI infrastructure in Memphis and South Haven gives us a clear forecast for the accelerated construction path for the remainder of this year.
Therefore, we expect that in just October alone, nameplate computing power could approach 2.2 GW; and as Elon emphasized, by the end of this quarter, nameplate computing power is expected to reach the range of 2.5 to 3 GW. With more computing power coming online this quarter, we expect fourth-quarter capital expenditures to be in the range of $35 billion to $40 billion. We also anticipate that the overall gross margin for the company in Q4 will be comparable to Q2, as some one-time benefits and customer mix factors from Q3 have already been explained.
Given the increased visibility of the computing power contract pipeline over the next six months, we are conditionally providing additional forward guidance on the business acceleration trend. We expect the company's revenue in Q1 2027 to be in the range of $33 billion to $37 billion.
In summary, the company's financial situation is undergoing a profound transformation. We are actively investing in three key areas: SI computing power, Starship research and production, and the next-generation Starlink broadband and mobile constellations, which we believe are the areas with the highest long-term returns. These are demand-driven investments, and the markets they are in have clear and visible returns in the near term.
We are building future infrastructure with a rigorous attitude, focusing on capital efficiency, strong investment capital returns, and seizing current opportunities with sufficient execution speed while maintaining a robust investment-grade balance sheet. A diversified profit structure, extreme vertical integration capabilities, and strong market demand for superintelligence collectively support our confidence in the future development path.
Now, I will hand it back to Andrea.
Q&A Session
Head of Investor Relations Andrea Williams: We will first take questions from equity analysts. The first question comes from Adam Jonas of Morgan Stanley.
Adam Jonas (Morgan Stanley):
Hello everyone, can you hear me? Very good. First, Elon, thank you for making flying cars a reality; that is truly crazy and incredibly inspiring for the world, especially for young people with aspirations to create.
I have a two-part question about TerraFab: you want to manufacture chips domestically or in secure and controllable locations, and the production scale needs to be quite substantial. Has SpaceX ordered EUV lithography machines? If so, when is the expected delivery?
Additionally, when you examine the semiconductor foundry supply chain from first principles— I know you have looked into companies like TSMC, ASML, AMD, and Lam Research, all of which are outstanding companies— when you approach it in your way, where do you think the greatest room for improvement lies?
Elon Musk:
We are still in the exploratory phase of chip manufacturing. But I can share our internal target expectations, which of course come with considerable uncertainty, as we are not sure if we can achieve them.
Our internal goal is to complete the first test chip by May or June next year, possibly a SRAM or a similar basic validation chip for testing the production line, located at our research lab in Austin. Our vision is to achieve mass production at the TerraFab main plant in Gibbons Creek by the third quarter of 2028. This is a very aggressive timeline, and we are very grateful to ASML and all our suppliers for their efforts to expedite equipment delivery. Tentatively speaking, achieving mass production in the third or fourth quarter of 2028 is at least within the realm of possible outcomes.
These timelines are obviously almost crazily fast. I believe we may indeed have several significant breakthroughs in chip manufacturing, but this is not suitable for disclosure in an earnings call. However, I am optimistic that we can significantly accelerate chip production and believe that TerraFab will ultimately live up to its name— producing terawatt-level super-intelligent chips annually.
Andrea Williams: The next question comes from Doug Anmuth at JPMorgan.
Doug Anmuth (JPMorgan):
Thank you. Elon, could you elaborate on how you plan to overcome constraints related to power, cooling, and infrastructure, and where your confidence in reaching 13 GW by the end of next year comes from? Additionally, Bret, could you help us understand the corresponding financing needs?
Elon Musk:
About 3 GW, or close to 3 GW, is the portion we expect to complete in the coming months. Everyone just needs to focus on the speed at which we are actually deploying and bringing online computing power.
As far as I understand, other hyperscale cloud providers rarely disclose the actual number of GPUs brought online each month, but we will be very transparent about this data. Deploying 220,000 GB300s each month and providing power, electrical equipment, cooling, batteries, networking, and all supporting infrastructure is indeed an extremely daunting task, but that is exactly what we are doing, and the pace will further accelerate next year.
Regarding how to solve the power issue, I cannot go into detail, as this is highly confidential information, and once disclosed, others may rush to imitate. I can only say that we have a plan, and if everything goes smoothly, we will add 20 GW of power and cooling capacity next year, plus what we already have this year, totaling about 23 GW. But in reality, not everything can go smoothly, so I am speaking of a highly confident 10 GW, while 20 GW is difficult but not impossible.
One initiative I have publicly mentioned is casting blades and guide vanes for gas turbines. SpaceX already has extremely advanced casting capabilities—developed for rocket engines, which I believe is the most advanced casting technology on Earth, as rocket engines have requirements for castings that far exceed any other application. Transitioning this team with the world's most advanced casting technology to manufacture blades for ground gas turbines is relatively easy compared to their previous challenges.
We learned from gas turbine suppliers that the delivery cycle for blades and guide vanes is 12 to 18 months longer than for other components, meaning they can deliver all components except for blades 12 to 18 months in advance. Casting is a real bottleneck, and it seems to be worsening. This means we can bring power online 12 to 18 months ahead of anyone else—this competitive advantage is extremely difficult to replicate unless someone starts a new advanced foundry from scratch, which cannot compete with SpaceX in this regard.
We are also exploring various power sources beyond gas turbines, including solar, wind, and all available energy sources. Additionally, we believe there is a significant opportunity in inference computing—if we manufacture modular inference computing units at the factory level, with built-in power and cooling systems, and then deploy them in a distributed manner across the country and even globally, efficiency will greatly improve.
In summary, I am highly confident about adding 10 GW of computing power next year (totaling 13 GW), and the probability of breaking through 20 GW is also rising rapidly.
Bret Johnsen:
Doug, regarding financing, our advantage lies in having an investment-grade credit rating and a robust balance sheet, and we are currently engaging with multiple sources of debt capital. Another important factor is that the payback period is very short, which means this capability can quickly become self-sustaining. Even the newly added computing power this quarter will start supporting financing in the first half of next year.
Therefore, first is operational cash flow, followed by the diversified debt market financing channels brought by our investment-grade status and strong balance sheet, as well as collaboration opportunities with suppliers and customers across the entire value chain. What SpaceX does is never easy, and financing challenges are no exception. But we are very confident that we can proceed steadily in a prudent manner while maintaining our investment-grade credit rating throughout the process.
Elon Musk: From our capital efficiency record on Starship and all projects, it is hard to find another company globally that can match SpaceX.
Bret Johnsen: I completely agree.
Andrea Williams: The next question comes from Edison Yu at Deutsche Bank.
Edison Yu (Deutsche Bank):
Thank you, I also want to express my admiration for the Roadster. Recently, there has been a lot of reporting and speculation in the market about the possibility of a merger between SpaceX and Tesla. I know you may have some restrictions in your statements, but from a macro perspective, how do you view the pros and cons of a potential merger? Are there obstacles that need to be addressed before moving forward?
Elon Musk:
This question makes me feel like I’m dancing on a minefield, needing to be very careful with my wording.
Both SpaceX and Tesla have established special committees at the request of shareholders to specifically discuss this issue, with committee members being independent directors. Since I am a stakeholder, I cannot participate in the discussions of the special committees, so this is a peculiar situation—two groups of people are negotiating, and I cannot be part of it.
I believe that the merger of SpaceX and Tesla should not be seen as a foregone conclusion; some people may be overly optimistic. Personally, I think it is a good idea, but it ultimately depends on shareholder support, especially on the Tesla side, where we need to obtain support from over 50% of all shareholders (not just voting shareholders), which is quite a high bar.
Currently, the special committees of both companies have not reached an agreement on any transaction terms, nor can we guarantee that an agreement will ultimately be reached. However, I do believe that in the context of being in the era of superintelligence singularity, a merger would be significant—collaboration between the two companies would be beneficial in areas such as superintelligent software development, chip design, TerraFab, robotics, quality assurance capabilities, and the Starmine constellation, as well as communication connections. But this ultimately depends on the special committees of both companies reaching a plan and submitting it for shareholder voting.
Andrea Williams: The next question comes from Kutgun Maral at Evercore.
Kutgun Maral (Evercore):
Thank you. I would like to ask about Starlink mobility. Recent low-band spectrum acquisitions have made significant progress, but there is still some uncertainty from the outside— even as spectrum assets continue to improve, it is unclear how they can compete with existing operators in the U.S. market. One key point that we do not understand well is how much coverage and capacity the satellite layer can provide to bridge the gap between ground networks and peers. What roles will satellites and ground networks each play? How do you view the traffic distribution between the two and the ability to provide a 5G-like experience? More broadly, is the focus of the connectivity business on traditional retail wireless communication, or the huge opportunities brought by physical AI?
Andrea Williams:
I will answer first, and Elon can add details. It should be noted that a significant proportion of mobile data connections—about 85% to 93%—are completed through Wi-Fi, and Starlink broadband also handles a large number of Wi-Fi scenarios.
In terms of spectrum structure, we expect the S band to carry most of the traffic; while the low-band spectrum (800 MHz) is crucial for signal penetration within buildings— users can still receive signals in non-Wi-Fi scenarios. Additionally, last quarter we mentioned a plan: deploying small radio units at homes, commercial locations, and towers where Starlink devices are installed, fully utilizing Starlink's on-site installation assets. Therefore, the available spectrum is not limited to just the S band and low-band spectrum; we will comprehensively utilize the on-site resources of Starlink installations and other towers.
Elon Musk:
I think we should arrange a more detailed presentation specifically discussing the overall plan for Starlink connectivity and why we believe this will ultimately become a business generating hundreds of billions of dollars in revenue annually. There is still much internal information that has not been fully communicated. I do believe we have a clear path to achieving hundreds of billions in revenue from the connectivity business each year, but the specific planning details are not suitable for elaboration in the few minutes of an earnings call; we should arrange a separate session to explain in detail.
Andrea Williams: We only have three minutes left.
Elon Musk: I think we can talk a bit longer.
Andrea Williams: The next question comes from Eric Sheridan at Goldman Sachs.
Eric Sheridan (Goldman Sachs):
Thank you very much. In the context of computing power deployment, how do you find a reasonable balance between external cloud service opportunities and the internal computing power needed for scaling Cursor, Grok, and Grok Bot? How has your thinking on this balance evolved over the past 12 to 18 months? From a monetization perspective, what output might this combination bring to the business?
Elon Musk:
The allocation of computing power between third-party and internal will change dynamically over time. Roughly speaking, our goal is to have it be about fifty-fifty—half for internal use and half for external rental, but this ratio may fluctuate between sixty-forty, with no fixed direction.
We prefer to rent at spot market pricing rather than signing long-term contracts. Our judgment is that the value per watt of computing power will rise over time rather than fall— the reason is simple: as AI software continues to improve and models are optimized, the effective intelligent value generated per watt of computing power is also increasing, and this value is the fundamental support for computing power pricing. This also explains why even "old" models like the H100 have rental prices that are even higher than when they were first released, and I believe this trend will continue.
The supply gap for superintelligent computing power will exist for a long time, so betting on the continuous increase in effective value per watt of computing power with short-term contracts is a wise move— and the facts have validated this judgment. From the contract renewal situation, we see that the price per watt in dollars is rising, not falling.
Honestly, we are being pursued almost daily by major cloud service providers and dozens of small to medium-sized companies wanting to rent more computing power—if we agreed to all of them, our computing power could be rented out several times over. This is the reality, much like Monty Python's "Cheese Shop" sketch: that shop actually has no cheese, and customers ask about various kinds, but end up with nothing.
We even tried subcontracting some of our inference computing power to other cloud service providers to free up more resources for training, but the result was the same—no GB300, no GB200, no TPU, perhaps some H100 overseas, but after checking, they said there were none left. It’s truly absurd.
In short, I believe we will not have issues on the demand side. I’m not saying this will definitely happen, but it’s possible that the payback period for computing power investments could shorten to six months next year.
Andrea Williams:
Next, we will move on to questions submitted by individual investors on the public Q&A platform.
Since we talked a lot about ground computing power deployment earlier, let’s look at a question about the V3 satellites: When will the capacity gains from the V3 satellites truly translate into higher speeds and lower latency that users can perceive? How many V3 satellites are needed for users in high-demand areas to noticeably feel the network improvements?
Gwynne Shotwell (President and COO):
I think it will take several hundred V3 satellites for users to really feel a noticeable improvement. Currently, the number of satellites is very limited, and users may occasionally experience enhancements, but then revert back after a few minutes. I believe several hundred satellites is the threshold, and we expect to reach that number by mid-next year.
Andrea Williams:
The sixth question: Can you provide an update on the Louisiana Starbase? What is the timeline? How confident are you about achieving the first launch of Starship from that base (as early as 2029)?
Elon Musk:
Our internal goal is actually to achieve the first launch within two years, which is 2028, but I think 2029 is very achievable. By 2029, I am highly confident that Louisiana will achieve scaled launches.
Andrea Williams: Are we all ready to wrap up?
Gwynne Shotwell: Okay.
Andrea Williams: Thank you all for participating. This concludes the Q3 2026 earnings call, and we’ll see you next quarter.
Bret Johnsen: Thank you, everyone.
 Risk warning Risk warning