Is the U.S. stock market weakening the cryptocurrency market cycle?
 Core Viewpoint

 Native tokens will no longer monopolize on-chain capital; a cryptocurrency market that does not have to be rebuilt every four years may be the most profound significance of tokenization for this industry.
Author: Zhou, ChainCatcher
On October 15, OKX and ICE's joint venture tokenized stock platform OKXICE announced that among the 63 U.S. stocks planned for launch, nine listed companies including Verizon, Broadcom, and UnitedHealth have opposed based on the SEC's new regulations, meaning these stocks will not be tradable on the platform.
At the same time, Nasdaq also stated that it would not allow its stocks to be tokenized under this framework.
This is the first time since the SEC introduced the innovative exemption in September that listed companies have collectively exercised their veto rights. What does tokenization mean for U.S. stocks and the crypto market?
1. The Costs of Tokenizing U.S. Stocks Begin to Emerge
According to the innovative exemption released by the SEC on September 17, on-chain tokenized securities trading venues do not need to register as exchanges to trade already issued U.S. stocks. Third-party tokenization does not require prior consent from the listed companies but must provide written notice in advance. If the listed company raises an objection within 30 days, the stock cannot be traded at that venue.
OKXICE is the first venue to issue an opening announcement based on this rule. According to its announcement, the platform is deployed on X Layer, using a Uniswap v4 liquidity pool with access control, pairing stocks with stablecoins like USDC, USDG, and USDT for 24/7 trading. The price in the pool is determined solely by the ratio of the two assets, without using oracles, and there are no circuit breakers except for trading halts. The announcement also acknowledges that token prices may deviate from the underlying stocks, especially outside regular trading hours.
For listed companies, this means their stocks will enter a market where they cannot control pricing. Among the nine companies that opposed, CoreWeave, AppLovin, and Applied Digital are popular AI and retail investor stocks, which are also the targets crypto traders most want to trade.
Nasdaq's reasoning is more direct; it does not want its stocks traded in a venue that cannot display optimal prices in real-time and does not report transactions to comprehensive market systems. It is worth mentioning that Nasdaq itself is a competitor of ICE, the parent company of the New York Stock Exchange, which was approved by the SEC in March to trade stocks in tokenized form.
Market views suggest that the bottleneck for Real World Assets (RWA) lies in authorization, specifically who is qualified to turn the economic rights of a stock into an on-chain token. The opposition from these nine companies is precisely about this right.
Just last weekend, the market experienced a flash crash. Around 5:22 AM Beijing time on October 18, during the U.S. stock market's closure, perpetual contracts for U.S. stock AI concept stocks on crypto platforms suddenly plummeted.
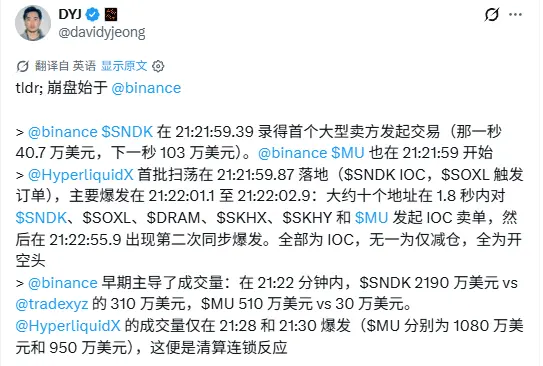
DYJ, CEO of the trading execution platform Tread.fi, stated that the flash crash sell-off began at Binance, with the SNDK contract seeing large active sell orders first, executing about $407,000 in the first second and about $1.03 million in the next second. Less than a second later, there were sweep orders on Hyperliquid, with about 10 addresses concentrating on selling six contracts, including SNDK, MU, and SOXL, all opening new short positions. About six minutes later, the trading volume of the MU contract on Hyperliquid surged to about $10 million per minute, which DYJ attributed to chain liquidation.
The MU contract on Binance briefly dropped to $818.57, down about 6% from before the flash crash, and then recovered most of the losses within an hour.
Real shareholders' accounts were unaffected over the weekend; it was those using leverage to trade these contracts that were liquidated. Although prices have returned, their positions have exited.
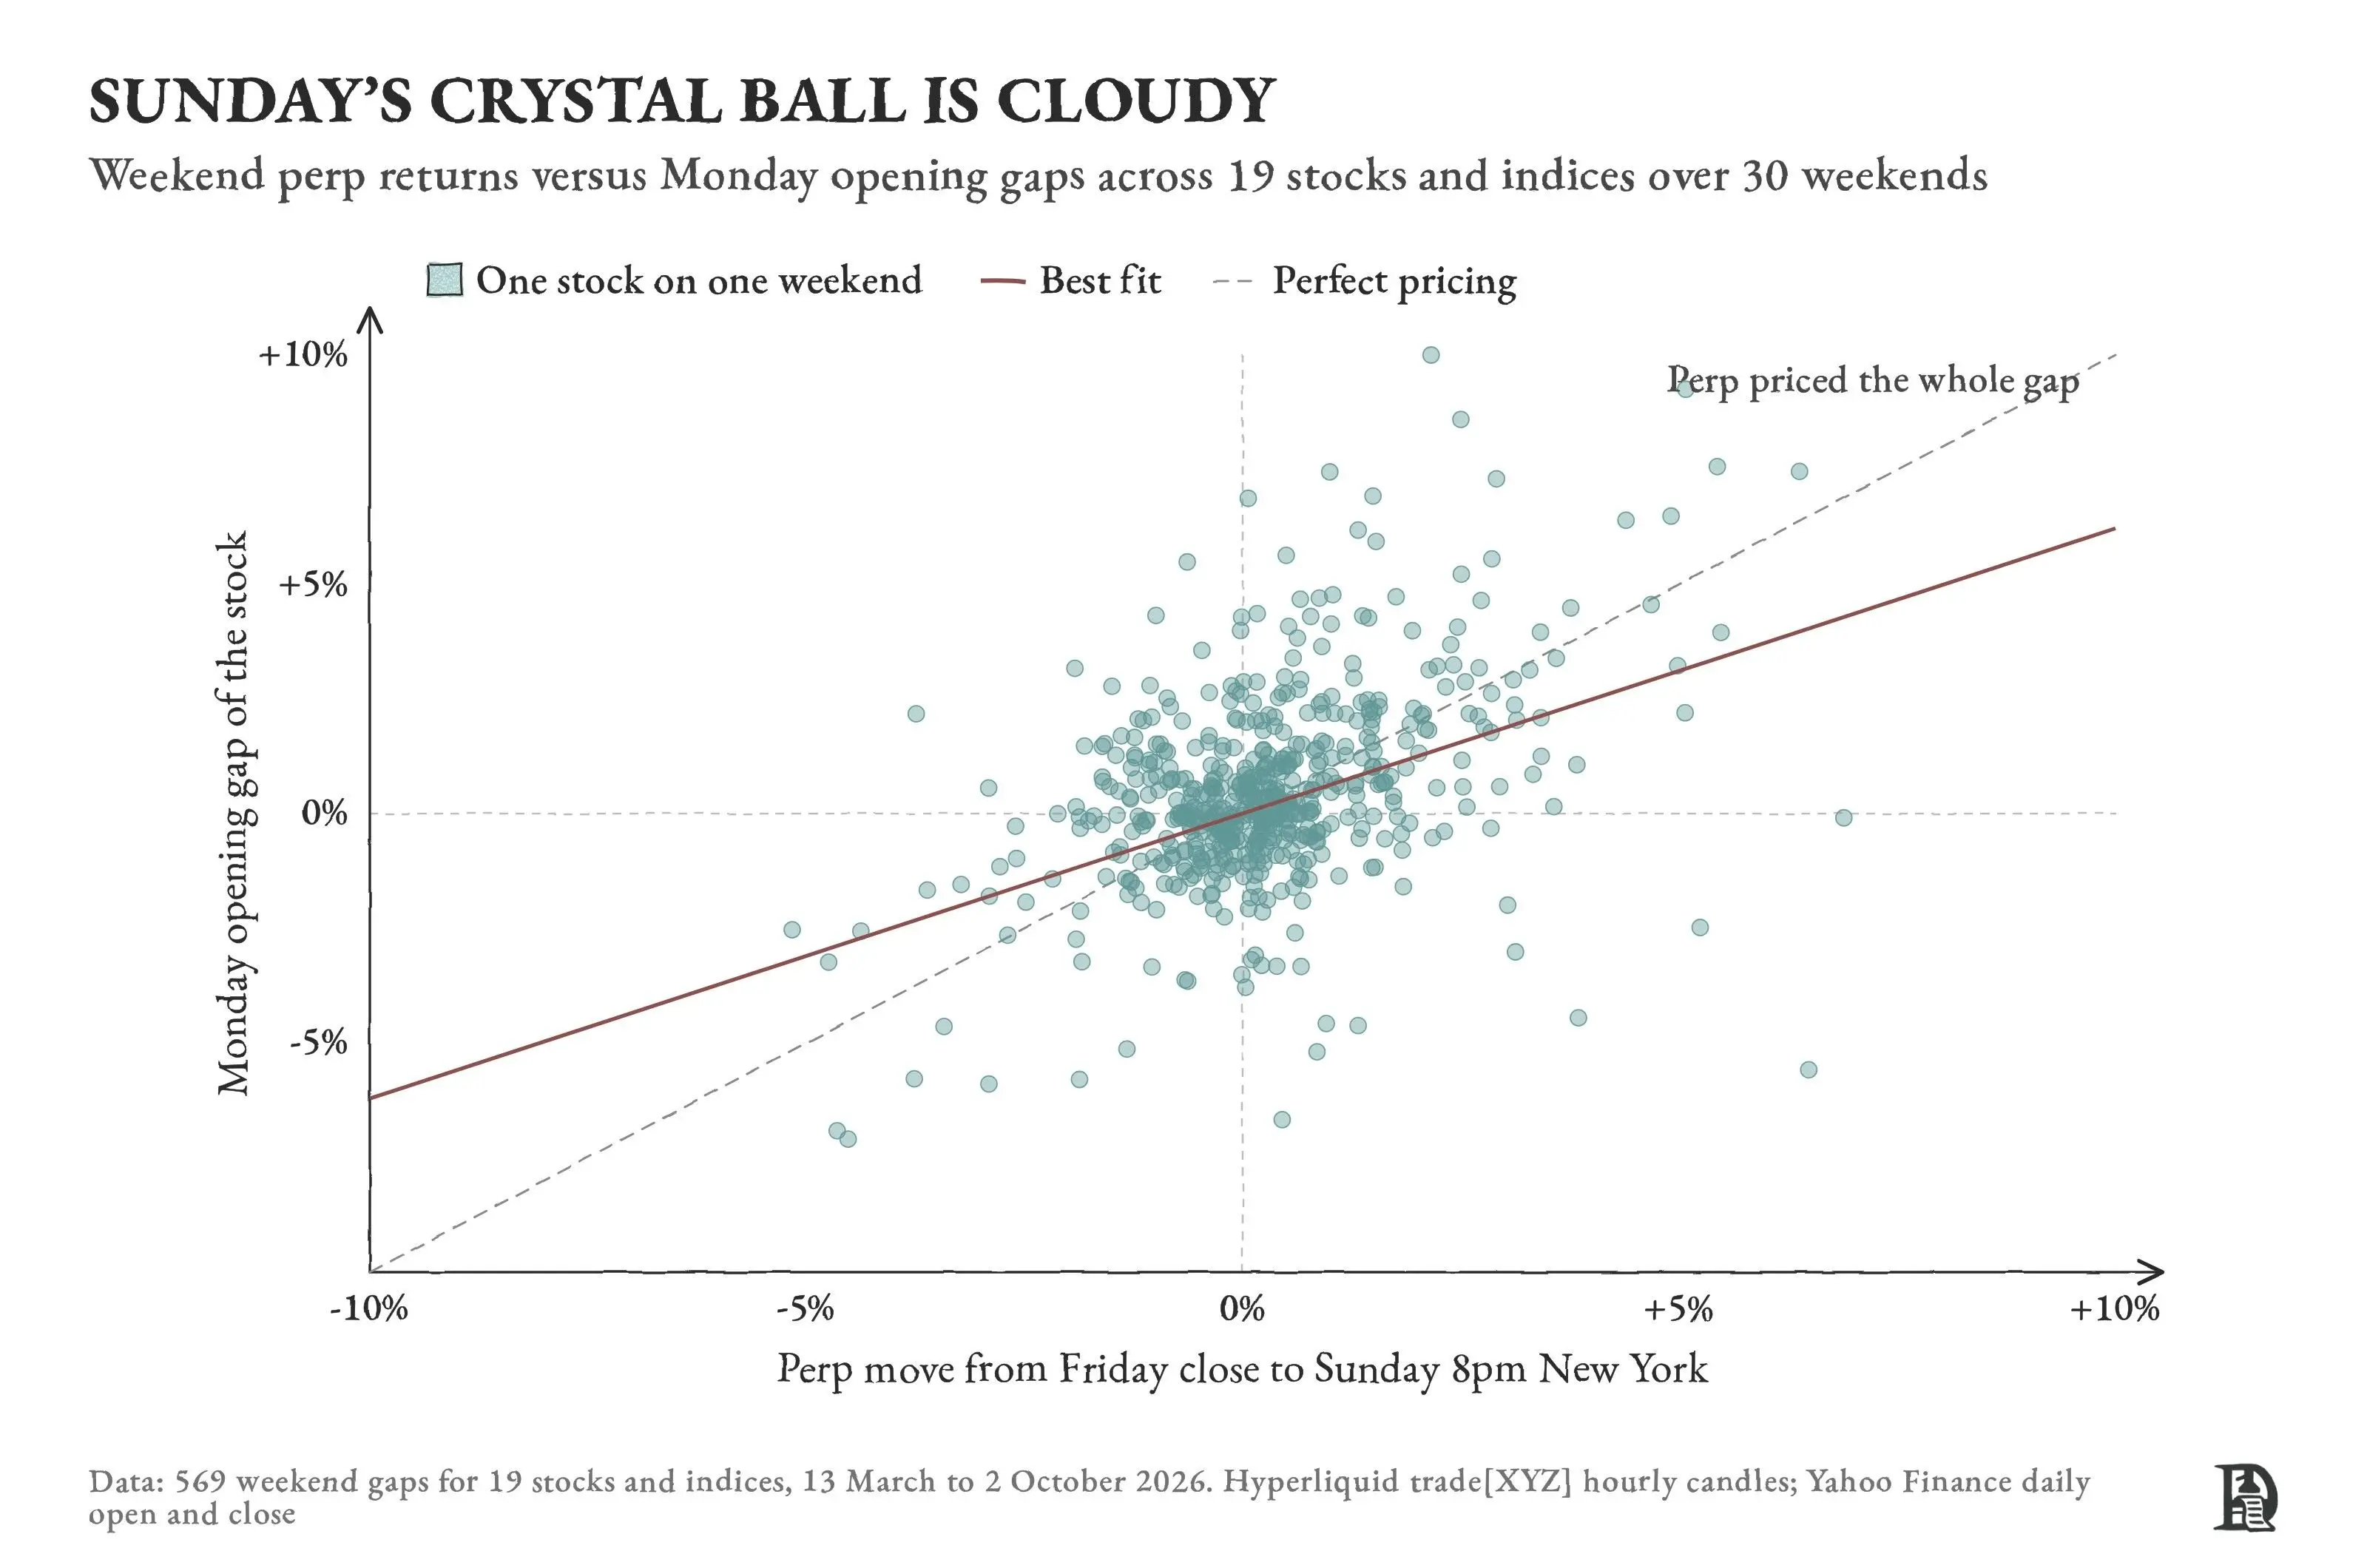
The weekend itself is the weakest period for tokenized U.S. stocks. According to a post by Decentralisedco comparing data from 30 weekends since March, it was found that when the opening gap on Monday exceeds 1%, the accuracy rate for predicting the direction of perpetual contracts is 69%, but by Sunday night in New York, it only reflects about a quarter of the gap.
Thin trading and inaccurate pricing, combined with leverage and liquidation mechanisms, amplify the impact. The IMF pointed out in its October Global Financial Stability Report that the volatility of tokenized stocks is about 1.5 times that of the corresponding stocks. IMF financial advisor Tobias Adrian believes that the inefficiencies that tokenization attempts to eliminate serve as shock absorbers in traditional markets. The weekend market closure is precisely such a buffer.
2. Is the U.S. Stock Market Weakening the Crypto Market Cycle?
Over the past decade, Bitcoin's price has generally followed a four-year cycle formed by halving events. In previous bear markets, Bitcoin's decline from its peak has ranged from 77% to 93%.
The cost of a bear market is not only reflected in prices; large amounts of capital exit the market, and the industry often has to wait for the next bull market to re-gather funds and popularity.
This round's rhythm has not changed; Bitcoin is expected to peak at around $126,000 in October 2025, about 540 days from the halving in April 2024, consistent with historical patterns. However, the volatility has clearly decreased. On June 5 of this year, Bitcoin dropped to about $59,100, a retracement of about 53%, and has gradually rebounded, recently returning to around $85,000.
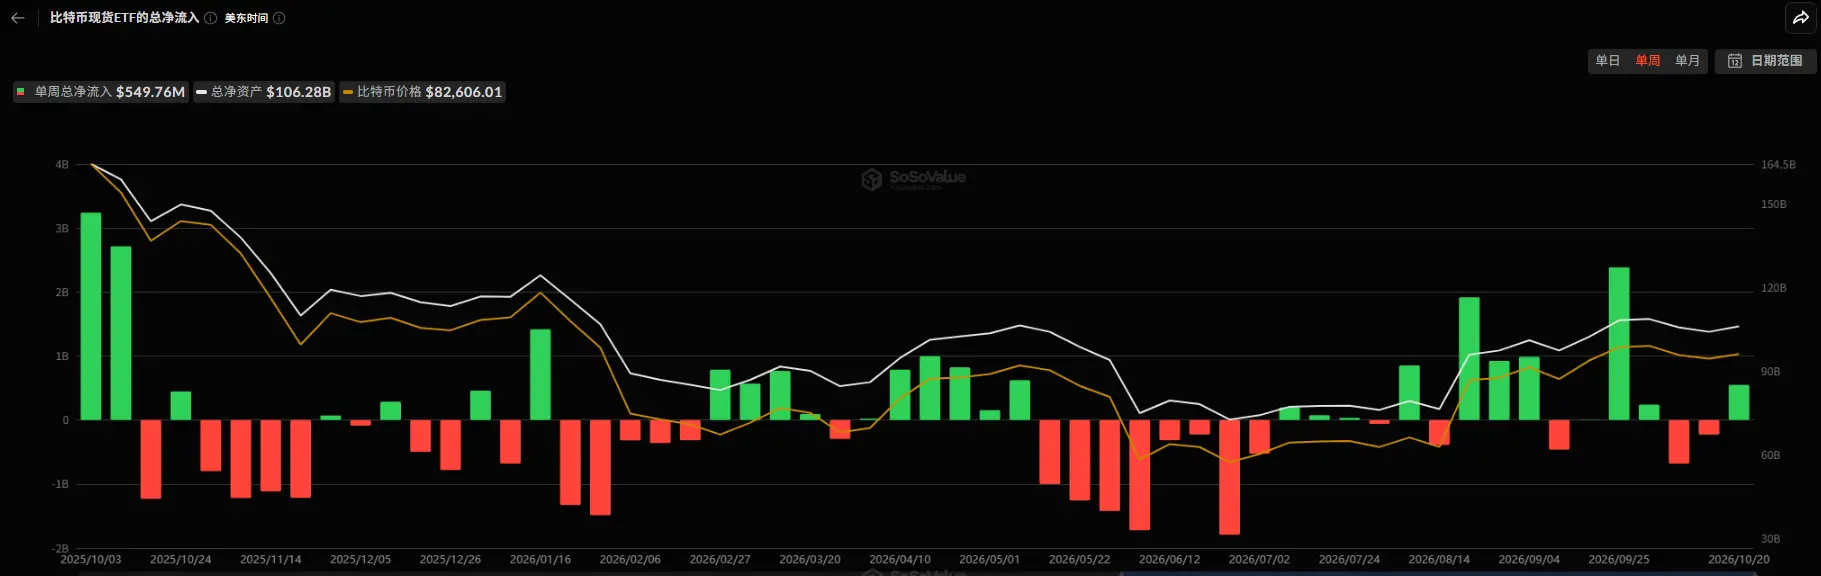
The shallower decline first depends on who is supporting the price. Regarding Bitcoin spot ETFs, according to SosoValue data, from November 2025 to June 2026, the net outflow from ETFs totaled about $10 billion, with a single-month outflow of about $4.5 billion in June when Bitcoin bottomed, and a net inflow of about $6.3 billion during the rebound from July to September.
In terms of Bitcoin treasury companies, according to statistics from BitcoinTreasuries.net, the selling volume of listed treasury companies exceeded the buying volume as of February this year, with almost only Strategy continuing to buy. According to its filings with the SEC, Strategy's Bitcoin holdings increased from about 650,000 coins at the end of November 2025 to 843,775 coins in late June 2026, an increase of about 194,000 coins. In January of this year, Strategy alone accounted for 97.5% of the net increase in holdings by listed companies. However, Strategy paused its purchases after the week of June 22 and shifted to accumulating dollar reserves.
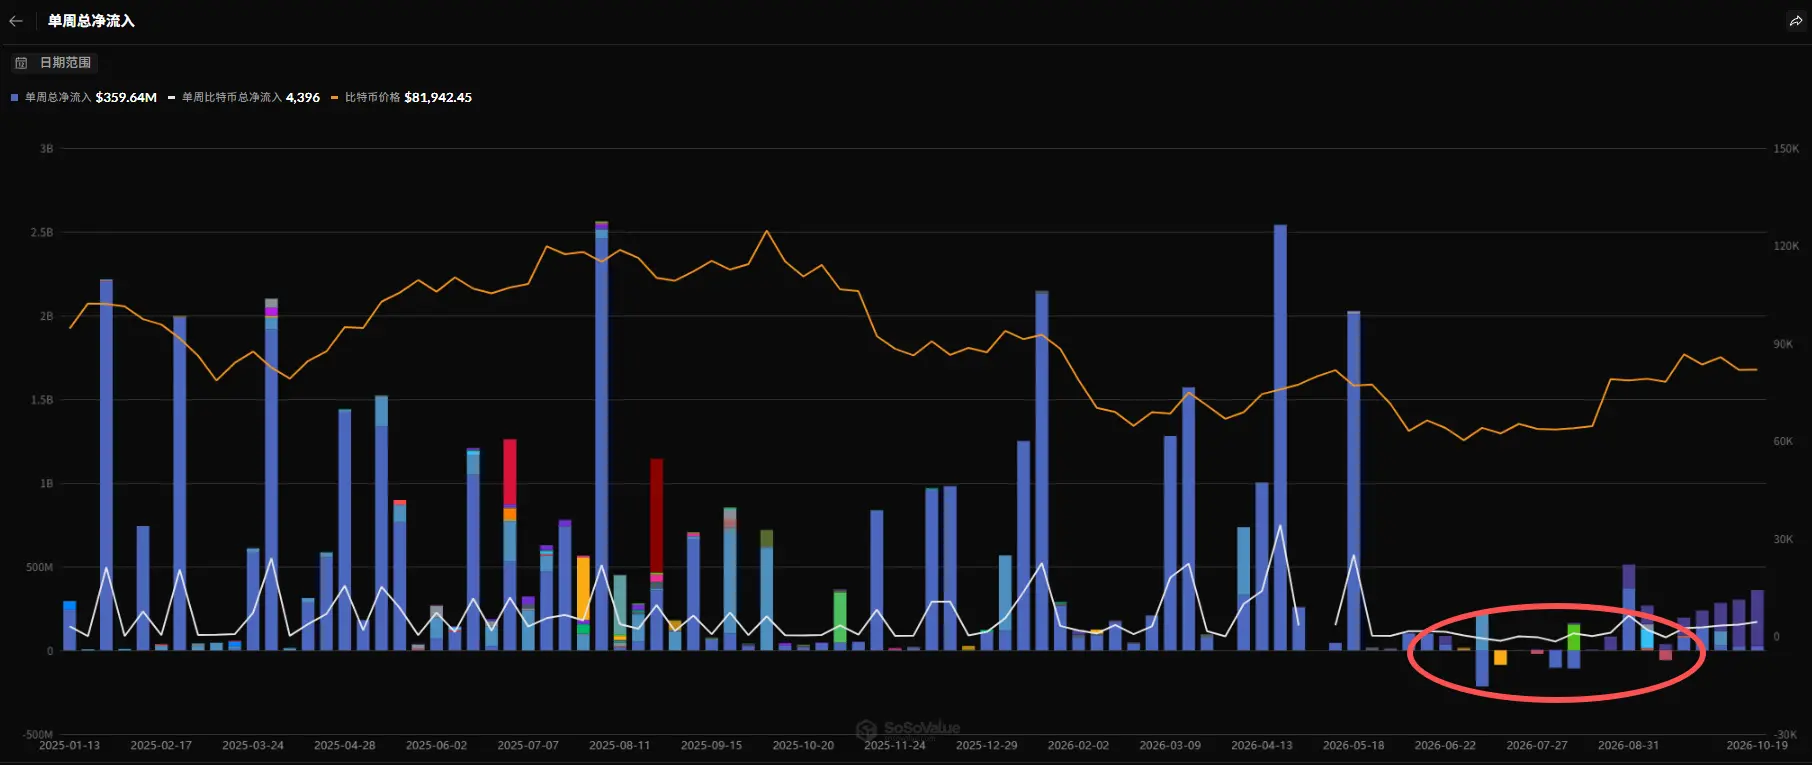
In other words, the support for prices in this bear market largely relies on the financing ability of a single company.
At the same time, another change is occurring on-chain—stablecoins have not exited the market in large quantities as they did in the previous round. CoinGlass data shows that after Bitcoin peaked in October 2025, the market capitalization of USDT continued to grow, peaking around April and May of this year, and has since stabilized at about $183 billion, while USDC has only slightly retreated.
Statistics show that this year, the contraction of stablecoins from their peak is about 3%, far lower than the 26% decline in 2022. Of course, part of the shrinkage in 2022 was due to the collapse of Terra and the Silicon Valley Bank incident.
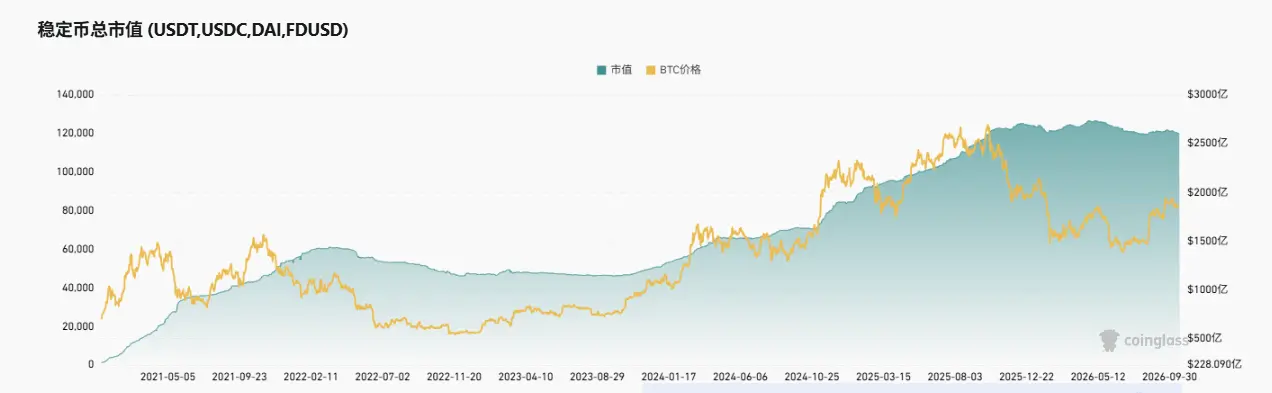
Additionally, on-chain funds have found new places to stay. According to RWA.xyz data, the scale of tokenized U.S. Treasury bonds increased from about $9 billion in October 2025 to a high of about $16 billion in mid-year, then began to decline after Bitcoin rebounded, currently around $14.5 billion.
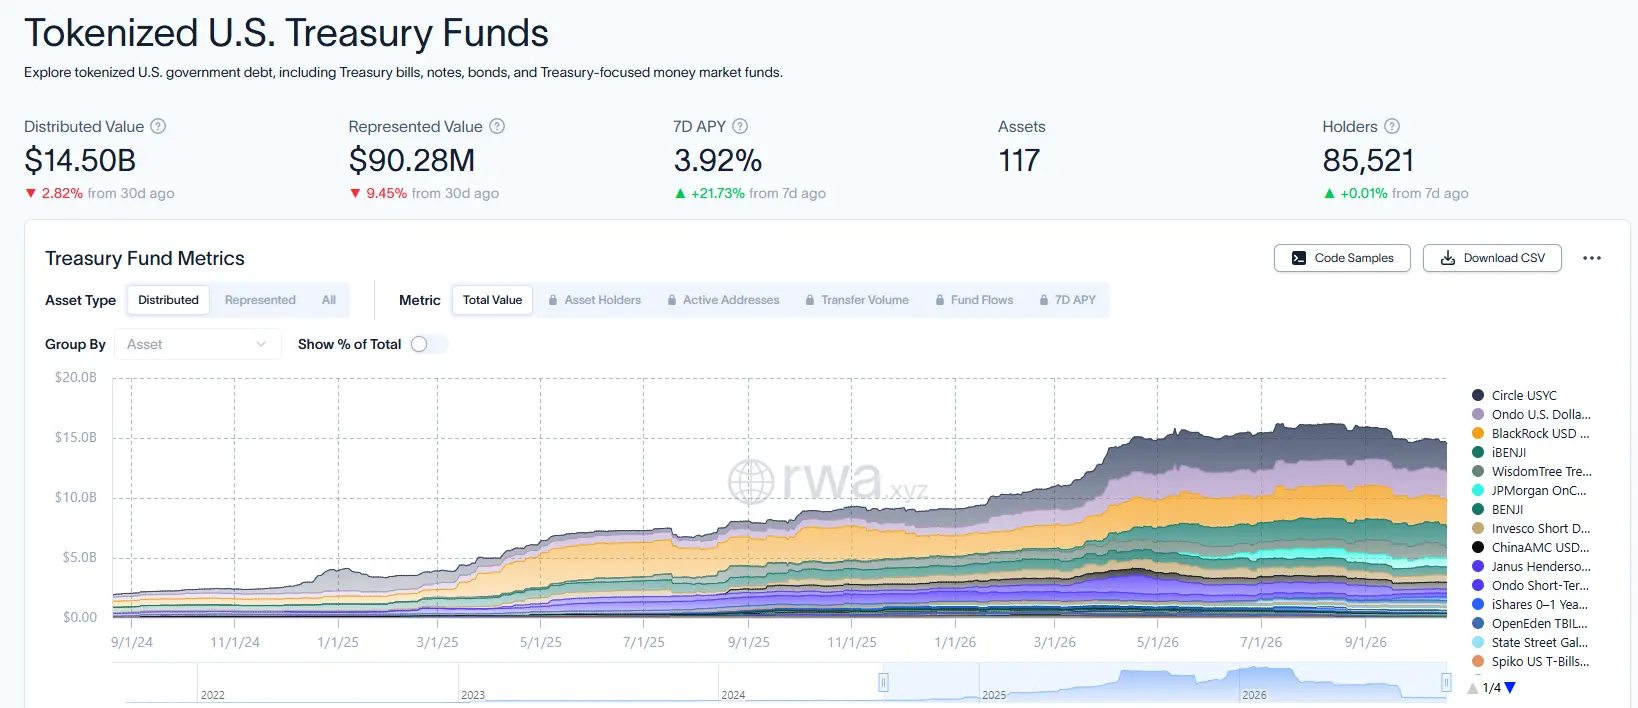
The holders of tokenized Treasury bonds number about 85,500, primarily institutions and DeFi protocols, and the scale is much smaller than Strategy's purchases, but there were almost no such outlets during the previous bear market.
On the other hand, the revenue structure of exchanges is also changing. According to Dune data dashboards, in mid-December 2025, the HIP-3 market on Hyperliquid, primarily consisting of stocks, indices, and commodities, accounted for only 4% of daily trading volume. By this summer, it had reached 40% to 60% on most trading days, peaking at 74% on July 30.
This includes factors related to the shrinking of crypto asset transactions, but during a crypto market downturn, exchanges have indeed developed businesses that do not rely on coin prices.
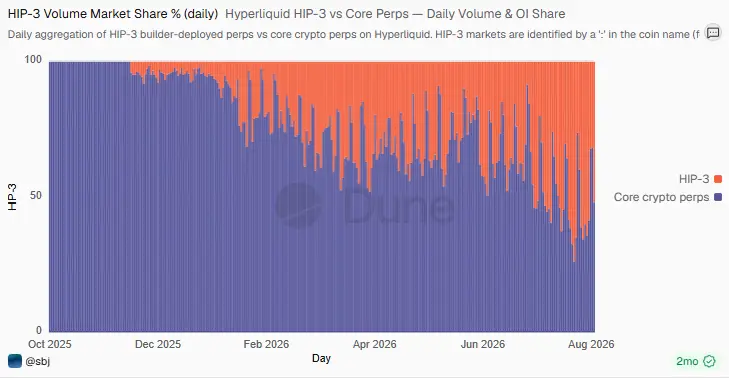
Crypto researcher Haotian believes that the crypto industry is shifting from a bull market in asset issuance to a bull market in the distribution of global assets on-chain. In other words, in the next bull market, some incremental funds will flow into tokenized U.S. stocks, which may flatten the peak of the bull market.
At the same time, the impact of halving itself is diminishing. Currently, the Bitcoin block reward is 3.125 coins, which will drop to 1.5625 coins in 2028. When traders on crypto platforms are simultaneously focused on earnings season and Federal Reserve meetings, the crypto market cycle will more closely follow the rhythm of global liquidity and U.S. stocks.
3. The Crypto Market Needs U.S. Stocks Far More Than U.S. Stocks Need Crypto
For companies like Broadcom and Verizon, being tokenized offers almost no benefits; they neither lack liquidity nor financing channels. According to CoinFound, the trading volume of overseas tokenized stocks compared to traditional market trading volume has a median of only 0.084% for 49 stocks.
Although Wall Street is also promoting tokenization, they are taking a different path. In December 2025, DTC received a no-action letter from the SEC, allowing it to convert the securities it custodies into on-chain tokens, covering Russell 1000 constituents, which account for about 95% of the investable market capitalization of U.S. stocks. At Nasdaq, tokenized shares are matched with traditional shares on the same order book, with the only difference being the delivery method after the transaction.
This route does not rely on stablecoins, and tokens can only be transferred between wallets registered with DTC. Michael Winnike, the strategic head of DTCC, believes that tokenization should transform market functions while retaining the security guarantees that existing markets rely on.
Conversely, crypto funds cannot support the tokenization market of U.S. stocks. Decentralisedco estimates that foreign investors hold approximately $19.86 trillion in U.S. stocks, and even if one-tenth of all stablecoins were to flow into stock tokens, it would only increase by about $31 billion, with the remaining increment needing to come from stocks already held in brokerage accounts.
What is more noteworthy is what crypto funds are buying. Data from RWA.xyz shows that as of October 19, the scale of on-chain tokenized stocks is approximately $3.45 billion. Among them, tokens related to Strategy total about $368 million, and those related to Circle are about $307 million, together accounting for approximately 19.6%, which is 2.6 times the total of four broad-based index products.
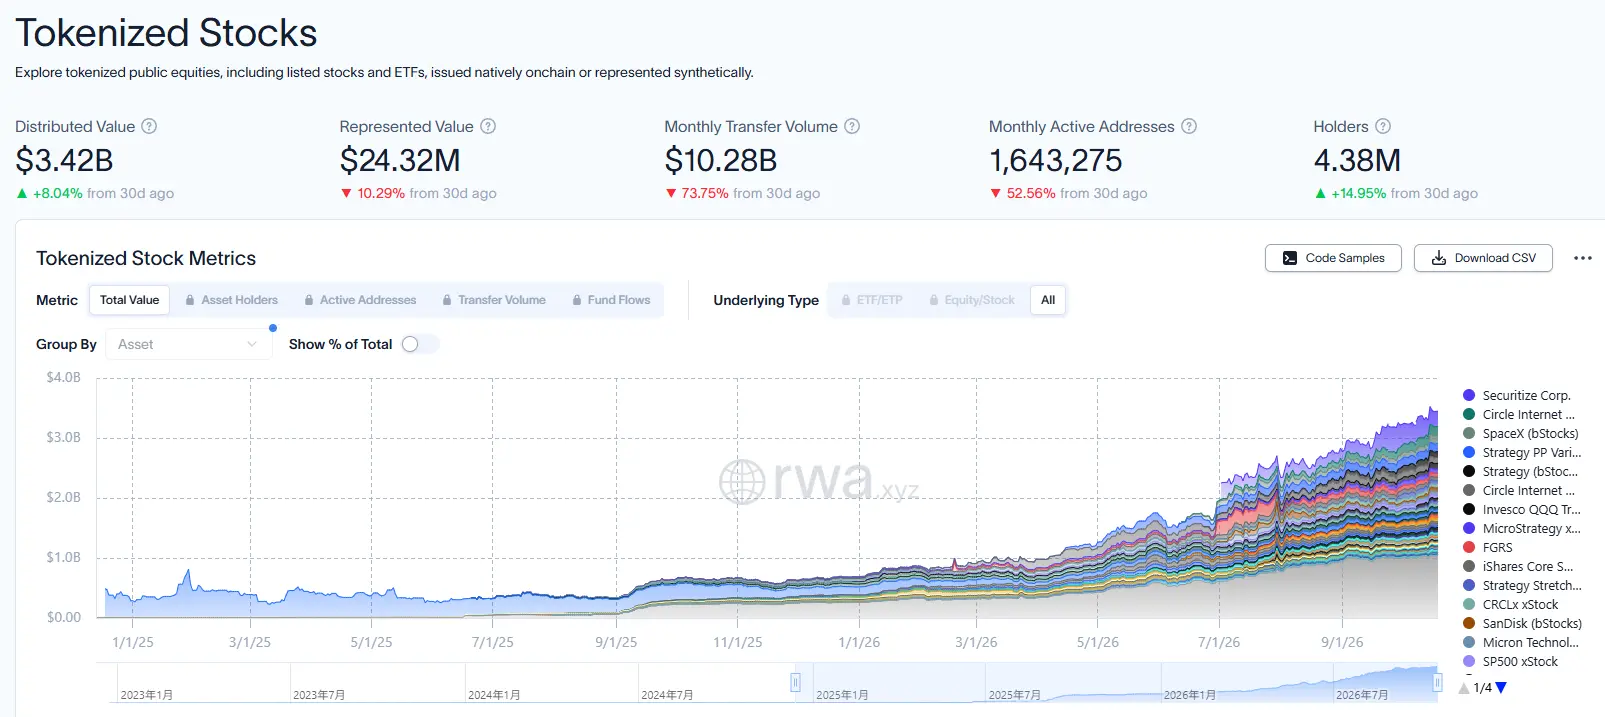
CoinFound indicates that the top three U.S. stocks purchased by crypto funds are Circle, Strategy, and Coinbase, which rise and fall in tandem with the crypto market, making such holdings difficult to diversify risk.
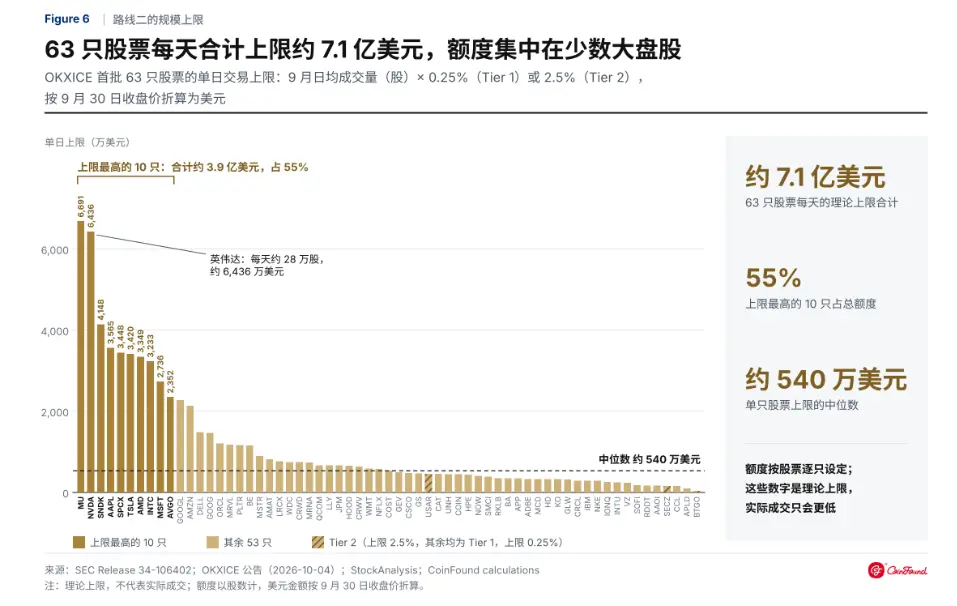
Forms that can stabilize are also the most tightly regulated. According to SEC rules, the tokenized trading volume of a single stock cannot exceed a certain percentage of the average daily trading volume of the previous month, with large-cap stocks at 0.25% and other stocks at 2.5%. Calculations show that the first batch of 63 stocks on OKXICE has a daily total limit of about $710 million, with Nvidia having a maximum of about $64 million per day. Coupled with the issuer's veto power, compliant routes are unlikely to scale up in the short term.
At the same time, the open interest of stocks, indices, and ETF perpetual contracts on tradeXYZ is about $3.01 billion, equivalent to 94% of the total value of all on-chain stock tokens. At the beginning of September, a memecoin liquidity pool on Robinhood Chain held 53% of all tokenized HIMS, and a buy order of about $39,000 pushed the token price to $132.64, while the New York closing price was only $28.84.
The crypto market needs U.S. stocks to smooth out cycles but can only obtain them according to Wall Street's rules, while the compliant forms that can stabilize are the most restricted. This may be why tokenizing U.S. stocks sounds good but takes effect very slowly.
Conclusion
For a long time, the root cause of the crypto market's boom and bust has been that the value of most assets comes from the market's expectations of crypto itself. Rising prices attract funds, which in turn push prices higher, and the same happens during downturns; the entire market lacks an anchor independent of its own emotions.
Tokenized U.S. stocks and government bonds provide just such an anchor. Their value comes from corporate profits and interest rate levels, with no necessary connection to coin prices. With such assets, funds can remain during bear markets, exchanges and protocols can rely on services to maintain operations, and developers have reasons to plan across cycles.
The premise is that the crypto industry is willing to accept the rules of traditional markets, allowing U.S. stocks to enter the chain in the form of collateral and places where funds reside. If it is only made into another high-leverage chip, it will only bring about more severe fluctuations.
This also means that native tokens will no longer monopolize on-chain capital. However, a crypto market that does not need to be rebuilt every four years may be the most profound significance of tokenization for this industry.
 Risk warning
 Risk warning